Unsecured Commercial Lines of Credit in Fairfax in Fairfax, Virginia
Unsecured Commercial Lines of Credit in Fairfax in Fairfax, Virginia
Unsecured commercial lines of credit in Fairfax, VA offer flexible working capital with no collateral requirement. VIP Business Credit helps Fairfax businesses access these credit lines tied to the company’s EIN, not the owner’s SSN. The firm’s network includes 1,000+ lending options, with clients seeing a significant average approval increase.
Key Takeaways
- Unsecured commercial lines of credit in Fairfax, VA provide flexible working capital without requiring collateral.
- Lenders evaluate unsecured facilities based on the borrower's financial strength and credit history rather than pledged assets.
- Unsecured commercial credit lines close faster since no appraisals, lien filings, or asset documentation are required.
- Businesses pay interest only on borrowed funds, making these lines ideal for managing uneven revenue cycles.
What Makes Unsecured Commercial Credit Different?
Unsecured commercial credit lines carry no collateral requirement. Lenders approve these facilities based entirely on the borrower's financial strength and credit history, not on pledged assets. This fundamental difference reshapes every aspect of qualification, cost, and ongoing management for Fairfax business owners.
Traditional secured lines tie borrowing power to specific assets. A lender might extend credit against equipment, real estate, or receivables. [Unsecured business credit lines] remove that safety net for the lender. Without collateral to seize in a default, underwriting becomes more rigorous. Bank of America states plainly that all programs remain subject to credit approval and loan amounts depend on creditworthiness. The business itself must prove it can repay.
How does collateral affect approval requirements?
Secured lines let businesses leverage assets to strengthen applications. Unsecured facilities demand verified corporate credit profiles instead. Lenders scrutinize revenue consistency, time in business, and banking relationships because no fallback asset exists. For Fairfax companies, this means building EIN-based business credit becomes essential before applying. VIP Business Credit helps entrepreneurs across Northern Virginia build that credit foundation, protecting personal assets while positioning the business for approval.
Why do businesses choose unsecured lines despite stricter terms?
Speed and simplicity drive the decision. A commercial line of credit without collateral requirements closes faster. No appraisals, no lien filings, no asset documentation. The tradeoff is higher interest rates reflecting elevated lender risk. Yet for ongoing operational expenses and short-term cash flow needs, the flexibility justifies the cost. | Feature | Secured Credit Line | Unsecured Credit Line |
|---------|---------------------|----------------------|
| Collateral required | Yes | No |
| Approval speed | Slower | Faster |
| Interest rates | Lower | Higher |
| Underwriting focus | Asset value | Business creditworthiness |
Fairfax companies pursuing working capital lines in the local market benefit from understanding this distinction early. A revolving business line of credit provides reusable capital that matches operational rhythms. VIP Business Credit connects business owners to lenders who evaluate the full picture, not just collateral availability.
What credit profile do lenders expect for unsecured approval?
Lenders want documented business credit separate from personal credit. VIP Business Credit guides Fairfax clients toward EIN-based profiles that demonstrate the company's independent borrowing capacity. Strong profiles include trade lines reporting to business credit bureaus, consistent banking activity, and accurate business identity data across all registrations. Without these elements, unsecured applications face rejection regardless of revenue.
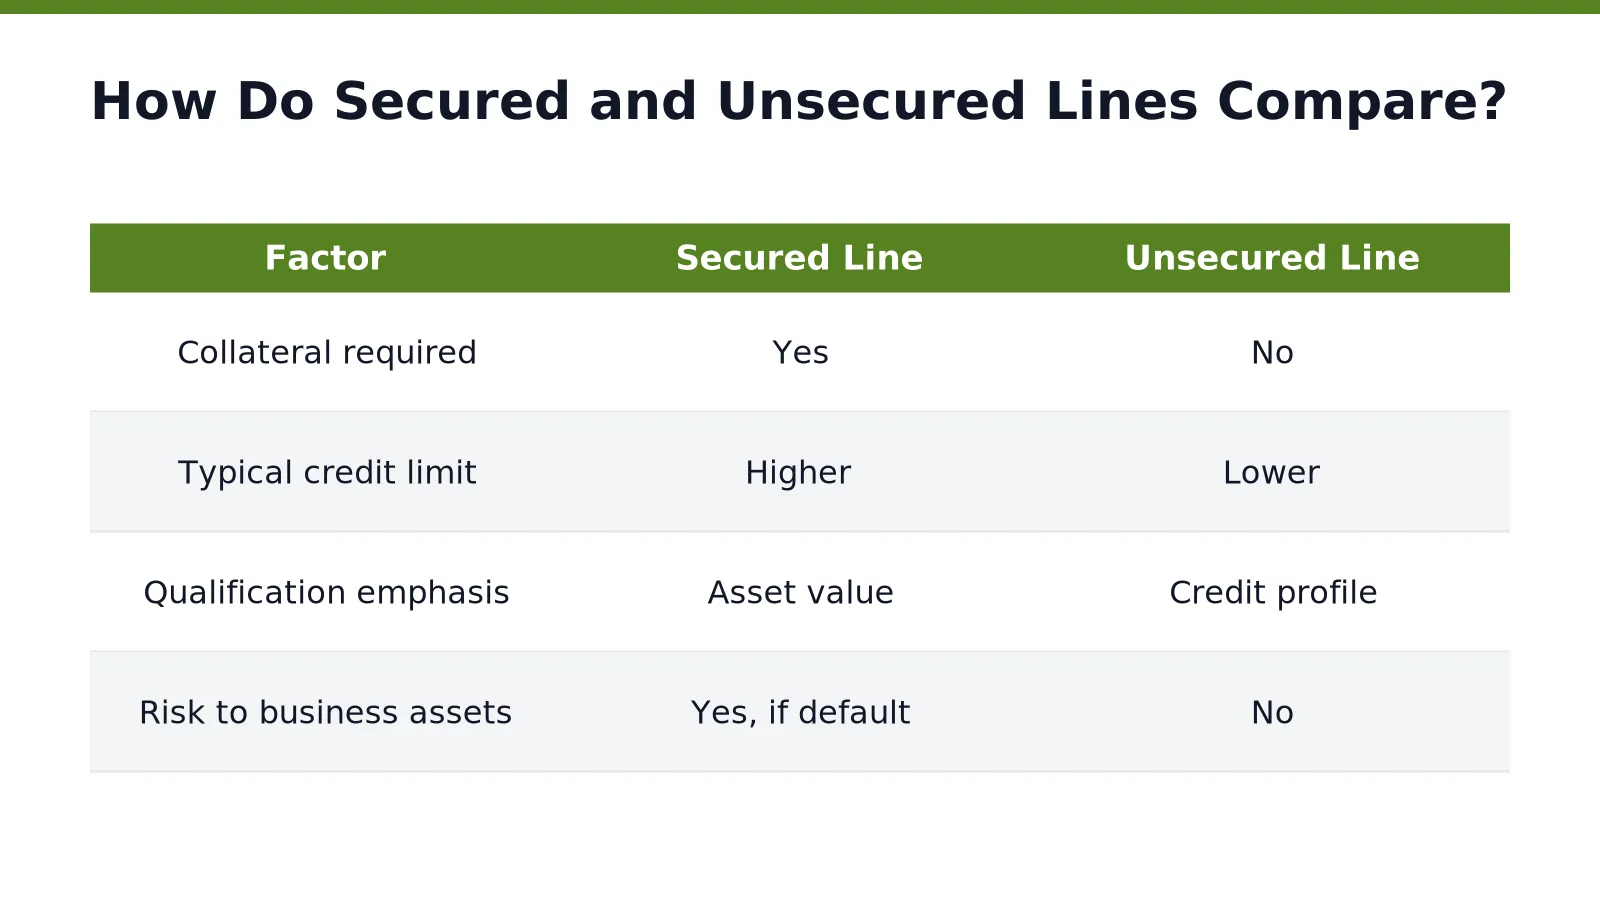
How Do Secured and Unsecured Lines Compare?
Secured lines of credit require collateral, while unsecured lines do not. The trade-off involves credit limits, qualification standards, and risk exposure for Fairfax businesses.
A commercial line of credit secured by business assets, certificates of deposit, or contracted receivables typically unlocks higher borrowing limits. Lenders accept lower risk because the collateral backs the facility. For a Fairfax contractor with equipment or a retailer with receivables, pledging those assets often means access to substantially more working capital.
Unsecured business credit lines demand no collateral. The lender instead evaluates business credit history, revenue consistency, and financial documentation. Strong profiles get approved. Weaker profiles face denials or reduced limits. U.S. Bank confirms that businesses without collateral can still apply for an unsecured line, but underwriting scrutiny increases.
Which Option Costs Less to Carry?
Interest accrues only on the amount actually borrowed, not the full approved limit. This structure makes both secured and unsecured lines efficient for managing uneven cash flow.
How Do Fairfax Businesses Choose?
The decision hinges on available assets and credit strength. VIP Business Credit connects Fairfax companies to over 1,000 national and local lenders offering both structures. The company's advisors help owners evaluate working capital lines in Fairfax against their specific balance sheets and growth plans.
Business owners exploring Fairfax County credit line options benefit from understanding both structures before applying. The right choice protects assets while delivering the capital a growing operation needs.
What Underwriting Standards Do Fairfax Lenders Use?
Fairfax lenders evaluate commercial credit applications through a structured, multi-point underwriting process. Financial documentation, business compliance, and credit history form the foundation of every approval decision. Without meeting these standards, business owners lose access to better rates and higher credit limits.
What Financial Documents Do Lenders Require?
Lenders typically request multi-year tax filings, profit and loss statements, and debt service coverage ratios. These documents demonstrate a business's ability to repay borrowed funds consistently. Bank of America notes that all credit programs remain subject to credit approval, with loan amounts tied directly to demonstrated creditworthiness. Strong financial records signal lower risk to underwriters.
How Does Business Compliance Affect Approval?
Virginia businesses must maintain good standing with the State Corporation Commission and hold proper local licensing. VIP Business Credit helps clients improve lender compliance, which directly impacts qualification for better terms and higher limits. Gaps in registration or lapsed licenses trigger automatic declines. A complete Virginia business loan application requires verified compliance before underwriting begins.
What Role Do Business Credit Profiles Play?
Underwriters pull data from Dun & Bradstreet, Experian Commercial, and Equifax Business to assess corporate creditworthiness. VIP Business Credit emphasizes that verified profiles across all three bureaus are essential for approval. Incomplete or inconsistent profiles reduce scoring and limit available options. Building these profiles before applying prevents unnecessary rejections.
Can Businesses Qualify Without Collateral?
Unsecured business credit lines require strong bank health and consistent cash flow history. MainStreet Bank confirms that lines of credit support ongoing operational expenses while borrowers pay interest only on funds used. Lenders scrutinize average daily balances and revenue trends to gauge repayment capacity. Thin cash flow history disqualifies applicants from unsecured options regardless of personal credit scores.
Commercial lines of credit and working capital lines fairfax providers weigh these factors together. Documentation strength, compliance status, and bureau profiles create a composite risk picture. VIP Business Credit guides Fairfax business owners through each underwriting requirement, ensuring applications meet lender expectations before submission.
How Can Fairfax Businesses Build Credit Readiness?
Credit readiness starts with a foundation that lenders can verify. Fairfax businesses build this foundation through deliberate steps that transform an unproven entity into a credible borrower. Without these steps, companies lose access to commercial lines of credit and unsecured business credit lines that competitors secure routinely.
What Is the First Step Toward Lender Compliance?
Proper entity registration creates the baseline for every credit application. A business must register with the state, obtain a federal Employer Identification Number, and maintain a physical business address with a dedicated phone line. These elements form what underwriters check first. Missing or inconsistent data triggers automatic declines before a human ever reviews the file.
How Do Vendor Trade Lines Strengthen a Credit Profile?
Vendor relationships build payment history that bureaus can score. Fairfax companies open accounts with suppliers who report to commercial credit agencies, then pay every invoice on time. This graduated process creates a verifiable Paydex profile. A strong Paydex score signals reliability to banks evaluating working capital lines fairfax businesses need for daily operations.
VIP Business Credit structures this path for local companies. The firm's advisors guide Fairfax business owners through entity setup, vendor selection, and credit monitoring. Each step addresses a specific underwriting criterion, removing guesswork from the process.
How Long Does It Take to Qualify for Higher Credit Limits?
Timelines depend on consistent, responsible credit use over months, not weeks. Businesses start with smaller vendor accounts and demonstrate payment discipline. As positive data accumulates, lenders extend larger unsecured business credit lines and eventually commercial lines of credit with better terms. VIP Business Credit improves lender compliance so clients qualify for better terms, higher limits, and lower rates. The company's local advisors walk Fairfax entrepreneurs through each stage, ensuring no funding roadblock stalls progress.
Building credit with vendor accounts requires careful preparation. The process separates personal and business liabilities while establishing the payment histories that commercial underwriters demand.
Which Lenders Serve Fairfax Commercial Credit Needs?
Fairfax businesses access commercial lines of credit through national banks, regional institutions, and advisory networks that aggregate lender options. The right choice depends on whether a company needs secured borrowing power, unsecured flexibility, or a broad comparison of terms across multiple providers.
What Types of Credit Lines Do Banks Offer Fairfax Companies?
MainStreet Bank provides both secured and unsecured business lines of credit to Fairfax businesses. Secured options require collateral and typically unlock higher credit limits. Unsecured options skip the collateral requirement but hinge on strong business creditworthiness.
U.S. Bank structures its unsecured business credit lines with competitive interest rates. Borrowers pay interest only on drawn funds. The bank also offers a fixed-rate lock feature on existing balances, giving Fairfax companies predictable repayment costs when rates fluctuate.
Bank of America extends unsecured business lines of credit subject to credit approval. Loan amounts reflect the applicant's creditworthiness and underwriting standards. Fairfax business owners should expect documentation requirements that verify revenue history and operational stability.
How Can Fairfax Businesses Compare Multiple Lenders at Once?
VIP Business Credit connects Fairfax companies to over 1,000 national and local lenders. This network spans traditional banks, alternative finance providers, and Virginia-specific programs. Rather than applying individually to each institution, business owners receive matched options aligned with their credit profile and funding needs.
The advisory approach helps Fairfax firms identify working capital lines fairfax lenders actually approve. Many businesses waste weeks applying to banks whose underwriting criteria they do not meet. A pre-qualification step eliminates that friction.
Does Collateral Matter for Fairfax Commercial Credit Approval?
Collateral changes both the approval odds and the credit limit. Secured lines of credit let Fairfax businesses leverage assets like real estate, equipment, or receivables to access larger pools of capital. U.S. Bank explicitly notes that applying with collateral secures a higher line of credit.
Unsecured lines skip the asset pledge. The trade-off is stricter credit scrutiny. Bank of America's programs underscore this reality: every application faces creditworthiness review, and loan amounts adjust accordingly. Fairfax companies with thinner credit files benefit from working with an advisor who understands which lenders weigh collateral less heavily.
What Are the Red Flags in Commercial Credit Offers?
Red flags in commercial lines of credit offers include guaranteed approval claims, hidden fees, and pressure tactics. These signals often point to predatory financing that harms a business rather than helping it grow.
Lenders who promise approval before reviewing financials misrepresent how underwriting works. Bank of America states plainly that all programs are subject to credit approval and loan amounts depend on creditworthiness. No legitimate lender guarantees funding without first examining a company's financial health. Businesses that accept such offers often face unsustainable rate terms and deceptive advance fees. The damage compounds quickly. VIP Business Credit emphasizes transparent, no-surprise pricing and positions itself as a long-term partner, helping Fairfax business owners steer clear of these traps.
How Do Fee Structures Reveal Predatory Lenders?
Predatory lenders bury costs in complex fee schedules. A fair unsecured business credit line carries clearly stated interest rates and maintenance costs. U.S. Bank notes that competitive-rate products let borrowers pay interest only on the amount drawn, with an option to lock in a fixed rate on existing balances. When a lender refuses to disclose rate structures or prepayment covenants before signing, that opacity signals trouble. Fairfax companies evaluating working capital lines fairfax should demand full fee transparency upfront.
What Makes "Guaranteed Approval" a Warning Sign?
The phrase itself contradicts standard lending practice. Every credible program subjects applications to credit review and underwriting standards. A lender who skips that step either charges predatory rates to offset risk or collects upfront fees and disappears. VIP Business Credit helps Fairfax businesses identify legitimate lenders and avoid these practices. The company combines expert guidance with proven strategies so clients secure funding the right way, without falling for offers that sound too good to be true.
How Should You Manage Working Capital Lines Responsibly?
Responsible management of working capital lines fairfax businesses rely on starts with disciplined utilization. Fairfax business owners who keep balances modest protect both corporate and personal credit ratings. VIP Business Credit emphasizes building business credit tied to an EIN rather than an SSN, which shields personal assets while unlocking larger funding opportunities.
A commercial line of credit works best when deployed against predictable cash flow gaps. MainStreet Bank notes that a business line of credit supports ongoing operational expenses and short-term cash flow, with interest charged only on borrowed funds. Fairfax companies face three recurring pressure points:
- Payroll buffers during slow receivables cycles
- Seasonal inventory purchases ahead of demand spikes
- Bridging the lag between invoicing and client payment
What Does Healthy Credit Utilization Look Like?
Healthy utilization means borrowing only what a Fairfax business can repay within its operating cycle. Keeping balances low relative to the credit limit signals lender compliance and positions the company for better terms, higher limits, and lower rates. VIP Business Credit helps owners improve lender compliance so qualification standards stay favorable.
How Can Fairfax Businesses Prepare for Rate Volatility?
Contingency planning matters. Economic shifts and interest rate changes squeeze margins quickly. Unsecured business credit lines carry variable rates, so Fairfax owners should model repayment scenarios before drawing funds. VIP Business Credit provides education and coaching that helps owners understand underwriting criteria and maintain healthy credit usage over time. That guidance turns a credit line into a strategic tool rather than a liability.
Ready to Secure Your Fairfax Business Line of Credit?
Securing a commercial line of credit in Fairfax, Virginia requires a lender-ready profile and access to the right financial products. VIP Business Credit provides a structured path to both. The company’s local Business Credit Advisors deliver personalized, concierge-level guidance so Fairfax business owners never face funding roadblocks alone. Without this expert navigation, applicants risk repeated denials that damage their business credit profile and delay critical working capital.
The process begins with a clear view of how underwriters evaluate a business. VIP Business Credit uses proprietary tools to reveal exactly how lenders view a company and to identify specific eligibility gaps. This diagnostic step transforms a confusing application process into a targeted action plan. Fairfax entrepreneurs stop guessing and start fixing the precise issues that block approvals.
How does the Capital-Ready Framework help Fairfax businesses qualify for funding?
The Capital-Ready Framework builds a credit profile tied to the company’s EIN rather than the owner’s personal credit. This approach helps businesses qualify for unsecured business credit lines without personal guarantees. The framework combines credit-building strategies with direct lender access. Business owners protect personal assets while establishing standalone corporate creditworthiness.
What lending options are available through VIP Business Credit’s network?
Fairfax businesses gain access to over 1,000 national and local lending options through the company’s extensive network. This includes working capital lines in Fairfax tailored specifically for Virginia-based companies. The breadth of options means a construction firm in Fairfax City and a tech consultancy in Merrifield both find products matched to their revenue cycles and industry risk profiles. Advisors match each business to the most favorable terms available, not just the easiest approval.
FAQ
What makes unsecured commercial lines of credit different from secured lines?
Unsecured lines require no collateral, so lenders approve based on business creditworthiness and financial strength rather than asset value.
How does VIP Business Credit help Fairfax businesses get approved?
VIP Business Credit helps entrepreneurs build EIN-based business credit and connects them to over 1,000 national and local lenders.
Why do businesses choose unsecured lines despite higher interest rates?
Speed and simplicity drive the choice, no appraisals or lien filings are needed, and businesses pay interest only on borrowed funds.
Conclusion
Fairfax business owners who apply these principles and work with a local advisor avoid the traps that derail funding. The path to an unsecured commercial line of credit requires a lender-ready profile built on EIN-based credit, disciplined utilization, and transparent fee structures. VIP Business Credit provides the diagnostic tools and personalized guidance to turn that requirement into a clear, executable plan.


