Virginia Small Business Loans: Best Funding Options for Local Entrepreneurs in 2026
Virginia Small Business Loans: Best Funding Options for Local Entrepreneurs in 2026
Finding the right business loans in Virginia takes some legwork, but local entrepreneurs have more options available than many realize. This article covers the best funding paths for Virginia small businesses, including SBA loans, microloans, and grants, along with the application process and eligibility requirements for each. Securing capital to launch or grow a business is rarely simple, so we break down what each loan type involves, how the application works, and how to put your business in the strongest position for loan readiness.
Key Takeaways
- Virginia small business loans include SBA loans, microloans, grants, business credit lines, merchant cash advances, and revenue-based financing.
- SBA loans offer lower interest rates, longer repayment terms, and require a solid business plan and good credit history.
- Microloans support startups and small businesses with lower interest rates and simpler application processes.
- Business credit lines provide flexible funding with interest charged only on the amount borrowed.
- Merchant cash advances offer quick cash based on future credit card sales but often have higher fees.
- Grants provide non-repayable funds but require detailed proposals and have competitive application processes.
- Improving business credit through timely payments and reducing debt increases loan eligibility and better financing terms.
- Loan application steps include researching options, preparing documentation, submitting applications, and awaiting lender approval.
- Local banks, credit unions, and online lenders offer varied terms and rates for Virginia small business loans.
Funding Options
Virginia small businesses have several funding avenues to explore, each with its own eligibility rules, application steps, and trade-offs. Weighing these differences side by side makes it easier to pick the funding source that actually fits the business.
SBA Loans

SBA loans are a popular choice for small businesses due to their favorable terms and lower interest rates. These loans are partially guaranteed by the Small Business Administration, which reduces the risk for lenders. To qualify, businesses typically need to demonstrate a solid business plan, good credit history, and the ability to repay the loan. The benefits of SBA loans include longer repayment terms and lower down payments, making them accessible for many entrepreneurs. The application process involves submitting detailed financial documents and a business plan, which can take several weeks.
Business Credit Lines
Business credit lines offer flexibility for entrepreneurs who need access to funds on an as-needed basis. These lines of credit allow businesses to borrow up to a certain limit and only pay interest on the amount drawn. Eligibility for business credit lines often depends on the business's creditworthiness and financial history. The advantages include quick access to funds and the ability to manage cash flow effectively. Entrepreneurs can use these lines for various expenses, from inventory purchases to unexpected costs.
Merchant Cash Advances
Merchant cash advances provide a lump sum of cash to businesses in exchange for a percentage of future credit card sales. This option is particularly suitable for businesses with high credit card sales but may come with higher fees and interest rates. Eligibility requirements are generally less stringent than traditional loans, making it an attractive option for businesses that may not qualify for other funding types. However, the costs can add up quickly, so it's essential for entrepreneurs to weigh the pros and cons before proceeding.
Microloans

Microloans are smaller loans typically offered by non-profit organizations and community lenders. They are designed to support startups and small businesses that may not qualify for traditional financing. Microloans often come with lower interest rates and more lenient eligibility criteria. Entrepreneurs can use these funds for various purposes, including purchasing equipment or covering operational costs. The application process is usually straightforward, requiring basic financial information and a business plan.
Microfinance, the broader practice microloans fall under, has been studied for its effects on poverty reduction and community empowerment.
Microfinance: Values, Limits, and Community Empowerment The purpose of this article is to present and discuss the values and limits of microfinance within the context of poverty reduction, international development, and community empowerment. The main thesis is that microfinance requires a more complex strategy than merely the provision of credits. Before microfinance: The social value of microsavings in Vincentian poverty reduction, M Tavanti, 2013
Grants
Grants are a highly sought-after funding option as they do not require repayment. Various organizations, including government agencies and private foundations, offer grants to support small businesses, particularly those in underserved communities or specific industries. Eligibility for grants can vary widely, and the application process often involves detailed proposals outlining how the funds will be used. While grants can provide significant financial support, competition can be fierce, and not all applicants will receive funding.
Revenue-Based Financing
Revenue-based financing allows businesses to receive capital in exchange for a percentage of future revenue. This option is particularly appealing for startups that may not have a strong credit history but have a solid revenue stream. The eligibility criteria typically focus on the business's revenue projections rather than credit scores. The advantages include flexible repayment terms that align with the business's cash flow, making it easier for entrepreneurs to manage their finances.
Application Process Overview
Understanding the application process for business loans is crucial for entrepreneurs seeking funding. The steps involved can vary depending on the type of loan, but there are common elements that all applicants should be aware of.
- Research Funding Options: Identify the types of loans that best suit your business needs and eligibility.
- Prepare Documentation: Gather necessary financial documents, including tax returns, bank statements, and a business plan.
- Submit Application: Complete the loan application and submit it along with the required documentation.
- Await Approval: Lenders will review your application, which may take several days to weeks.
- Receive Funds: Once approved, funds will be disbursed according to the lender's terms.
Potential Lenders
In Virginia, various lenders offer business loans, including local banks, credit unions, and online lenders. Each lender may have different terms, interest rates, and eligibility criteria, so it's essential for entrepreneurs to shop around and compare options.
- Local Banks: Often provide personalized service and may have specific programs for local businesses.
- Credit Unions: Typically offer lower interest rates and fees compared to traditional banks.
- Online Lenders: Provide quick access to funds but may have higher interest rates and fees.
What Are the Top Business Loan Types Available in Virginia?
Virginia entrepreneurs have access to several business loan types, each catering to different needs and circumstances. The most common types include:
- SBA Loans: Long-term financing with lower interest rates.
- Business Credit Lines: Flexible funding for ongoing expenses.
- Merchant Cash Advances: Quick cash based on future sales.
- Microloans: Smaller loans for startups and small businesses.
- Grants: Non-repayable funds for specific projects or demographics.
Each type serves a different stage and need, so the right fit usually comes down to how fast the funds are needed, how established the business is, and what it can offer as collateral.
How Do SBA 7 Loans Support Virginia Entrepreneurs?
SBA 7(a) loans are particularly beneficial for Virginia entrepreneurs as they offer flexible financing options for various business needs. These loans can be used for purchasing equipment, real estate, or working capital. The benefits include lower down payments and longer repayment terms, making them accessible for many small businesses. To qualify, businesses must meet specific eligibility criteria, including size standards and creditworthiness. The application process involves submitting a detailed business plan and financial statements, which can take time but ultimately provides valuable support for growth.
What Are Microloan Programs and Their Benefits in Virginia?
Microloan programs in Virginia are designed to assist small businesses and startups that may not qualify for traditional loans. These loans typically range from $500 to $50,000 and are offered by non-profit organizations and community lenders. The benefits of microloans include lower interest rates, flexible repayment terms, and a focus on supporting underserved communities. Entrepreneurs can use these funds for various purposes, such as purchasing inventory or equipment. The application process is generally straightforward, requiring basic financial information and a business plan.
Which Are the Best Business Lenders in Virginia for Small Businesses?
When seeking business loans, it's essential to identify the best lenders that cater to small businesses in Virginia. Some of the top lenders include:
- Local Banks: Often provide personalized service and tailored loan products.
- Credit Unions: Typically offer lower interest rates and fees.
- Online Lenders: Provide quick access to funds but may have higher costs.
The right lender often comes down to what matters most for a given business: a personal relationship, the lowest possible rate, or speed of funding.
How Can Virginia Entrepreneurs Improve Business Credit to Qualify for Loans?
Improving business credit is crucial for Virginia entrepreneurs looking to qualify for loans. Here are some strategies to enhance creditworthiness:
- Pay Bills on Time: Consistent, timely payments positively impact credit scores.
- Reduce Debt: Lowering outstanding debts can improve credit utilization ratios.
- Monitor Credit Reports: Regularly checking credit reports helps identify and rectify errors.
Each of these habits builds on the others: on-time payments and lower balances both feed directly into the credit score lenders look at first.
What Are Effective Credit Building Strategies for Virginia Businesses?
Building strong business credit is essential for accessing financing options. Effective strategies include:
- Establishing Trade Lines: Work with suppliers that report to credit bureaus.
- Using Business Credit Cards: Regularly use and pay off business credit cards to build credit history.
- Registering with Credit Bureaus: Ensure your business is registered with major credit bureaus to establish a credit profile.
Consistency matters more than any single action here: a business that keeps these habits up over time tends to see steadier improvement in its credit profile and the terms it qualifies for.
How Does Business Credit Impact Loan Eligibility and Terms?
Business credit plays a significant role in determining loan eligibility and terms. Lenders assess credit scores to evaluate the risk of lending to a business. A higher credit score can lead to:
- Lower Interest Rates: Businesses with strong credit histories often qualify for better rates.
- Higher Loan Amounts: Good credit can increase the amount a lender is willing to offer.
- Favorable Terms: Businesses with solid credit may receive longer repayment periods and lower fees.
In short, credit health isn't just a qualifying hurdle, it directly shapes how much a business can borrow and what it will cost.
What Are the Key Eligibility Criteria for Business Loans in Virginia?
Eligibility criteria for business loans in Virginia can vary by lender and loan type. Common requirements include:
- Credit Score: A minimum credit score is often required.
- Business Plan: A detailed business plan outlining financial projections and goals.
- Financial Statements: Recent financial statements, including income statements and balance sheets.
Lenders use these three pieces together to judge risk, so a weak spot in one area is often offset by strength in another.
Which Documentation and Financial Metrics Do Lenders Require?
When applying for business loans, lenders typically require specific documentation and financial metrics, including:
- Tax Returns: Personal and business tax returns for the past few years.
- Bank Statements: Recent bank statements to assess cash flow.
- Financial Projections: Forecasts demonstrating the business's potential for growth.
Having this paperwork organized ahead of time is one of the simplest ways to keep an application moving instead of stalling in back-and-forth requests.
How Do Startup Funding Requirements Differ from Established Businesses?
Startup funding requirements often differ significantly from those of established businesses. Startups may face more stringent criteria due to their lack of financial history. Key differences include:
- Credit History: Startups may not have an established credit history, making it challenging to secure loans.
- Collateral: Established businesses may have assets to offer as collateral, while startups often do not.
- Business Plans: Startups must present detailed business plans to demonstrate viability and potential for success.
Because of this, a strong, well-documented business plan often carries more weight for a startup than it would for a company with years of financial records behind it.
How Do Interest Rates and Loan Terms Affect Virginia Small Business Financing?
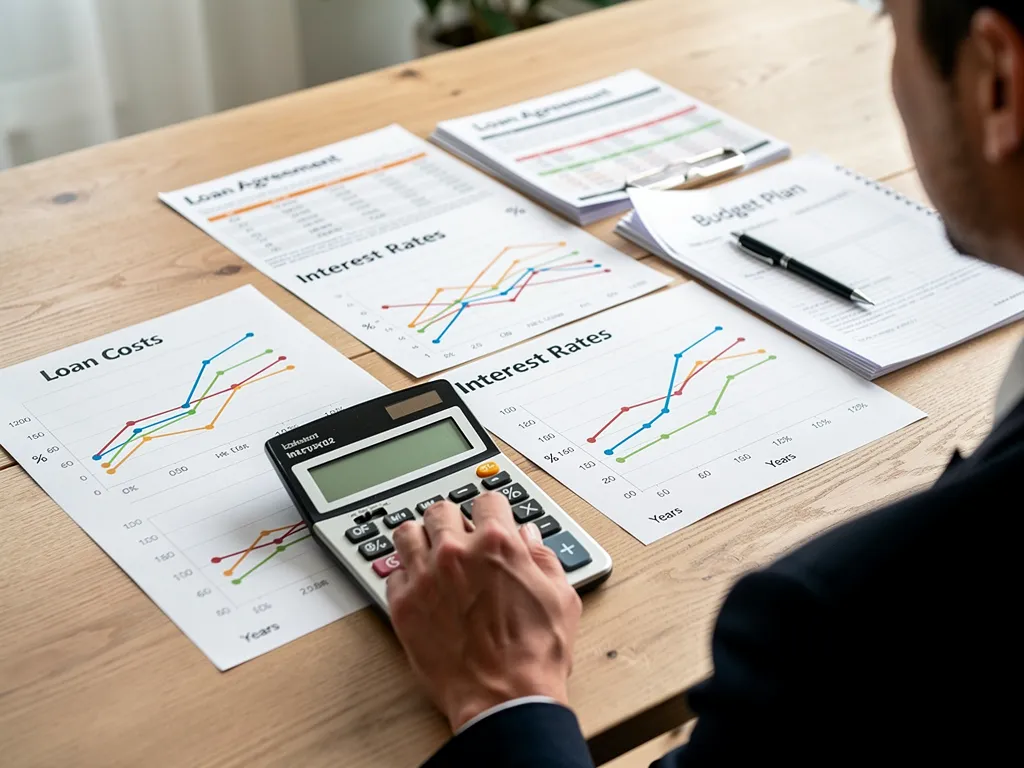
Interest rates and loan terms significantly impact the overall cost of financing for small businesses. Higher interest rates can lead to increased monthly payments, affecting cash flow. Conversely, lower rates can make loans more affordable. Additionally, the length of the loan term influences the total interest paid over time. A loan with a lower rate but a shorter term can sometimes cost more month to month than a longer loan at a slightly higher rate, so it's worth running both scenarios before signing.
What Are the Current Interest Rate Trends for Virginia Business Loans in 2026?
As of 2026, interest rates for business loans in Virginia are influenced by various economic factors, including inflation and the Federal Reserve's monetary policy. Current trends indicate a gradual increase in rates, which may affect borrowing costs for entrepreneurs. Businesses that lock in financing early, before rates climb further, often fare better than those who wait.
How Do Repayment Terms Vary Among Different Loan Types?
Repayment terms can vary significantly among different loan types, impacting the overall cost of borrowing. For example:
- SBA Loans: Typically offer longer repayment terms, often up to 25 years.
- Business Credit Lines: May require monthly payments based on the amount drawn.
- Merchant Cash Advances: Repayment is based on a percentage of daily sales, which can fluctuate.
A longer term generally means smaller payments but more interest paid overall, while a shorter term does the opposite, so the right choice depends on how the business handles cash flow month to month.
What Is the Step-by-Step Loan Application Process for Virginia Entrepreneurs?
The loan application process can be complex, but following a structured approach can simplify it. Here's a step-by-step guide:
- Research Loan Options: Identify the best loan types for your business needs.
- Gather Documentation: Collect necessary financial documents and a business plan.
- Complete Application: Fill out the loan application accurately and thoroughly.
- Submit Application: Send the application and supporting documents to the lender.
- Follow Up: Stay in contact with the lender to check on the status of your application.
Entrepreneurs who stay organized through each of these steps, and follow up proactively rather than waiting silently, tend to move through the process faster.
How to Prepare and Submit a Successful Business Loan Application?
Preparing a successful business loan application requires careful planning and attention to detail. Key steps include:
- Develop a Comprehensive Business Plan: Clearly outline your business goals, strategies, and financial projections.
- Organize Financial Documents: Ensure all financial statements and tax returns are up to date and accurate.
- Practice Your Pitch: Be ready to explain your business model and how the loan will be used.
Lenders notice when an owner can speak confidently and specifically about their numbers, it signals the business is being run with discipline.
What Are Typical Approval Timelines and Next Steps?
Approval timelines for business loans can vary based on the lender and loan type. Generally, entrepreneurs can expect:
- SBA Loans: 4-6 weeks for approval.
- Business Credit Lines: 1-2 weeks for processing.
- Merchant Cash Advances: Often approved within 24-48 hours.
After approval, businesses should be prepared to discuss the next steps, including fund disbursement and repayment terms.
Which Local Business Loan Programs in Virginia Offer the Best Support for Startups?
Several local business loan programs in Virginia provide excellent support for startups. These programs often focus on underserved communities and offer favorable terms. Key programs include:
- Virginia Small Business Financing Authority: Offers various loan programs tailored for startups.
- Community Development Financial Institutions (CDFIs): Provide microloans and technical assistance to new businesses.
- Local Economic Development Programs: Many cities have initiatives to support local entrepreneurs with funding and resources.
For a startup without a long credit history, these local and community-focused programs are often more accessible than a conventional bank loan.
Local Funding Resources Across Virginia
Funding needs often look different depending on where a business is based, and Virginia entrepreneurs benefit from resources tailored to their local market. VIP Business Credit supports small business owners throughout the region, including those seeking business credit in Sterling, VA, business loans in Ashburn, VA, and business funding in Tysons, VA.
Entrepreneurs further afield have local support too: businesses in Reston and Herndon can tap into dedicated credit-building guidance, while those in Arlington have access to working capital resources suited to their market. Owners in Fairfax County and across the broader DC Metro area can likewise find funding options shaped by their local business environment.
What State and Community-Based Funding Options Are Available?
Virginia offers a range of state and community-based funding options for entrepreneurs. These include:
- State Grants: Various state agencies provide grants for specific industries or projects.
- Local Business Development Programs: Many local governments offer funding and resources to support small businesses.
- Non-Profit Organizations: Several non-profits focus on providing financial assistance and mentorship to entrepreneurs.
These state and community resources often fly under the radar compared to bank loans, yet they can be just as valuable for the right business. Navigating these complexities can feel overwhelming, but entrepreneurs don't have to go it alone: answers to common business loan FAQs are available on dedicated resources, and our blog offers further guidance for those working to secure the capital needed to launch or expand a business. When it's time to take the next step, VIP Business Funds offers tailored solutions. Contact us today.
About The Author
Lee Johnson is the Co-Founder and CEO of VIP Business Credit, bringing over 25 years of experience helping entrepreneurs identify the right business loan types and meet startup funding requirements. Based in Sterling, VA, Lee and his team at VIPBizFunds.com specialize in guiding new business owners from credit building to loan approval. Reach out today to get expert support on your funding journey.
Contact VIP Business Credit
- 📞 Phone: +1 (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Consultation: Call to schedule your free consultation
- 🌐 Website: vipbizfunds.com
- 🎯 FREE Business Funding Pre-Qualification Scan: Start your scan
Serving Sterling, VA and surrounding areas.
Research & Sources
Several of the figures and standards discussed in this article are grounded in guidance from federal and research sources:
- SBA 7(a) Loan Program: The U.S. Small Business Administration publishes official size standards, eligibility requirements, and repayment terms for 7(a) loans, including the long repayment periods and lower down payment structures referenced above. Entrepreneurs can review current program details directly through the SBA.
- Interest Rate Trends: Broader borrowing-cost trends, including the influence of inflation and Federal Reserve monetary policy on small business lending, are tracked through Federal Reserve economic data and reporting.
- Microfinance and Community Lending: The role of microloans in supporting underserved entrepreneurs and community development is documented in academic research on microfinance, including work examining its value and limitations in poverty reduction and community empowerment (Tavanti, 2013), cited earlier in this article.
Entrepreneurs are encouraged to consult these primary sources directly for the most current rates, terms, and program requirements, as lending conditions can change.


