Understanding Business Fundability and Loan Pre-Qualification: The Role of Soft Credit Check Loans
Understanding Business Fundability and Loan Pre-Qualification: The Role of Soft Credit Check Loans
Achieving strong business fundability is a foundational step for any company seeking financing. Loan pre-qualification provides a quick, risk-free way for business owners to assess potential borrowing options using soft credit check loans, without affecting personal credit scores. VIP Business Credit’s Business Fundability Scan delivers insights in 2–5 minutes, revealing the types of loans, credit lines, and vendor terms a business likely qualifies for, while mapping a clear path toward enhanced business credit strength and lending eligibility.
Key Insights on Business Fundability, Loan Pre-Qualification, and Soft Credit Check Loans
- Business fundability underpins successful loan applications by demonstrating creditworthiness based on consistent identity data and strong trade credit profiles.
- Loan pre-qualification offers a preliminary estimate of borrowing potential using self-reported data and soft credit check loans that protect personal credit scores.
- Entrepreneurs in Northern Virginia and the Greater Washington, DC area benefit from localized guidance to quickly understand their EIN-based loan eligibility.
- The concepts of pre-qualification and pre-approval differ significantly: pre-qualification is an early, informal assessment, while pre-approval is a more formal lender commitment supported by verified documentation.
What Is Loan Pre-Qualification and How Does It Relate to Business Fundability?
Loan pre-qualification acts as a rapid, initial evaluation of a business’s credit capacity, usually based on self-reported financial metrics instead of full documentation. Lenders use this process to estimate how much capital a business might obtain without in-depth verification, while business fundability reflects the company’s overall financial health, credit history, and reporting consistency that underwriters consider during formal lending decisions.
This early-step is designed for speed and clarity—business owners learn in minutes if their financing goals align with lender expectations and can then plan next steps accordingly, saving time and effort. Importantly, pre-qualification relies heavily on progress in business fundability factors to present a realistic borrowing outlook.
Does Loan Pre-Qualification Guarantee Funding?
No. Loan pre-qualification signals potential eligibility but does not guarantee approval. Only after verifying documentation and conducting comprehensive underwriting—often including a review of business fundability metrics—will lenders issue a final decision.
Why Are Loan Pre-Qualification and Business Fundability Important for Busy Business Owners?
They streamline the financing process by prioritizing lenders and loan products that fit the business’s current profile. Instead of submitting multiple uninformed applications, owners gain a clear roadmap.
A typical loan pre-qualification process, enhanced by robust analysis of business fundability, clarifies:
- Which lenders and funding programs are realistic matches today
- Which require improvements in credit or documentation before applying
- What specific credit-building or operational actions can broaden financing options
Through its extensive lender network covering national banks, local financial institutions, alternative financing sources, and specialty programs, VIP Business Credit tailors recommendations based on verified business credit profile data and business fundability scores instead of guesswork.
The Critical Role of Soft Credit Check Loans in Loan Pre-Qualification
Soft credit check loans allow business owners to assess financing options without triggering a hard inquiry on their personal credit report. Unlike hard pulls, which can lower credit scores and require extensive documentation, soft checks are non-invasive and perfect for the exploratory phase of loan pre-qualification.
This approach aligns perfectly with business fundability goals by enabling owners to receive prompt, no-risk feedback on borrowing capacity and approximate loan terms in minutes rather than days.
Will Soft Credit Check Loans Affect My Personal Credit Score?
No. Since soft credit checks do not impact personal credit scores, business owners can shop around and compare multiple lenders freely before formal applications.
How Does an Advisor Enhance the Pre-Qualification Process?
Expert Business Credit Advisors provide personalized guidance throughout the soft credit check phase. They interpret lender criteria and help owners understand their business fundability status. This is especially valuable in Northern Virginia and the Greater Washington, DC region where localized support helps businesses separate credit profiles tied to their EIN from personal Social Security numbers, reducing personal risk and improving funding outcomes.
- No hard inquiry or credit score impact
- Fast results in minutes, not days
- Dedicated local advisor support
- Credit-building linked to the business EIN, not the owner's personal SSN
Loan Pre-Qualification vs. Small Business Loan Pre-Approval: Key Differences
Though both terms often appear together, loan pre-qualification and small business loan pre-approval signify different stages in the lending process related to business fundability.
Pre-qualification is an early assessment using self-reported information granting a preliminary estimate of borrowing capacity without verified documents. In contrast, pre-approval involves verified financials and provides a more authoritative commitment from the lender, often required before finalizing funding.
Understanding the difference helps business owners choose the right step based on their company’s stage and goals: factoring vs mca
Owners typically begin with loan pre-qualification and move to pre-approval as their financing needs firm up and documentation becomes available. This progression ties closely to building business fundability—improving creditworthiness and access to better financing terms.
The Impact of Business Fundability on Loan Eligibility and Financing Terms
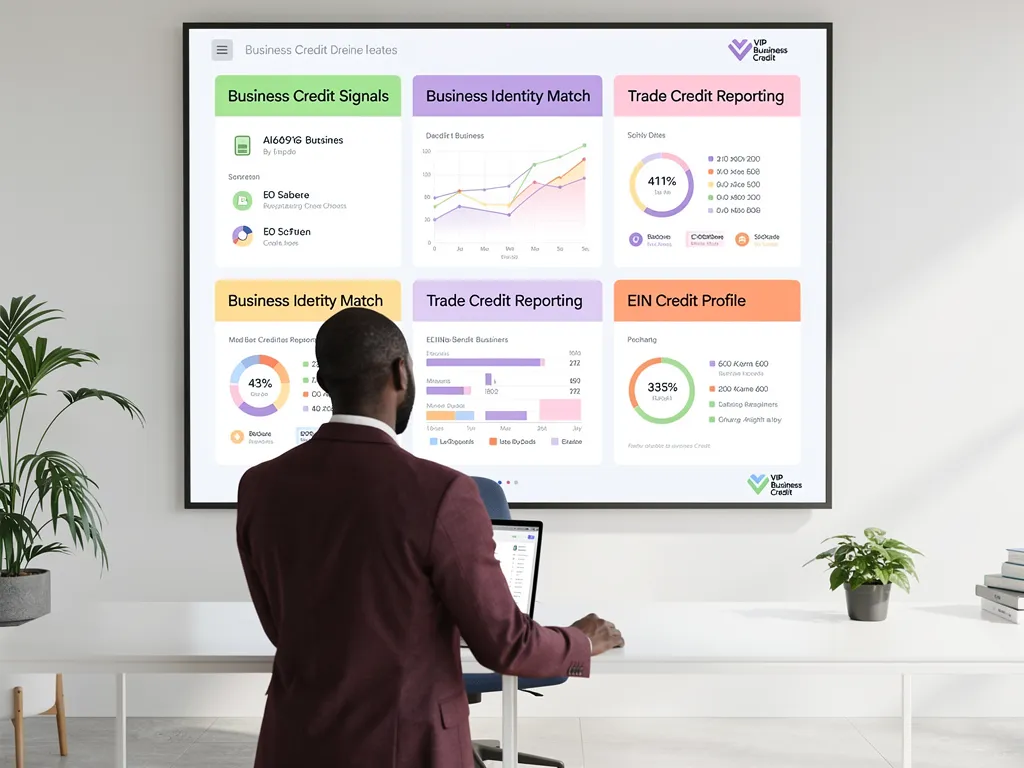
Business fundability defines how lenders and vendors assess risk and creditworthiness before extending financing. Businesses with solid fundability—marked by consistent identity data across registrations, timely vendor payments, and EIN-linked credit—appear more trustworthy and secure better loan terms including higher limits and lower interest rates.
Key components include:
- Consistent business contact and entity information across official records
- Established trade credit relationships reporting positive payment history to commercial credit bureaus
- Credit profiles linked to the business’s EIN rather than the owner’s personal SSN, separating personal risk from business liabilities
Why is Credit Structure Important for Fundability?
Credit established under the company’s EIN safeguards personal assets and allows businesses to qualify for higher-limit loans and revolving credit lines scaled to company performance. This structure is a cornerstone of healthy business fundability and improves loan approval odds.
Steps to Building Business Fundability
- Standardize business identity information across registrations, filings, and directories
- Establish and maintain trade credit relationships that report to business credit bureaus
- Transition to credit accounts tied to the EIN instead of the personal SSN
- Use improved fundability to qualify for better borrowing terms over time
VIP Business Credit supports this structured approach through continuous coaching and transparent pricing, fostering long-term credit building rather than one-off transactions.
Benefits of Loan Pre-Qualification Aligned with Business Fundability
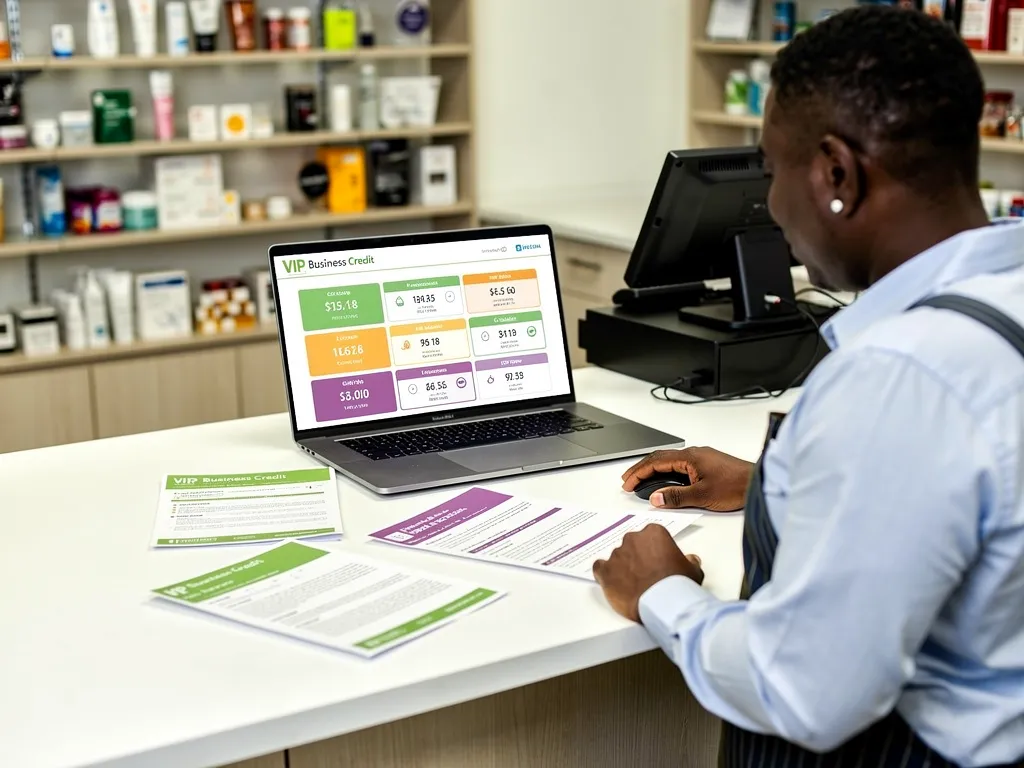
Loan pre-qualification gives owners a realistic borrowing range, enabling smart, budget-appropriate financing decisions. This step removes guesswork by providing actual estimated terms early, building confidence for formal applications.
Access to a diverse lender network broadens financing opportunities, as VIP Business Credit connects clients to over 1,000 institutions tailored to various business stages and risk profiles. This increases the likelihood of finding terms that align with a company’s business fundability.
Does Pre-Qualification Impact Business Credit Scores?
When conducted with soft credit check loans, pre-qualification does not harm a business’s credit profile, enabling owners to explore options safely.
What Follow-Up Steps Should Businesses Take After Pre-Qualification?
After understanding their estimated eligibility, owners should focus on enhancing business fundability through:
- Selecting loans and credit lines aligned with verified pre-qualification estimates
- Engaging in credit-building programs paired with expert coaching
- Addressing any identified eligibility gaps for stronger subsequent approvals
This methodology minimizes surprises during formal application underwriting and improves overall funding success.
VIP Business Credit’s Streamlined Pre-Qualification and Fundability Assessment Process
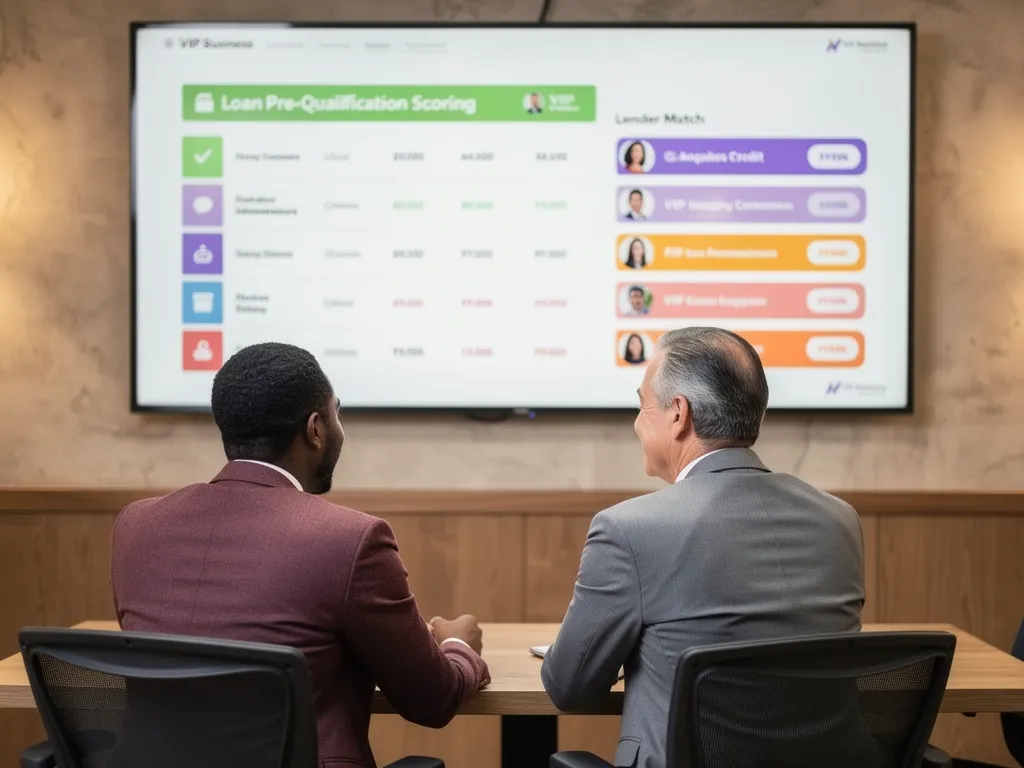
VIP Business Credit begins with a proprietary scoring system that assesses business fundability and loan pre-qualification simultaneously. This tool provides an accurate picture of how lenders currently view the business, uncovers eligibility gaps, and identifies suitable loan products based on the company’s EIN-linked credit data.
This approach differs from applying directly to banks, which often results in hard pulls and uncertain outcomes. VIP’s focus on soft credit check loans enables multiple explorations without risking personal credit scores, offering founders the flexibility to pursue the most advantageous funding sources.
How Does Lender Matching Work?
Following pre-qualification, the business’s profile is matched against a network of over 1,000 lenders, considering sector, stage, and risk attributes. This curated selection, guided by fundability metrics, presents owners with realistic, strategic options rather than generic offers.
- Current underwriting snapshot of the business
- Identification of specific eligibility weaknesses
- Custom-tailored list of lenders and loan products
- Roadmap connecting existing credit standing to future growth finance
The Importance of Building Credit on Your EIN Instead of Your SSN
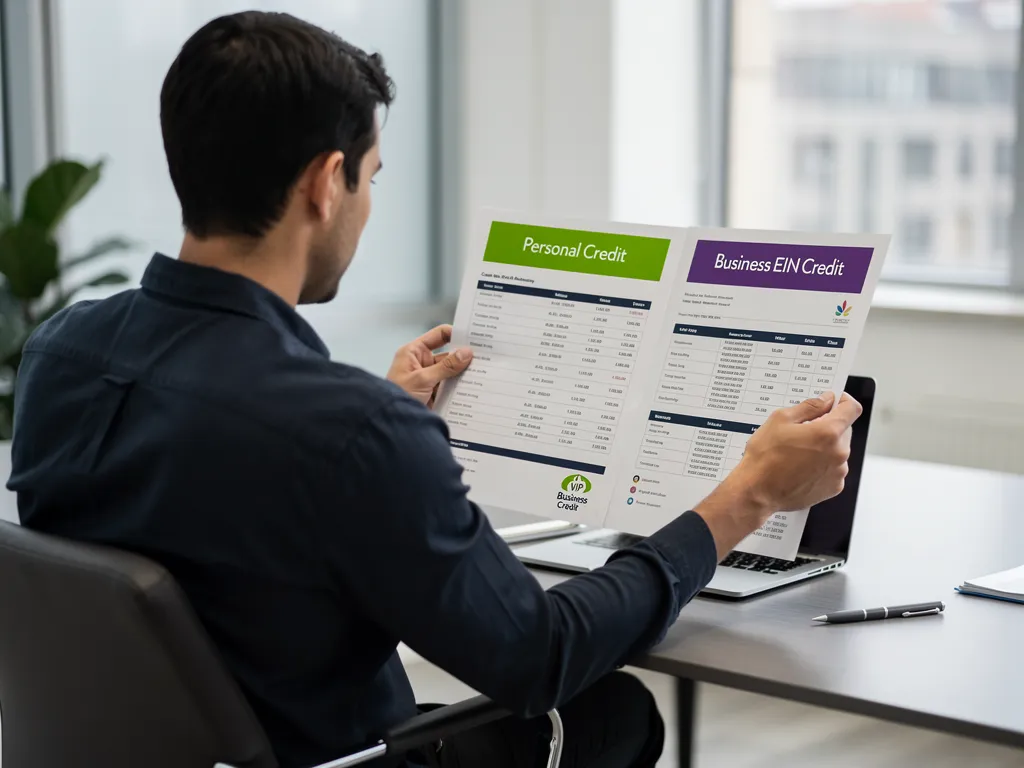
Using an EIN allows businesses to build a distinct credit profile separate from the owner’s personal Social Security Number, which is critical to establishing strong business fundability. This separation limits personal liability exposure and enables companies to secure higher-limit loans evaluated on business merits alone.
At VIP Business Credit’s Sterling, Virginia office, specialized advisory services help local entrepreneurs transition from personal guarantees to business-backed credit, streamlining access to capital that supports sustainable growth.
Clarifying Credit Impact: Pre-Qualification and Your Personal Score
Loan pre-qualification via soft credit check loans ensures zero impact on personal credit scores, an essential consideration when separating business and personal liabilities.
Determining an Appropriate Loan Amount
Qualification does not always equate to advisable borrowing levels. Businesses should consider cash flow and repayment capacity alongside eligibility. Building credit on the EIN provides a credit history detached from personal credit, enabling better-aligned funding decisions.
- Establishes a business-centric credit profile
- Mitigates personal financial risk
- Enables loan pre-qualification grounded in business performance metrics
Next Steps to Secure Business Financing with Confidence
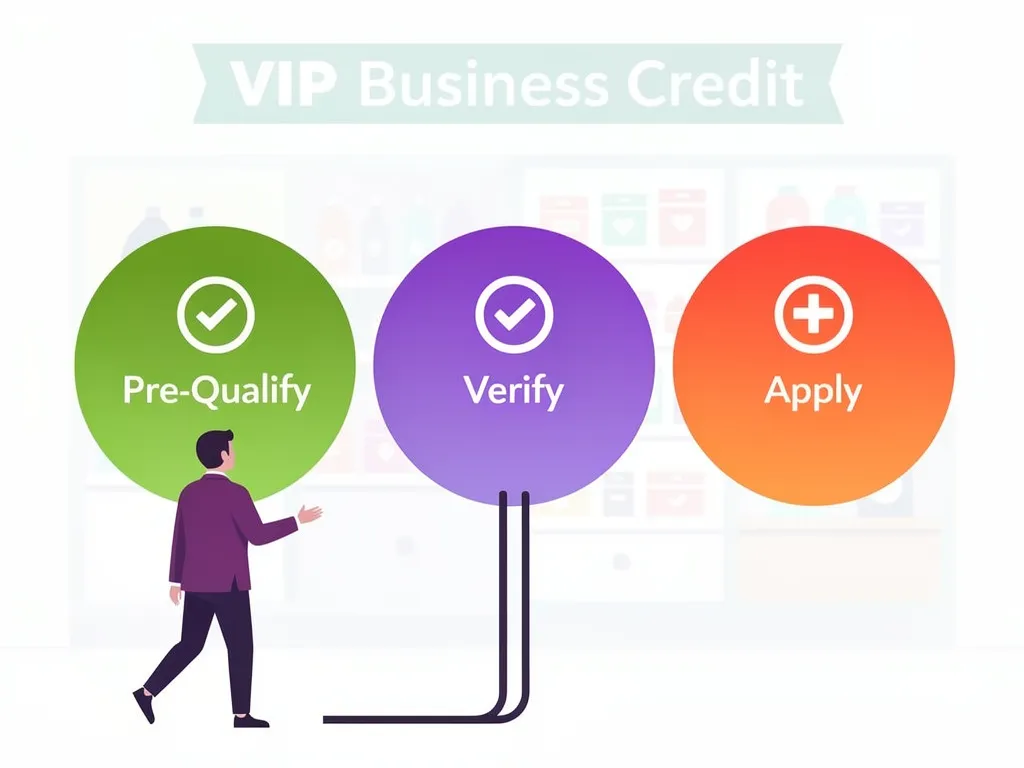
To successfully access capital, business owners should follow a structured approach:
- Begin with loan pre-qualification using soft credit check loans to set a realistic borrowing budget
- Verify financial information early to strengthen subsequent applications
- Develop business fundability by standardizing identity data and building trade credit
- Apply formally once documentation aligns with lender expectations
VIP Business Credit’s personable advisory team, based in Sterling, VA, emphasizes a concierge-style experience that affords each client detailed attention and tailored guidance through the funding journey.
Frequently Asked Questions About Business Fundability, Loan Pre-Qualification, and Soft Credit Check Loans
Does Loan Pre-Qualification Affect My Credit Score?
No. Loan pre-qualification with VIP Business Credit uses soft credit check loans that have zero impact on personal credit.
How Is Loan Pre-Qualification Different From Pre-Approval?
Pre-qualification offers an early, informal estimate based on unverified data, while pre-approval is a firm lender commitment following verification of financial documents and assessment of business fundability.
What Can Loan Pre-Qualification Reveal About Financing Options?
It identifies lenders a business currently qualifies for, those requiring further preparation, and steps that can improve eligibility, backed by access to a broad lending network.
Conclusion: Elevate Your Business Financing with Strategic Fundability and Pre-Qualification
Optimizing your business fundability and leveraging loan pre-qualification supported by soft credit check loans eliminates uncertainty from your financing process. This informed approach empowers business owners to confidently navigate lender options, understand realistic credit capacity, and strategically pursue funding aligned with their company’s profile. The clarity and expertise provided transform capital acquisition from overwhelming to manageable, helping your business secure the financing it truly deserves.
About The Author
Lee Johnson is a Master Certified Professional Coach and the Founder of VIPBizFunds. With extensive expertise in business credit structuring, alternative commercial lending, and financial strategy, Lee empowers entrepreneurs and small business owners to access the capital they need to scale sustainably.
Contact Us
- 📞 Phone: (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule A Business Financial Health Strategy Call
- 🌐 Website: https://vipbizfunds.com
- 🎯 FREE Business Success Scan: FREE Business Success Scan
(Serving Sterling, VA and surrounding areas)


