Understanding Business Credit Terms
Understanding Business Credit Terms
Business credit terminology covers terms like Fundability Score, Paydex, trade credit, and EIN-based credit profiles, each describing how lenders and bureaus evaluate a company separately from its owner. VIP Business Credit's Business Fundability Scan identifies gaps in these metrics within 2–5 minutes, giving founders a clear roadmap for building lender-ready credit.
Key Takeaways
- Business credit reflects how well your company manages money and builds lender trust.
- VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders nationwide.
- Understanding business credit terminology helps Northern Virginia and Greater Washington, DC entrepreneurs secure funding.
Why Do Credit Terms Confuse So Many Owners?
Unfamiliar vocabulary creates most of the confusion, not a lack of intelligence or effort. Many founders never learn the basic credit terms that lenders use every day, simply because no one taught them. The Nav American Dream Gap Survey (2015) found that 45% of small business owners surveyed did not even know their company had a business credit score. That single gap explains why everything built on top of it, scoring models, repayment language, risk categories, feels like a foreign language.
Business credit works much like personal credit: it signals whether a company can be trusted based on how it manages money. Lenders read that signal through dense credit definitions and underwriting language that rarely gets explained in plain terms. Owners juggling payroll, inventory, and customers have little time left to decode financial vocabulary written for bankers, not business builders.
What makes business credit vocabulary harder than personal credit vocabulary?
Personal credit involves one scoring system most consumers eventually learn through repetition. Business credit involves multiple bureaus, multiple scoring models, and financial jargon that shifts depending on the lender and the loan type. A term that means one thing at a bank can carry a different weight with an alternative lender.
VIP Business Credit works directly with entrepreneurs across Northern Virginia. The Greater Washington, DC region to translate this language into EIN-based credit building, keeping personal Social Security numbers out of the equation. That guidance matters because the firm connects clients to more than 1,000 national. Local lenders, each with its own underwriting style and terminology:
- Traditional banks favor conservative, collateral-driven language.
- Alternative finance providers use faster, revenue-based criteria.
- Specialized programs apply industry-specific risk definitions.
Clarity on these terms turns a confusing marketplace into a navigable one.
What Core Credit Definitions Should You Know First?
Four concepts anchor every conversation about building business credit: business credit itself, credit terms, credit definitions, and the financial jargon lenders use to judge risk. Misreading even one of these can cost a founder real money, leading to the wrong loan application or a missed qualification step. Getting the foundation right first prevents that loss later.
Business credit, in simple terms, reflects how well a company manages its money. That single idea underpins every other definition that follows, from repayment history to credit limits. Once that foundation is clear, the more technical terms stop feeling like a foreign language.
What does EIN-based credit mean?
EIN-based credit ties a company's borrowing history to its federal Employer Identification Number instead of the owner's Social Security number. VIP Business Credit's core focus centers on guiding clients toward exactly this kind of funding. Building credit this way keeps personal and business liability separate. A downturn in the company's finances does not automatically damage the owner's personal score.
Why does location matter for learning these terms?
Credit education delivered from a specific, accountable office carries more weight than advice from an anonymous website. VIP Business Credit operates out of Sterling, Virginia, grounding every definition in a real place clients can point to. That specificity matters when founders are trusting a firm with decisions that affect both personal and corporate finances.
A few starting definitions worth memorizing:
- Business credit: a reflection of how reliably a company manages its financial obligations.
- EIN-based credit: credit history attached to the business's own identification number, not the owner's SSN.
- Credit terms: the specific repayment conditions, rates, and limits attached to a loan or credit line.
VIP Business Credit's three-person team delivers these explanations with a hands-on, advisory style rather than a scripted call center approach. That smaller structure allows each definition to be explained patiently, with room for follow-up questions before a founder commits to any funding product.
How Do Business Credit Scores Actually Work?
Business credit scores measure how reliably a company repays what it owes. These numbers shape two concrete outcomes: whether a lender approves a loan, and what interest rate gets offered. A low score doesn't just slow down approval; it narrows the pool of lenders willing to extend credit at all. The ones who do say yes often charge more for the risk.
Unlike a single personal credit score, business scores come from multiple bureaus, and each one runs its own math. Each major bureau applies a different scoring model and a different range. A company can look strong to one lender and risky to another, simply based on which bureau gets checked. That inconsistency is part of what makes financial jargon around business credit so confusing for founders.
Why Does My Business Credit Score Change Depending on Who Checks It?
Different bureaus pull from different data sources and weigh payment history differently. A business might carry a strong score with one bureau while showing a thinner, less favorable file with another. Lenders rarely disclose which bureau they pull from in advance, which is why monitoring more than one score matters.
What Actually Moves a Business Credit Score Up?
Timely payments and responsible credit use are the two levers that matter most. Paying vendors and lenders on schedule, month after month, builds a payment history bureaus reward. Responsible use, meaning borrowed amounts that stay well below available limits, signals low risk and increases funding opportunities over time.
This is where clear credit definitions and ongoing monitoring earn their place in a growth strategy. Tools designed to track accounts and data across the bureaus lenders actually use translate raw score movements into plain language founders can act on, rather than numbers that sit unexplained on a report.
What Does EIN-Based Credit Really Mean?
EIN-based credit shifts the spotlight away from a founder's Social Security number. Onto the company's own federal tax ID, the EIN. Lenders evaluate the business as its own financial entity, not as an extension of the owner's personal history. This distinction sits at the center of how credit terms actually work for a growing company. It changes what underwriters look at when deciding whether to approve a loan or credit line.
Why does this distinction matter so much? Because the practical payoff is asset protection. A business that builds its own credit profile creates a buffer between company debt and personal liability. A slow season or a missed vendor payment doesn't automatically threaten an owner's home, savings, or personal credit score.
Why Do Small Business Owners Need to Understand Credit Definitions?
Understanding credit definitions stops confusing financial jargon from turning into costly mistakes. Knowing how business credit scores work, and managing them well, becomes essential the moment a company needs funding to expand, hire, or cover a cash-flow gap. Owners who skip this step often discover underwriting requirements only after a denial letter arrives.
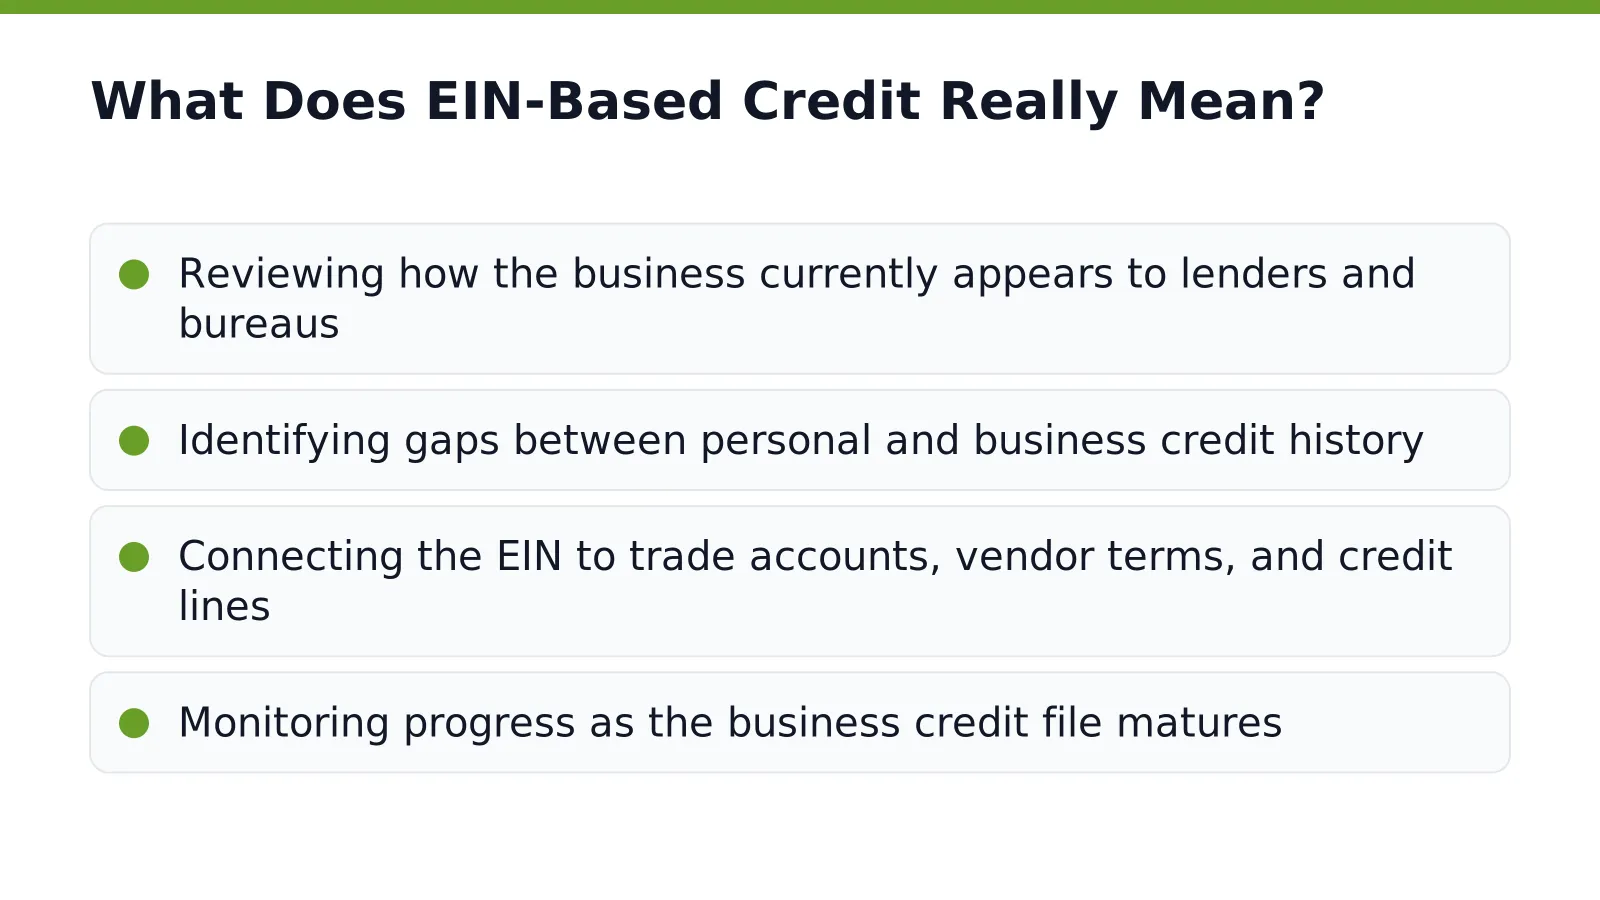
Building that EIN-based foundation takes guidance, not guesswork. VIP Business Credit helps entrepreneurs across Northern Virginia. The Greater Washington, DC region establish exactly this kind of credit profile from the ground up. Support typically includes:
- Reviewing how the business currently appears to lenders and bureaus
- Identifying gaps between personal and business credit history
- Connecting the EIN to trade accounts, vendor terms, and credit lines
- Monitoring progress as the business credit file matures
Combining broad lender access with structured guidance gives owners a clearer path toward separating their personal finances from the company's. That separation isn't just about financial jargon or paperwork; it's the mechanism that lets a business grow on its own merit. Its owner keeps personal assets out of the equation entirely.
Which Lender Terms Matter When Comparing Options?
Comparing lending options starts with a handful of recurring credit terms that determine whether a business qualifies and what the financing actually costs. Skipping past these credit definitions risks signing agreements that drain cash or limit future borrowing. Lenders often wrap similar offers in financial jargon that sounds alike but carries very different obligations underneath.
A broad network of lenders matters because no single bank's underwriting model fits every business. National banks, alternative finance providers, and specialized lending programs each serve different company stages and risk profiles. Founders comparing offers should ask which network segment a given lender actually serves before assuming approval odds.
Several financing structures carry their own vocabulary worth learning before signing anything:
What Do Equipment and Fleet Credit Lines Actually Cover?
Equipment credit lines let a business put machinery or tools to work immediately, rather than waiting on cash reserves to build. The account activity builds credit history, and the payments typically qualify as deductible business expenses. Fleet credit lines work the same way but apply to vehicles: financing covers multiple trucks, vans, or cars under one arrangement while building credit and preserving tax deductions tied to the fleet.
Why Does Cash Flow Management Count as a Lending Term?
Cash flow management describes the strategies that keep working capital available before a shortage hits, not after. A business relying on reactive borrowing often pays more for speed. Lenders view consistent cash flow planning as a sign of lower risk, which strengthens negotiating position on rates and terms.
How Can Credit Monitoring Tools Decode Jargon?
Specialized monitoring platforms turn confusing credit terms into plain, usable guidance for business owners. A well-built scoring dashboard strips away dense financial jargon. Shows a founder exactly where a company stands with lenders, not just what a report says. Instead of guessing what a term like "trade line" or "utilization ratio" actually means for approval odds, owners get a translated view tied directly to their own numbers.
Tools such as the Capital-Ready Score, Funding Explorer, Funding Manager, and Bureau Insights exist for this exact purpose. Each one is designed to show how underwriters actually view a business and where its eligibility gaps sit. Rather than leaving owners to decipher credit definitions on their own, these tools surface the specific factors pulling a score up or down.
Why does this matter for a growing business?
This kind of technology infrastructure supports a clear, step-by-step path forward. As a credit profile strengthens, owners become eligible for better terms, higher limits, and lower rates. The platform shows which milestone unlocks which outcome.
Does monitoring tell owners what to do next, or just what their score is?
Monitoring alone only reports a number; a pre-qualification workflow goes further. It helps business owners understand which funding programs they already qualify for today, which ones require more preparation, and which specific actions expand their options over time.
That distinction matters because jargon without direction leaves owners stuck. A dashboard that simply displays a score, without context, still forces an owner to interpret:
- Which factors are driving the score up or down
- Which lender programs match the current profile
- What specific next step moves the needle
Decoding jargon, in practice, means connecting every term to a concrete next action, not just a definition.
What Role Do Advisors Play In Translating Jargon?
Local Business Credit Advisors turn confusing credit terms into plain, actionable guidance tailored to each business. Rather than handing over a generic glossary, these advisors walk entrepreneurs through credit definitions in the context of their actual financing goals. A founder applying for a line of credit gets a different explanation than a retailer trying to qualify for vendor terms. The advisor matches the lesson to the lender and the product in play.
Concierge-level support means the conversation doesn't end after one meeting. Advisors stay engaged as a long-term partner, not a broker who explains a term once and vanishes. Pricing stays transparent throughout the relationship. Clients never face surprise fees buried in financial jargon they didn't fully understand upfront.
Why does jargon translation matter for funding approval?
Lenders judge businesses partly on how well owners understand underwriting criteria. When a founder can speak confidently about trade credit reporting or consistent business identity data, that confidence signals lower risk. Advisors close this gap by teaching the "why" behind each term, not just the definition.
What does an advisor cover beyond loan paperwork?
Advisors extend well past arranging financing itself. Their coaching includes:
- Explaining how business loans and lines of credit differ in underwriting
- Walking through the full credit-building program step by step
- Showing owners how consistent business data affects lender perception
- Teaching healthy credit usage habits that protect long-term funding access
This broader education helps owners see credit management as an ongoing discipline. Strengthening those credibility signals, rather than treating financing as a one-time transaction, positions the business for stronger terms down the road.
How Do You Put These Terms Into Action?
Applying business credit concepts starts with turning definitions into daily habits, not memorizing a glossary. Entrepreneurs who understand financial jargon can convert each term into a specific move: pay invoices on schedule, check reports regularly, and keep business accounts separate from personal ones. Skipping these habits costs businesses funding opportunities. Leaves owners personally exposed for debts that should sit under the company's own identity.
Consistent attention to credit standing separates businesses that qualify for stronger financing from those that stall. Monitoring and improving credit scores through timely payments. Responsible credit use positions a company for long-term growth and expands its funding opportunities over time. Owners who review their standing on a regular basis catch errors before those errors derail an application.
What does applying credit definitions look like day to day?
Turning credit definitions into practice means building small, repeatable routines around the company's financial identity.
- Pay vendor and lender accounts ahead of due dates
- Keep legal business information consistent across every filing and application
- Separate personal and business banking, credit cards, and lines of credit
- Review reports from the bureaus lenders rely on before applying for new funding
Each habit reinforces the next, building a profile lenders can trust.
Where can business owners get hands-on help applying these terms?
Support for this work is rooted in Northern Virginia, with active service across Loudoun County and the surrounding region. Clients beyond that area connect digitally, since the firm works with lenders nationwide regardless of location. Owners seeking in-person guidance can visit the office at 21000 Southbank St Ste 106-380, Sterling VA 20165, for local advisory support.
Combining broad lender access, purpose-built software, and guided execution ultimately helps owners protect personal assets while unlocking sustainable growth once these credit terms move from theory into daily practice.
FAQ
Why does business credit terminology confuse so many business owners?
Unfamiliar vocabulary, not a lack of intelligence, causes most confusion. Many founders never learn the basic credit terms lenders use daily, simply because no one taught them.
What makes business credit vocabulary harder to understand than personal credit terms?
Personal credit involves one scoring system most people learn through repetition. Business credit involves multiple bureaus and scoring models, with jargon shifting depending on the lender and loan type.
What does EIN-based credit mean for entrepreneurs?
EIN-based credit ties a company's borrowing history to its EIN instead of the owner's Social Security number. VIP Business Credit helps Northern Virginia and DC-area entrepreneurs build credit this way.
Conclusion
In closing, mastering business credit terminology transforms how you communicate with lenders and navigate the funding landscape. These terms form the foundation of every conversation about capital, risk assessment, and borrowing capacity. By understanding what lenders mean when they reference your Fundability Score, trade lines, or personal guarantee, you move from confusion to confidence. You're no longer a passive applicant, you become an informed business owner who speaks the language of credit. Positions your company for sustainable growth and stronger financial partnerships.


