The Fundability Benefits Every Business Owner Should Know for Business Financial Health and Funding Readiness
The Fundability Benefits Every Business Owner Should Know for Business Financial Health and Funding Readiness
By VIP Business Credit Editorial Team · Updated *2026-08-05*
Fundability Score assessments identify gaps across over 20 key fundability checkpoints—among the 125 total factors lenders evaluate—that determine financing eligibility, strengthening EIN-based business credit and boosting your company’s business financial health and funding readiness. VIP Business Credit connects qualifying entrepreneurs to more than 1,000 national and local lenders, improving access to superior rates, higher limits, and stronger vendor and leasing opportunities by focusing on precise lender approval metrics.
A detailed VIP Business Credit Fundability Scan reveals your business’s commercial borrowing power through hundreds of lender criteria. This EIN-based credit evaluation offers a roadmap for improving fundability benefits, aligning your corporate compliance checklist to meet real-world standards held by commercial lenders and underwriting teams.
Key Takeaways on Business Financial Health, Funding Readiness, and Fundability Benefits
- A comprehensive fundability score builds strong EIN-based business credit without relying on personal credit history.
- VIP Business Credit’s Fundability service widens access to over 1,000 national and local lenders, enhancing commercial borrowing power.
- Strong business credit improves fundability benefits by securing lower interest rates and expanded credit limits through better lender approval metrics.
- Evaluating fundability optimizes your company’s funding readiness, enhancing business financial health and expanding growth opportunities.
Understanding the 20+ Fundability Checkpoints Lenders Evaluate for Business Financial Health
Lenders utilize a complex set of metrics, commonly known as lender approval metrics, consisting of approximately 125 factors that influence a company's ability to access funding. Among these, more than 20 critical fundability checkpoints drive the core evaluation of your business’s financial health and funding readiness. Key categories include:
- Legal Business Structure and Registration – Compliance with state and federal entity requirements, proper registration, and naming conventions free of high-risk language.
- Financial Documentation Accuracy – Consistent, transparent, and complete income statements, balance sheets, and cash flow reports.
- EIN-Based Credit History – Credit scores and trade line activity tied specifically to the business EIN rather than personal social security numbers.
- DUNS Number Status – Verification of the company’s DUNS identifier, important for many commercial lenders’ risk assessment.
- Payment History with Vendors – Timely payments reflected in credit bureau reports to build documented creditworthiness.
- Accounts Receivable and Payable Management – Demonstrated cash flow through strategically negotiated payment terms like Net-30, Net-60, or Net-90.
- Business Tenure and Industry Classification – Time in business and industry risk profiles factored into underwriting.
- Corporate Compliance Checklist – Up-to-date licenses, permits, and adherence to regulatory standards.
- Revenue Consistency and Growth Trends – Evidence of stable and increasing business income.
- Bank Account Activity – Regular business account transactions supporting operational viability.
- Existing Debt Levels – Manageable liabilities relative to credit and cash flow.
- Business Insurance Coverage – Proper insurance signaling risk management.
- Collateral and Security Interests – Assets pledged to secure credit when applicable.
- Owner’s Equity and Financial Investment – Reinvestment and capital commitment signals financial strength.
- Trade References – Established vendor or supplier credit relationships.
- Credit Utilization Rates – Balanced use of existing credit lines demonstrating financial responsibility.
- Legal Proceedings and Judgments – Absence or resolution of lawsuits that affect credit risk.
- Tax Compliance – Prompt and accurate tax filings avoiding legal complications.
- Business Plan and Strategic Positioning – Clear direction and market positioning evaluated for growth potential.
- Cash Flow Planning and Management – Proactive approaches to working capital ensuring operational liquidity.
Each checkpoint contributes to a composite picture of business financial health and funding readiness, crucial for unlocking fundability benefits and improving your commercial borrowing power.
Why Funding Readiness Based on Fundability Benefits Matters for Your Business Financial Health
Achieving true funding readiness means your business is positioned to secure capital exactly when growth or opportunity demands it, rather than months later due to incomplete or inadequate preparation. This readiness is the foundation of effective commercial borrowing power. Strong funding readiness reflects a business that meets underwriting standards across the corporate compliance checklist and lender approval metrics, leading to faster approvals, higher credit limits, and lower interest rates.
Building strong EIN-based business credit distinguishes the company from personal credit files, protecting personal assets while establishing a dedicated financial identity with lenders. This separation is a fundamental fundability benefit that underpins sustainable business financial health.
Consequences of Insufficient Funding Readiness
Lacking a lender-ready profile often results in slower loan approvals, lower credit offers, and higher interest rates. Businesses may face unexplained rejections, losing critical time and financial opportunities. These setbacks highlight why fundability and funding readiness are not luxuries but necessities in commercial borrowing.
Expanding Access: Why the Number of Lenders Matters for Fundability Benefits
Access to a broad network of lenders grants greater options aligned to your business’s stage and sector. VIP Business Credit’s connections to more than 1,000 national and local lenders offer diverse avenues for funding, including traditional banks, alternative finance providers, and specialized credit programs. This range maximizes your commercial borrowing power and is a key fundability benefit enhancing your business financial health.
How Strong Business Credit Enhances Financial Health through Fundability Benefits
Strong business credit is a powerful trust signal to lenders and vendors alike. It separates business finances from personal assets, increasing credibility and enabling favorable financing terms. Without it, businesses risk higher borrowing costs and stunted growth opportunities. A solid credit profile is central to sustaining fundability benefits and is a strategic asset in long-term business financial health.
Such credibility expands your capacity to negotiate vendor agreements, office leases, and other operational necessities at improved terms, reflecting your business’s financial discipline and reputation.
Fundability Benefits Impacting Cash Flow and Credit Growth
Effective management of working capital is vital; cash flow gaps, not profits, cripple most small businesses. VIP Business Credit’s cash flow strategies integrate fundability principles to assure liquidity before shortfalls occur. Over time, dedicated credit-building elevates credit limits and vendor relationships, enhancing fundability benefits that support steady cash flow and lower borrowing costs.
- Lower borrowing costs via increased lender trust and stronger profiles.
- Expanded vendor payment terms as reliability is demonstrated.
- Steadier cash flow through strategic working-capital planning aligned with fundability checkpoints.
These outcomes translate directly to improved commercial borrowing power and sustained business financial health.
Why EIN-Based Credit Is Critical for Long-Term Business Financial Health and Fundability Benefits
Establishing EIN-based business credit creates a separate financial identity for your business distinct from your personal credit profile, a cornerstone for managing risk and unlocking strong fundability benefits. Building this credit profile enables greater Access to higher loan amounts and better vendor terms without personal guarantees, safeguarding personal assets and strengthening your company’s commercial borrowing power.
This strategic separation supports growing businesses during critical scaling phases and shifts the basis of lender approval metrics toward the business entity rather than individual owners.
What Specific Fundability Factors Does an EIN-Based Credit Assessment Check?
An EIN-based fundability assessment reviews multiple elements that align closely with lender approval metrics:
- Business structure - corporate formation, registrations, and compliance with incorporation standards.
- Credit history - credit activity tied to the EIN including trade lines and public records.
- Financial documentation - verification of revenue streams and fiscal stability through consistent reporting.
Aligned improvement across these areas directly elevates your business’s funding readiness.
Long-Term Value of EIN-Based Credit and Fundability Benefits
Relying solely on personal credit limits funding scalability. EIN-based credit removes these constraints, providing structured access to capital tailored to the company’s actual financial health. This progression underscores enhanced fundability benefits and improves lender approval outcomes over time.
Introducing the Capital-Ready Score: A Tool to Improve Fundability Benefits and Business Financial Health
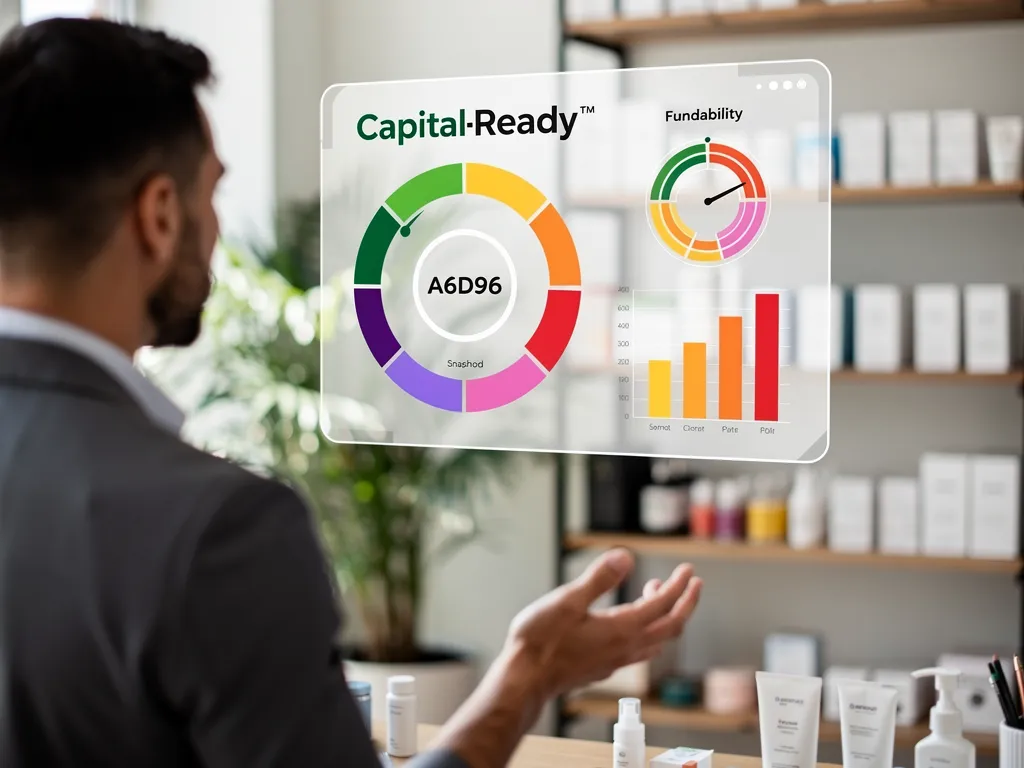
The Capital-Ready Score is a proprietary scoring solution designed to give businesses a clear metric of their commercial borrowing power and overall fundability. This tool condenses complex underwriting criteria into comprehensive lender approval metrics that plot your current standing and identify credit gaps. VIP Business Credit’s scan not only quantifies risk but provides an actionable roadmap to enhance your company’s financial health and funding readiness.
What Does a Fundability Scan Check Beyond Credit Score?
Alongside reviewing credit profiles, the scan verifies your business’s DUNS number status—a key identifier used by commercial lenders. It identifies gaps in documentation, reporting, and compliance, presenting specific, prioritized steps for sustaining fundability benefits and boosting commercial borrowing power.
Distinguishing Fundability from Traditional Credit Scores
While traditional credit scores focus narrowly on credit repayment history, fundability encompasses a broad set of lender approval metrics including business structure integrity, corporate compliance checklist items, and financial reporting consistency. This holistic approach equips business owners with a clearer understanding of their true funding readiness.
Typical outputs of the Capital-Ready Score involve:
- A lender-facing numerical risk score
- A detailed list of targeted credit and documentation gaps
- Prioritized improvement plans based on business-specific findings
- Validation and status of essential identifiers such as DUNS number
Through continuously updating these data points, businesses enhance their fundability benefits and improve overall financial health.
How Cash Flow Management Integrates with Fundability Benefits and Business Financial Health
Effective cash flow management is a practical means of demonstrating discipline and trustworthiness to lenders. Reporting on-time payments to major credit bureaus through vendor relationships converts routine payables into documented credit history, significantly strengthening fundability benefits.
Many business owners overlook these nuances, focusing only on obvious financial statements rather than recognizing the power of a well-managed corporate compliance checklist that includes extensive vendor and payment reporting.
Importance of Payment Terms for Business Financial Health and Fundability
Negotiated payment terms like Net-30, Net-60, and Net-90 align outflows with income cycles, effectively managing working capital and enhancing lender perceptions of financial stability. This strategic management is foundational in building credible credit files that lenders value.
Account Verification’s Role in Maintaining Strong Fundability Benefits
Ensuring every reporting account reaches Dun & Bradstreet accurately is crucial. A non-reporting account generates no credit-building value and permitting errors to persist undermines months of solid payment history. Continuous account monitoring and verification safeguard the integrity of your business credit profile, reinforcing funding readiness and solidifying business financial health.
Ongoing account management steps include:
- Validating correct reporting each cycle
- Tracking payment schedules rigorously
- Monitoring monthly enhancements in credit profiles
Cultivating these routines delivers one of the strongest fundability benefits: a credit profile grounded in performance and verifiability rather than promises alone.
Actionable Steps to Improve a Low Fundability Score and Build Business Financial Health
Improving your fundability score starts at the foundation of your business—legal structure, registration details, and financial documentation—rather than quick credit applications. Addressing these foundational factors maximizes your commercial borrowing power and accelerates funding readiness.
Owners should focus first on corrective actions within their control, such as:
- Removing high-risk industry language from business names
- Ensuring all business registration information is accurate and consistent
- Rectifying discrepancies in addresses, phone numbers, and entity names
- Verifying completeness and accuracy of financial documents and tax filings
Fundability challenges like limited business tenure or fixed industry classification require strategic planning rather than immediate fixes. Recognizing avoidable versus fixed factors prevents wasted effort and encourages sustainable improvement focusing on your corporate compliance checklist and lender approval metrics.
Integrating Cash Flow Planning to Sustain Fundability Benefits
Sound cash flow planning acts as a proactive signal to lenders demonstrating operational control and risk mitigation. VIP Business Credit’s strategies emphasize advancing working capital readiness ahead of funding needs, preserving readiness and expanding business financial health.
By approaching fundability improvement as a sequence of deliberate actions—strengthening basics, stabilizing cash flow, and expanding credit profiles—owners achieve lasting fundability benefits that align with long-term growth.
Getting Started with Your Fundability Assessment to Enhance Business Financial Health
Your fundability assessment begins with a personal consultation, not a credit pull. Connect with a Business Credit Advisor at VIP Business Credit’s Sterling, Virginia office, located at 21000 Southbank St Ste 106-380, Sterling, VA 20165. This initial meeting focuses on comparing your business’s current funding readiness against lender approval metrics and corporate compliance checklists for immediate insight.
What to Expect During the Initial Fundability Review
Your advisor will evaluate how underwriters view your profile, identifying fundability benefits already present and prioritizing gaps that need addressing. This hands-on approach provides actionable recommendations tailored directly to your unique business situation instead of generic advice.
The Role of Lender Access in Fundability Benefits at This Step
With access to a network exceeding 1,000 national and local lenders, VIP Business Credit offers options beyond conventional banking. This connectivity ensures that financing recommendations align with your company's industry, developmental stage, and inherent risk profile, boosting your commercial borrowing power and increasing funding readiness.
Your fundability assessment typically includes:
- Review of your current business financial health with a focus on EIN-based credit and documentation
- Identification of gaps compared to evolving lender requirements and approval metrics
- Customized shortlist of financing options suited to your business’s parameters
- Detailed, step-by-step plan for improving corporate compliance and other fundability checkpoints prior to application
This process transforms abstract concepts of fundability into concrete, manageable actions that strengthen your business’s financial health and readiness to secure funding.
Understanding and managing your fundability score reshapes your approach to business financing. Addressing specific credit and compliance gaps through targeted, strategic actions builds confidence, enhances commercial borrowing power, and unlocks sustainable growth.
FAQ on Fundability Benefits, Business Financial Health, and Funding Readiness
What exactly does a fundability score assessment evaluate?
It evaluates more than 125 factors, emphasizing over 20 core fundability checkpoints, including your business structure, financial documentation, and EIN-based credit history separate from personal credit files, all essential to solid business financial health.
How does a fundability assessment improve financing access?
The assessment identifies precise credit and compliance gaps limiting your business, then creates a strategic roadmap for closing them. Coupled with VIP Business Credit’s extensive lender network, this roadmap enhances your financing options, securing better rates, higher limits, and matched solutions for your business’s stage and industry.
Why is building EIN-based business credit vital for fundability benefits?
Because business credit scores use scoring models distinct from personal credit scores, a strong personal credit does not equate to a strong business profile. Separate EIN-based tracking is essential for developing authentic commercial borrowing power and sustaining long-term business financial health.
Facts About VIP Business Credit and Fundability Benefits
- VIP Business Credit is located in Sterling, VA, US.
- VIP Business Credit helps entrepreneurs in Northern Virginia and the Greater Washington, DC region build EIN-based business credit.
- VIP Business Credit connects clients to over 1,000 national and local lenders to improve funding readiness.
About The Author
Lee Johnson is the Co-Founder and CEO of VIP Business Credit and a seasoned expert in business funding, real estate, and generational wealth building with over 25 years of experience. He holds a Bachelor of Science from Fairleigh Dickinson University, a Master of Business Administration from the University of Phoenix, and is a Certified Professional Coach with more than 500 coaching hours. Since 2005, Lee has built a real estate portfolio spanning multifamily, private lending, and residential rehab — now exceeding 1,700 units valued at approximately $254 million across multiple U.S. markets. Guided by an investor-first philosophy, he shares only personally vetted opportunities, making him a trusted advisor for entrepreneurs looking to use business credit, alternative investments, and real estate to build compounding, generational wealth.
For personalized guidance to enhance your business financial health and funding readiness through expert fundability assessments, connect with a Business Credit Advisor serving Sterling, VA, Northern Virginia, and Greater Washington, DC:
Contact Information
📞 Phone: +1 (571) 248-3863
✉️ Email: [email protected]
📅 Consultation: Book a consultation
🌐 Website: vipbizfunds.com
🎯 FREE Business Funding Pre-Qualification Scan: Start your scan


