The Business Credit Advisor's Guide to Personalized Funding
The Business Credit Advisor's Guide to Personalized Funding
By *VIP Business Credit* Editorial Team · Updated 2026-08-31
Personalized business credit advisor funding offers entrepreneurs a uniquely tailored growth-capital strategy centered on the company's EIN, guided by certified professionals who specialize in guiding clients through the complex lending ecosystem. VIP Business Credit begins with a comprehensive business credit readiness review, pinpointing credit gaps and assessing fundability scores through an innovative fundability consulting roadmap and a structured business credit builder program. This approach ensures owners are matched with non-predatory lenders best suited to their stage and sector, while optimizing capital stacks and constructing multi-tier corporate credit profiles, all crafted to protect personal credit and unlock higher-limit financing options.
Key Takeaways
- VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders across Northern Virginia and DC, facilitated by commercial credit advisory services.
- Using proprietary fundability consulting tools, businesses gain clear insights into lender requirements before submitting funding applications, reducing costly mistakes.
- Approximately 80% of startups fail due to cash flow problems; strategic credit building and fundability consulting provide a preventative framework.
- A dedicated three-person team offers personalized business funding consulting, credit coaching, and multi-tier corporate credit construction to propel financial growth.
Why Does Your Business Need Its Own Credit Identity?
Establishing a separate business credit identity tied to the company's EIN, distinct from the owner's Social Security number, is essential for both legal protection and financial growth. This is how owners separate personal and business liability: any missed payments or lawsuits affect only the business, not personal mortgages or auto loans. VIP Business Credit aids entrepreneurs throughout Northern Virginia and the Greater Washington, DC region in building this foundational commercial credit profile from the ground up as part of their comprehensive commercial credit advisory services.
The stakes are higher than liability alone. Cash flow shortfalls cause nearly 80% of startup failures. Without a distinct credit identity, businesses lack access to the crucial working capital needed to survive and grow. An absence of credit history renders a company invisible to lenders — not necessarily risky, just unknown — which prematurely closes doors before owners can even present their case for funding. Building strong business credit and regularly evaluating your business's fundability score are pivotal steps for establishing credibility and unlocking access to vital capital.
The Core Role of a Business Credit Advisor
A certified business credit advisor is fundamental in auditing and enhancing a company's fundability profile. This includes:
- Auditing corporate fundability profiles with precision, analyzing all credit activities, trade lines, and public financial records. Advisors use proprietary tools to identify gaps and red flags that impair funding potential.
- Eliminating red flags in public filings by correcting inconsistencies, resolving liens, judgments, or errors on credit bureau reports. For example, an advisor might help dispute an outdated judgment or update inaccurate company address records that affect credit credibility.
- Aligning business entity structures such as LLC, C-Corp, or S-Corp with commercial lender underwriting guidelines to maximize lending eligibility. Proper structuring avoids common pitfalls that lead to application denials.
By methodically addressing these areas, advisors prepare businesses to present a strong, credit-ready profile uniquely suited to diverse financing avenues. This credit coaching ensures owners receive expert guidance at every stage of credit profile development, from initial registration through multi-tier credit line acquisition. Practically, a business credit advisor will work alongside you to routinely check your fundability score and advise on concrete steps to improve vendor relationships, reporting accuracy, and payment behavior, all of which influence lender decisions significantly.
Building Multi-Tier Business Credit Lines
Constructing a strong business credit profile involves developing progressive credit tiers, each unlocking higher funding potential and reducing dependence on personal guarantees. This strategic layering is crucial to scalable, sustainable financial growth.
- Tier 1 – Net-30 Vendor Accounts: Establish foundational tradelines with vendors reporting payment activity to business credit bureaus like Dun & Bradstreet, Experian, and Equifax. Examples include office supplies or utility providers offering 30-day payment terms. Practically, opening accounts with vendors who report timely payments enhances your business credit visibility.
- Tier 2 – Small Revolving Credit Lines: Access low-limit business credit cards or lines of credit, typically under $10,000, requiring minimal or no personal guarantees. These products help demonstrate the company’s ability to manage revolving credit responsibly, further boosting fundability.
- Tier 3 – Institutional Credit Lines & Term Loans: Engage banks or credit unions for mid-range loans or equipment financing, often with limited personal guarantee requirements as creditworthiness improves. For example, purchasing new equipment on a term loan can improve operational capacity and credit metrics simultaneously.
- Tier 4 – Non-Personal Guarantee (Non-PG) Lines of Credit: Achieve high-limit loans, commercial real estate or SBA loans where personal guarantees diminish or are eliminated due to strong business credit performance. This level represents full financial independence enabled by excellent fundability and credit profile strength.
This tiered construction reflects a strategic path from foundational credit establishment to high-limit business credit, powered by expert business funding strategies. Emphasis on each tier's successful completion ensures creditworthiness grows methodically as you build business credit tied to your EIN, supporting greater capital access with reduced personal risk.
Curious where your business stands right now? Take the FREE Business Success Scan to see your current fundability snapshot and get a personalized roadmap for building toward higher-limit, lower-personal-risk financing, no impact to your personal credit.
Comparative Analysis: Business Credit Advisor vs. DIY vs. Loan Brokers
Step-by-Step Personalized Funding Strategy Blueprint
- Diagnosis: Comprehensive fundability assessment employing fundability consulting roadmap, Experian Intelliscore coaching, and SBA loan readiness checks to identify gaps and opportunities. This initial step uncovers critical factors such as payment track records, credit bureau inaccuracies, and entity structuring issues.
- Foundation Optimization: Implement entity structuring alignment, correct discrepancies in public filings, improve Paydex score through vendor payment consistency, and optimize capital stack for risk and liquidity balance. For instance, registering your business properly and ensuring vendor payments are always timely directly raise your business credit scores.
- Credit Bureau Reporting: Establish and monitor multi-tier tradelines reporting to major bureaus. Regularly audit credit reports to maintain accuracy and address anomalies such as outdated data or duplicate entries that could lower fundability.
- Strategic Capital Acquisition: Engage matched lenders from a wide network for tiered credit lines, including SBA and alternative funding, following a pre-approved, phased approach to minimize personal guarantees and maximize capital access. This includes submitting well-packaged applications aligned with each lender’s criteria.
Expanding the Role of Business Credit Advisors with Specialized Consulting Services
Beyond general advisory, advanced business funding consulting includes:
- Paydex Score Improvement: Targeted strategies to enhance this crucial Dun & Bradstreet score by managing timely vendor payments and instituting favorable trade relationships. For example, negotiating net-30 or net-60 terms with vendors that report payments can materially improve scores.
- Experian Intelliscore Coaching: Tailored guidance to improve credit standing through Experian's proprietary scoring, enabling better loan readiness. Coaches analyze behavior trends and suggest ways to avoid common pitfalls that could negatively impact your fundability.
- SBA Loan Readiness Preparation: Advisors assess and coach companies on documentation, entity status, and financial history to meet SBA stringent underwriting criteria. This includes helping prepare detailed business plans, financial projections, and ensuring compliance with entity structuring requirements.
This suite of services creates a holistic growth-oriented financial architecture for businesses, combining credit coaching with hands-on small business funding guidance. Implementing these services effectively elevates a company's position in the lending marketplace, directly influencing successful fund acquisition outcomes.
How Capital Stack Optimization Drives Sustainable Growth
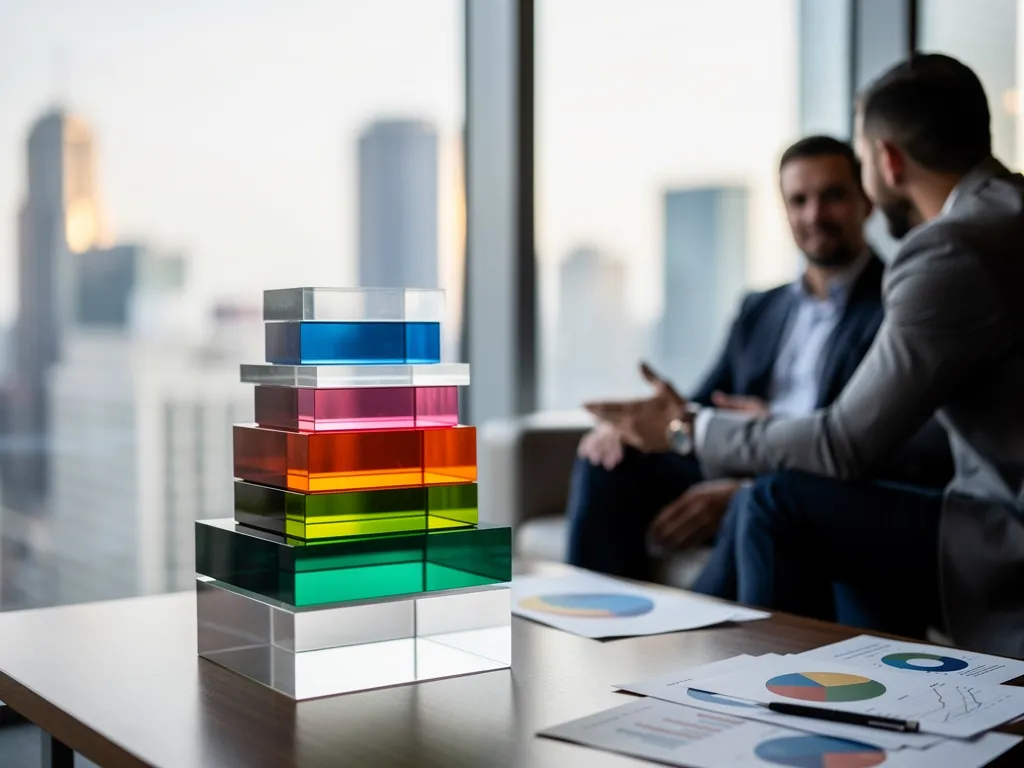
Advisors carefully balance diverse financing sources including vendor credits, revolving lines, equipment loans, and term financing, layered to mitigate risk while maximizing liquidity. Optimal capital stacks draw on:
- Low-cost, no or low-interest vendor credits, reducing overall funding expenses.
- Revolving credit with flexible drawdowns providing operational agility.
- Asset-backed loans to fund expansion, preserving cash flow while acquiring essential resources.
- Strategic SBA loans for scalability, offering longer repayment terms and competitive rates.
This calibrated layering reduces personal guarantees and preserves borrowing capacity, key to sustainable scaling under the guidance of a seasoned business funding expert. A well-optimized capital stack also supports strong business credit profiles and maintains healthy fundability scores needed for future funding opportunities.
Conclusion
Building a strong, independent business credit profile is one of the most important steps an entrepreneur can take to protect personal assets while unlocking the capital needed to grow. By working through a structured fundability review, methodically building multi-tier credit lines, and optimizing the overall capital stack, business owners can qualify for better financing terms and larger credit limits with fewer personal guarantees required along the way.
Partnering with a certified business credit advisor turns this process into a clear, step-by-step strategy rather than a series of guesses, helping owners move from foundational vendor credit to institutional and non-PG financing with confidence over time.
Frequently Asked Questions
How long does it take to build strong business credit?
Timelines vary by starting point, but most businesses see meaningful progress within 6 to 12 months of consistent vendor payment reporting and tier-building. Establishing Tier 1 net-30 vendor accounts early and paying them on time is the fastest way to start building a track record lenders can see.
Can I get a high-limit business credit line without a personal guarantee?
Yes, but it typically requires progressing through the credit tiers first. As a company's EIN-based credit profile strengthens through vendor accounts, small revolving lines, and institutional credit, lenders increasingly offer non-PG (non-personal-guarantee) financing, including larger credit lines and SBA loans.
Will building business credit affect my personal credit score?
When structured correctly, business credit is tied to the company's EIN rather than the owner's Social Security number, so day-to-day business credit activity doesn't appear on personal credit reports. This separation is exactly why establishing a distinct business credit identity matters from the start.
What is a fundability consulting roadmap?
It's a structured review of a business's credit profile, entity structure, and public records to identify what's holding back loan approval, then a step-by-step plan to fix those gaps before applying for financing. This reduces denials and wasted applications to lenders that were never a good fit.
Do I need a business credit advisor, or can I build credit on my own?
It's possible to build business credit independently, but a certified advisor brings access to vetted lender networks, error-correction expertise on credit reports, and a tested tier-building sequence, which generally results in fewer denials and faster progress toward higher-limit, lower-personal-risk financing.
Contact & Consultation
Get in touch with VIP Business Credit to start your personalized funding journey with expert business credit coaching and advisory services, serving Sterling, VA and the surrounding areas, including Reston, Arlington, Ashburn, and Tysons:
- 📞 Phone: +1 (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule A Business Financial Health Strategy Call
- 🌐 Website: vipbizfunds.com
- 🎯 FREE Business Funding Pre-Qualification Scan: Take the Free Business Success Scan
About The Author
Lee JohnsonCo-Founder & CEO of VIP Business Credit | Master Certified Professional Coach
Lee Johnson brings over 25 years of experience in business funding, credit building, and generational wealth strategies. He holds a Bachelor of Science from Fairleigh Dickinson University and an MBA from the University of Phoenix. As a Master Certified Professional Coach with over 500 coaching hours, Lee specializes in empowering entrepreneurs to establish strong business credit profiles tied to their EIN, separating personal liability and unlocking long-term funding. In addition to his advisory work, Lee is a seasoned real estate investor managing a portfolio of over 1,700 units valued at approximately $254M across multiple U.S. markets.
Research & Sources
Readiness assessments consistently show a strong correlation between loan approval rates and a company's business credit profile: businesses that proactively identify and correct credit gaps, such as reporting inconsistencies, outdated public filings, or thin trade history, tend to see materially higher approval odds and better loan terms than those applying without a prior review. Lenders also increasingly use automated screening tools, which means a company's credit data must be clean and consistent across bureaus before an application is ever submitted, reinforcing why a structured fundability review and staged credit-building sequence outperform a single, unprepared loan application.
Separately, establishing business credit under the company's EIN, rather than relying on the owner's personal credit, remains one of the most cited factors in protecting personal assets while scaling access to capital, a principle borne out across IRS EIN guidance and standard SBA underwriting criteria for business loan eligibility.


