Term Loan vs Line of Credit in VA in Northern Virginia
Term Loan vs Line of Credit in VA in Northern Virginia
Term loans deliver a lump sum repaid in fixed monthly installments. Lines of credit offer flexible, revolving capital with interest charged only on funds drawn. Northern Virginia business owners in Loudoun, Fairfax, and the D.C. metro choose based on need: equipment or expansion favors term loans; cash-flow gaps favor credit lines. VIP Business Credit matches both options through 1,000+ lenders nationwide.
Key Takeaways
- Term loans provide lump-sum funding upfront, while lines of credit offer flexible, draw-as-needed access to capital.
- VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders offering both financing options.
- Lines of credit work best for managing cash flow gaps; term loans suit major investments or equipment purchases.
What's the Real Difference Between These Two Loans?
A term loan vs line of credit VA decision comes down to one core structural difference: how the money arrives and how repayment works. A term loan delivers a lump sum upfront, repaid through fixed monthly installments over a set period. A line of credit works more like a reusable pool of funds, drawn on and repaid as needs change.
For a Northern Virginia business weighing equipment purchases against seasonal cash flow gaps, that structural difference matters more than the interest rate alone. Term loans typically carry a fixed rate, so payments stay consistent for the entire term. That predictability helps with budgeting around a large, one-time investment.
Accessing the right financing is a crucial part of staying stable and growing, especially for small business owners juggling payroll, rent, and inventory costs across the DC metro region. Understanding these differences before signing anything leads to decisions that actually fit the business, not just the moment.
Which loan type fits a growing Northern Virginia business?
Growth-stage companies planning a specific purchase, like a vehicle fleet or new office buildout, generally lean toward term loans because of their predictable structure. Businesses facing unpredictable cash flow timing, common across Loudoun and Fairfax County service industries, often benefit more from revolving credit.
Can a business use both at once?
Yes. Many companies pair a term loan for major investments with a credit line for day-to-day flexibility. This combination, central to any solid business funding comparison VA owners run, often produces the strongest overall credit profile.
Reviewing loan options Northern VA lenders offer, side by side, before applying prevents costly mismatches later.
When Should Northern Virginia Businesses Choose a Term Loan?
Major, planned purchases call for a term loan, not a revolving credit line. Businesses across Loudoun, Fairfax, and Arlington counties use this structure when the project has a clear price tag and a defined start date. A restaurant group in Reston replacing kitchen equipment, a logistics firm in Ashburn buying a delivery van, or a contractor in Fairfax consolidating older debt all fit this pattern. These are one-time investments, not ongoing operational costs.
The structure itself explains why. A term loan delivers one lump sum upfront, repaid through fixed monthly installments over a set period. Because the rate stays fixed, the payment amount never shifts. That predictability matters for Northern Virginia business owners trying to budget around a known cost, whether that's commercial real estate, machinery, or a vehicle fleet.
Is a term loan better for planned projects than unexpected expenses?
Yes. Structured, predictable payments work best for planned investments with a defined scope and timeline. Unexpected expenses or cash flow gaps are better matched to a flexible credit line. A term loan locks in the full amount regardless of whether the business ends up needing all of it.
Term loans in Northern Virginia typically make sense for:
- Purchasing equipment, machinery, or commercial vehicles
- Buying or renovating commercial real estate
- Consolidating existing high-interest business debt
- Funding a single, budgeted capital project with a known cost
VIP Business Credit connects Northern Virginia business owners to a network of more than 1,000 national. Local lenders offering term loan programs suited to these exact scenarios. That access matters because not every lender structures rates or terms the same way, and matching the right program to the right project protects long-term cash flow instead of straining it.
When Does a Line of Credit Make More Sense?
A business line of credit fits Northern Virginia companies managing uneven cash flow, covering payroll gaps, or stocking up before a busy season in Fairfax or Loudoun County. Interest applies only to the amount drawn, not the full credit limit sitting available. That structure makes a line of credit far cheaper for short bursts of spending than a lump-sum loan sitting unused.
Reston contractors waiting on municipal payment cycles know this problem well. So do Ashburn retailers restocking before a vacation rush. In both cases, a revolving credit line answers a timing problem, not a growth problem.
Is a line of credit better than a term loan for small businesses?
Neither option replaces the other; each solves a different problem. A term loan delivers structured, predictable payments suited to planned investments, like buying equipment or opening a second location. A line of credit offers flexible access to funds for fluctuations and unexpected expenses, the kind that arrive without warning.
Many Northern Virginia business owners use both products together, pairing one for long-term stability with one for day-to-day flexibility.
Consider a line of credit when:
- Revenue arrives inconsistently across the month or season
- Expenses pop up unpredictably (repairs, late invoices, inventory gaps)
- Funding needs change in size from month to month
- A planned purchase has already been financed through a term loan
When should a Northern Virginia business choose a term loan instead?
A fixed, one-time expense with a known price tag usually calls for a term loan instead. Expansion, major equipment, or a buildout project benefits from predictable monthly payments rather than a revolving balance. Understanding this distinction is part of any sound business funding comparison VA owners should run before applying. VIP Business Credit connects Northern Virginia businesses to lenders offering both loan options Northern VA companies rely on, helping owners match the right tool to the right expense.
How Do Local Virginia Lenders Structure These Products?
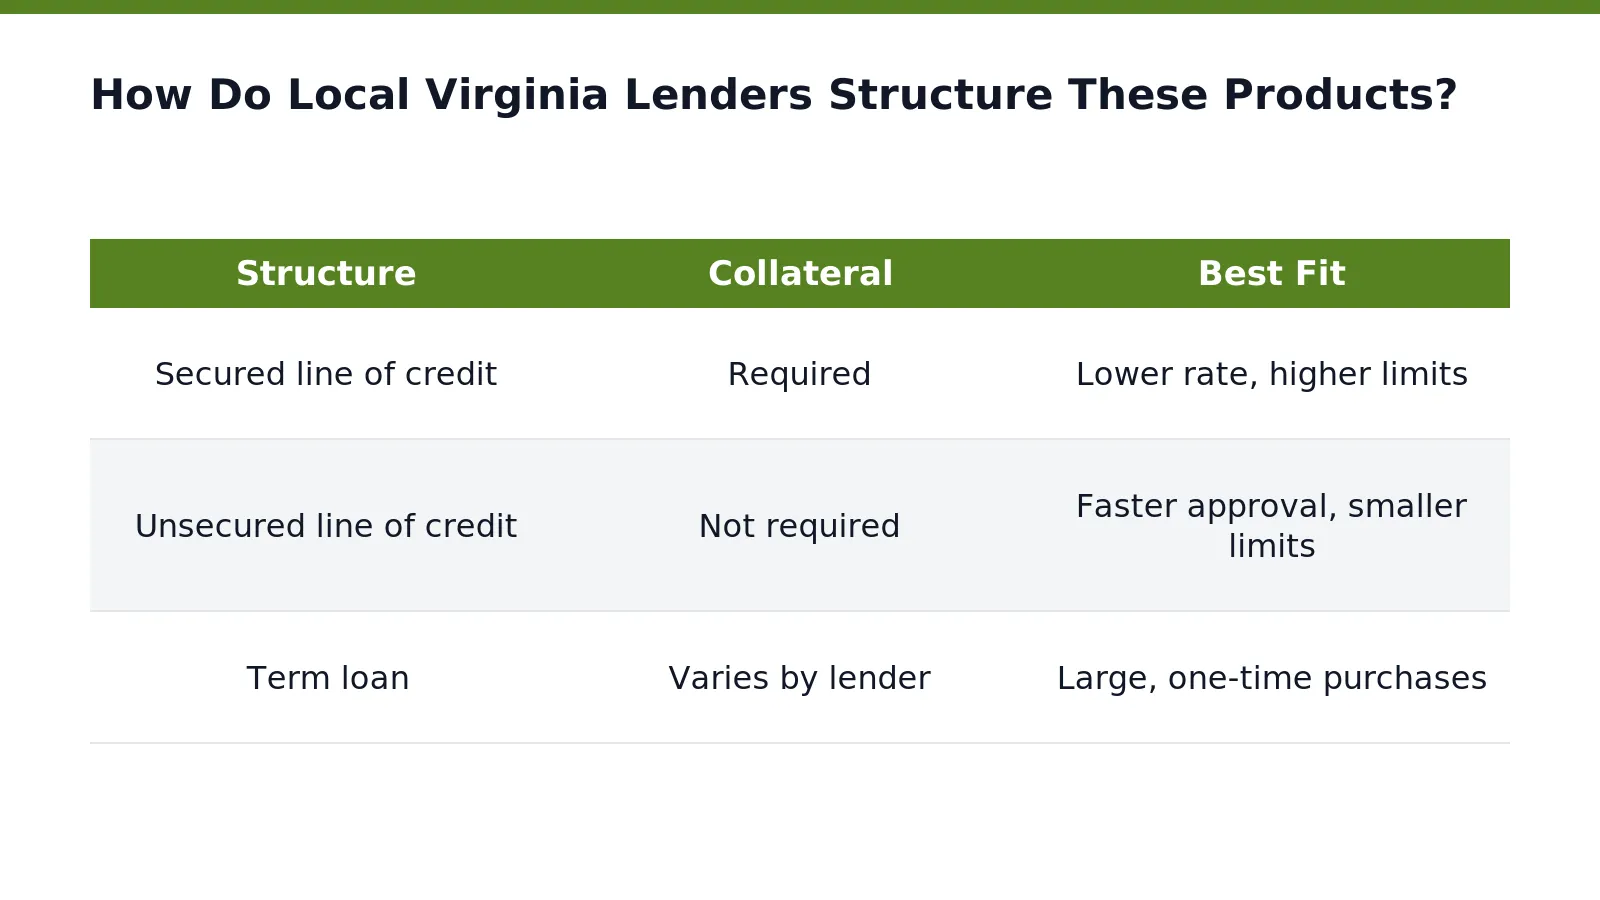
Virginia lending institutions build business credit products around collateral flexibility and relationship-based underwriting. Local banks serving Northern Virginia frequently offer both secured and unsecured business lines of credit, giving owners a choice based on their risk tolerance and available assets. A secured line usually carries a lower rate because the lender holds collateral. An unsecured line skips that requirement but often comes with tighter qualification standards.
Dedicated lending teams play a bigger role in Virginia than many owners expect. Rather than handing applicants a generic rate sheet, local teams sit down with business owners to map out which financing structure actually fits the situation. This matters for a Reston startup carrying seasonal cash flow swings and for an established Fairfax contractor financing new equipment. Each needs a different structure entirely.
What makes Virginia lenders different from national banks?
Personal service separates Virginia lenders from larger, impersonal national institutions. Many community banks and credit-focused firms in the region emphasize fast funding turnaround alongside direct access to a real decision-maker, not a call center queue.
Should a Northern Virginia business compare multiple lenders before choosing?
Comparing options protects against overpaying for capital or accepting restrictive terms. A single lender relationship rarely reveals how competitive the broader market is.
VIP Business Credit, based in Sterling, VA, extends this comparison process further for clients across Ashburn, Fairfax, and the wider D.C. metro area. Rather than relying on one bank's product menu, the firm connects owners to a wider lender network, supporting genuine business funding comparison VA decisions instead of single-source guesswork.
Owners weighing a term loan vs line of credit VA decision should treat local structure differences as a starting point, not the final word, when reviewing loan options Northern VA wide.
Can Home Equity Fund Your Northern Virginia Business?
Yes. A home equity line of credit lets Northern Virginia property owners borrow against their home's value. Turn that equity into working capital. For a business owner in Fairfax or Reston sitting on substantial home equity, this can look like an easy shortcut to funding. But the loss framing matters here: tapping personal home equity means the business owner's house, not just the business, carries the risk if revenue dips.
Some Virginia HELOC programs allow qualified borrowers to access up to $500,000 in equity, with typical loan amounts ranging from $10,000 to $500,000 depending on the lender and the property's value. Fixed-rate HELOC options add another layer of predictability, locking in a rate that never changes for the life of the loan. That stability helps with budgeting, but it does nothing to separate personal liability from business liability.
Is a HELOC a Good Way to Fund a Small Business?
A HELOC can supply fast cash, but it ties business risk directly to personal real estate. If the business struggles, the home itself becomes exposed to foreclosure risk. Business owners comparing financing paths should weigh this against options that keep personal assets separate from the company's credit profile.
What's the Safer Alternative to Home Equity Borrowing?
Building credit under the business's own EIN, rather than borrowing against a house, keeps personal and business liability apart. This approach matters for a true business funding comparison VA owners can trust long-term.
For owners weighing every available loan options Northern VA has to offer, separating personal and business risk often outweighs short-term convenience.
What Factors Should Shape Your Financing Decision?
Repayment structure, cash flow timing, and the purpose of the funds determine which financing option fits a Northern Virginia business best. A term loan vs line of credit VA decision affects more than monthly costs. It shapes how smoothly daily operations run for a restaurant group in Fairfax or a contracting firm in Loudoun County.
Financing choices should match a business's specific goals and its natural cash flow pattern, not a generic formula. A seasonal landscaping company in Ashburn has different rhythm needs than a year-round medical practice in Reston. Matching structure to rhythm prevents cash shortages before they happen.
Which Option Fits Which Situation?
Structured, predictable payments work best for planned investments like equipment purchases or facility buildouts. Flexible access to funds suits businesses facing fluctuating revenue or unexpected expenses, such as a Northern Virginia retailer managing vacation inventory swings. One option locks in certainty; the other preserves flexibility.
Why Does This Decision Carry Long-Term Weight?
Every financing decision shapes a business's future, not just its next quarter. Choosing poorly can strain cash flow for years. A careful business funding comparison VA owners can trust starts with honest evaluation of goals, revenue timing, and growth plans before signing anything.
Business owners weighing loan options Northern VA wide benefit from guidance that connects their specific situation to the right lender network. VIP Business Credit works with clients across the region to match financing structure to actual business rhythm, not guesswork.
How Can You Build Credit Before You Borrow?
Business credit starts with the company's EIN, not the owner's Social Security number. VIP Business Credit helps entrepreneurs across Northern Virginia and the greater Washington, D.C. region establish EIN-based business credit profiles before they ever submit a loan application. This separation protects personal assets and gives lenders a cleaner picture of the business itself.
A proprietary scoring tool shows exactly how underwriters view a company's current credit standing. This step matters because gaps in a credit file, like missing trade references or inconsistent business details, can quietly disqualify an otherwise strong applicant. Spotting those gaps early means fixing them before a lender ever runs a report.
Why Build Credit Before Applying for a Loan?
Lenders reward businesses that look established and low-risk on paper. A business owner in Reston or Fairfax who builds credit first typically qualifies for larger loan amounts. Better pricing than one who applies cold. Skipping this step often means settling for smaller limits or higher rates, simply because the lender has less reason to trust the file.
What Role Do Lenders Play in This Process?
Access matters as much as preparation. With connections to more than 1,000 national and local lenders, financing strategies can be matched to a business's specific stage, sector, and risk profile. A newer company in Ashburn may need a different lender type than an established contractor in Fairfax. Broad access makes that match possible.
Before comparing a term loan vs line of credit VA style decision, business owners in Sterling, Ashburn, Reston, and Fairfax benefit from this groundwork. A solid credit file turns a basic business funding comparison VA into a stronger negotiating position. It widens the pool of realistic loan options Northern Virginia companies can actually secure.
What's Your Next Step Toward Smarter Business Funding?
Moving forward starts with matching a financing structure to actual business needs, not guesswork. Northern Virginia business owners in Ashburn, Reston, Fairfax, and across the D.C. metro region face a crowded field of lenders and loan products. Picking wrong costs time, cash flow, and sometimes personal liability. A clear, guided process removes much of that risk.
How does a business owner pick between a term loan and a line of credit?
The right choice depends on goals and cash flow timing, not on which product sounds more familiar. A term loan vs line of credit VA decision becomes easier once a business maps its financing to its specific rhythm: one-time investments call for structured repayment, while fluctuating revenue calls for flexible access. This kind of business funding comparison VA owners can rely on starts with honest answers about how money moves through the business month to month.
Where can Northern Virginia businesses find the right loan options?
Northern Virginia owners don't need to rely on a single bank's limited menu. VIP Business Credit connects businesses to a lender network exceeding 1,000 national and local options, giving each applicant access to financing matched to their stage, sector, and risk profile. That range matters because loan options Northern VA businesses qualify for vary widely between a two-year-old consulting firm in Fairfax. An established logistics company in Loudoun County.
VIP Business Credit's office, based in Sterling, Virginia, serves as the operational hub supporting business owners throughout Northern Virginia. Advisors work directly with clients across Ashburn, Reston, and the surrounding D.C. metro area, translating lender requirements into practical next steps.
The smartest next move is simple: compare financing structures side by side before applying anywhere. A term loan locks in predictable payments; a line of credit offers breathing room. Paired with access to a broad lender network, Northern Virginia business owners gain the clarity needed to choose financing that actually fits, rather than financing that happened to be offered first.
FAQ
What is the main difference between a term loan and a line of credit?
A term loan delivers a lump sum repaid in fixed monthly installments. A line of credit offers revolving capital with interest charged only on funds drawn.
Which financing option fits equipment purchases or expansion in Northern Virginia?
Term loans suit equipment purchases and expansion because they provide upfront lump-sum
Conclusion
In closing, choosing between a term loan and a line of credit depends on your specific business need, cash flow pattern, and growth timeline. Term loans work best for defined, one-time investments; lines of credit provide flexibility for ongoing operational needs. Understanding which structure aligns with your situation positions you to access capital efficiently. Build sustainable business credit tied to your EIN. The right financing choice becomes clear when you match the tool to your actual business challenge.


