Secured Credit Line: Secured Business Line of Credit
Secured Credit Line: Secured Business Line of Credit
By *VIP Business Credit* Editorial Team · Updated 2026-08-05
Key Takeaways
- Secured business lines of credit require collateral such as cash deposits, equipment, inventory, or real estate to back the account.
- VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders for secured line of credit options.
- Cash-secured lines start with a minimum deposit set by the lender and may lead to unsecured credit over time, depending on consistent payments and business growth.
- Secured revolving lines vary widely in size depending on the pledged asset's value and lender requirements for Northern Virginia businesses.
What Is a Secured Business Line of Credit?
A secured credit line is revolving credit backed by a pledged asset instead of a promise alone. Equipment, inventory, real estate, or cash deposits can all serve as that backing, giving lenders a fallback if payments stop. Business owners draw funds as needed, repay them, and draw again. The credit line replenishes rather than closing out like a term loan.
Lenders often call this arrangement an **asset backed line of credit** because the approval and credit limit hinge on what the business pledges. A company with strong equipment or inventory value may qualify for a larger limit than its cash flow alone would support. That pledge lowers the lender's risk, which frequently translates into better rates and terms for the borrower.
How Do Pledged Assets Affect Approval Odds?
Pledging an asset shifts risk away from the lender and onto specific business assets. Companies with limited credit history often find approval easier with collateralized credit than with unsecured options. Unsecured lines lean almost entirely on the owner's credit profile instead: many bank programs expect a personal credit score above 700 and at least two years of operating history before extending credit without security. The pledged asset reduces the lender's downside, so a newer business or an owner who hasn't cleared those thresholds yet can still qualify. Newer businesses, in particular, benefit from this trade-off while they build a stronger credit profile.
Business owners across Northern Virginia and the Greater Washington, DC region work with VIP Business Credit to build EIN-based business credit that strengthens applications for secured lines. That foundation matters because lenders review both the asset offered as security and the underlying credit profile of the business itself.
Where Do These Credit Lines Come From?
Secured lines come from a wide range of sources, not a single lender type. VIP Business Credit connects clients to more than 1,000 national and local lenders offering both secured and unsecured products, which widens the field of options considerably. That access matters because terms, security requirements, and rates vary significantly from one lender to the next.
How Does a Cash Secured Credit Line Work?
A secured credit line ties directly to cash a business owner deposits upfront, rather than to a credit score or years in operation. Business owners typically open the account by funding it with a minimum deposit set by the lender. That deposit acts as security, giving lenders confidence to extend credit even to newer or credit-challenged businesses.
The deposit amount and the credit line amount move together. Whatever a business puts down becomes the exact limit it can draw against, which means owners know their obligation from day one, no guesswork, no surprise ceiling. For example, a business that opens a cash secured line with a $25,000 deposit typically receives a $25,000 draw limit, the two figures track dollar for dollar under most lender programs. Put down $50,000 instead, and the available credit line doubles to match. This structure is a straightforward form of collateralized credit: the lender's risk shrinks because the funds are already sitting in reserve.
Is a Cash Secured Line the Same as an Asset Backed Line of Credit?
Not exactly, though the two share a family resemblance. An asset backed line of credit can be secured by inventory, equipment, or receivables. A cash secured line uses liquid deposits as the sole backing. Both reduce lender risk, but cash-backed lines tend to open faster since the pledged funds are already verified and sitting in an account.
The underwriting gap between the two options runs deeper than approval speed. Unsecured lines demand no pledged asset but typically come with smaller credit limits and higher interest rates, while secured lines trade a slower approval process for higher limits and better pricing over time.
How Does This Fit Into a Broader Cash Flow Strategy?
A secured line rarely stands alone as a cash management tool. VIP Business Credit's cash flow management service pairs credit line setup with hands-on negotiation of vendor payment terms, including Net-30, Net-60, and Net-90 arrangements. Aligning those terms with the credit line's draw schedule gives controllers more breathing room between outgoing payments and incoming revenue.
For CFOs managing tight working capital cycles, that combination matters. A cash secured line covers short-term gaps. Negotiated vendor terms stretch the runway further, reducing reliance on the credit line itself.
What Assets Can Back Your Credit Line?
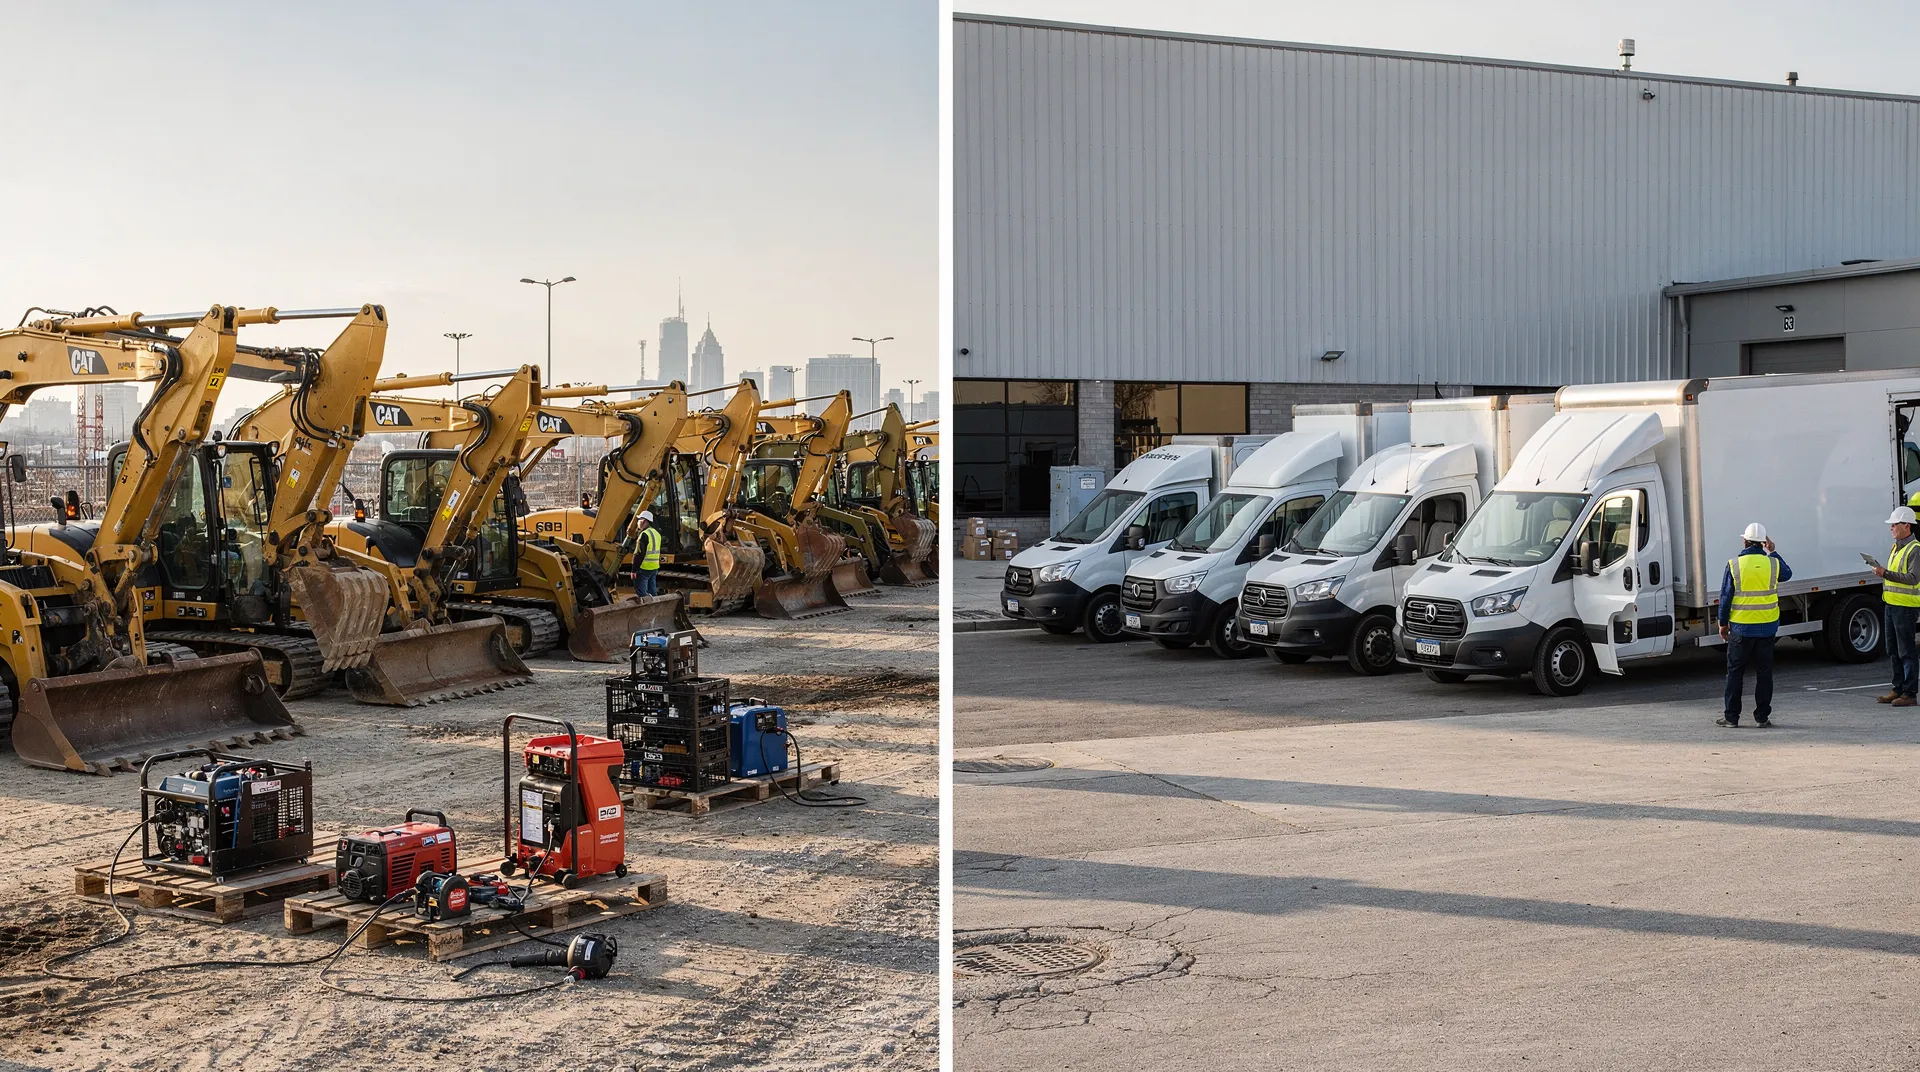
Equipment, vehicles, and cash deposits can all serve as the pledged asset backing a business credit line. Lenders accept these assets because they reduce risk, and that lower risk translates into real savings. An asset backed line of credit typically carries lower interest rates and higher borrowing limits than a line based on creditworthiness alone. For a financial controller managing tight margins, that difference shows up directly on the balance sheet. Two asset categories stand out for growing businesses: equipment credit lines and fleet vehicles.
- Equipment Credit Lines: These allow a business to acquire needed machinery or tools right away. The business builds credit history while using the equipment, and payments qualify as deductible business expenses.
- Fleet Credit Lines: Multiple vehicles can be financed under one line. Each on-time payment strengthens the business credit profile, and the arrangement locks in valuable tax deductions.
Is Collateralized Credit Better Than an Unsecured Line?
Collateralized credit generally beats an unsecured line on cost and capacity. Because the lender holds a claim on a physical asset, underwriters extend larger limits at lower rates than they would offer a business relying on credit history alone. Unsecured approval, by contrast, typically hinges on the owner's personal credit: many lenders look for a FICO score above 680 and at least six months of operating history before extending credit with no security attached. That structure matters most for companies scaling fast and needing capital beyond what an unsecured facility provides, or for owners who haven't yet built the credit profile unsecured lenders require.
Which Asset Type Fits a Growing Business Best?
The right asset depends on operational need. A construction firm expanding its toolset benefits most from equipment-backed credit, since the machinery itself secures the line. A logistics company adding delivery routes gains more from fleet-backed credit, which finances vehicles while building the business credit file. A medical or dental practice upgrading diagnostic equipment follows a similar pattern, pledging the new equipment itself rather than tying up cash reserves that could otherwise cover payroll or lease obligations. A retailer building up seasonal inventory ahead of peak demand often leans on cash-secured or receivables-backed lines instead, since inventory value fluctuates and few lenders will extend equipment-style terms against stock that turns over every few months. Both paths turn a necessary purchase into a credit-building opportunity, rather than a stand-alone expense.
Secured or Unsecured: Which Line Fits You?
Borrowing needs and the availability of pledgeable assets decide the answer, not preference alone. Owners with strong revenue but limited assets typically qualify for smaller, unsecured amounts. Those willing to pledge an asset as security open the door to significantly larger credit lines.
Both paths serve different growth stages. A secured credit line ties borrowing power to business or personal assets pledged as security. An unsecured line relies purely on revenue and credit history.
Does Pledging an Asset Get a Business More Money?
Yes. Businesses that pledge assets through an asset backed line of credit can typically access higher revolving limits than unsecured options. Pledging an asset reduces the lender's risk if payments stop. Lenders extend larger amounts because that pledged asset provides a fallback. That trade-off matters most for companies planning equipment purchases, inventory expansion, or multi-year projects.
How does a business know which option it qualifies for?
Qualification depends on financial history, collateral value, and existing credit gaps. VIP Business Credit's fundability scan gives owners a clear picture of where their business stands before applying, typically in 2 to 5 minutes and with zero impact on the owner's personal credit score. The scan identifies gaps that might block approval and builds a roadmap toward the right product.
Controllers comparing both paths should weigh cash flow needs against asset flexibility. Collateralized credit unlocks stronger limits, but it also puts pledged assets at risk if repayment slips. Unsecured lines protect those assets while capping the available credit at a lower ceiling. Matching the choice to actual growth plans, rather than chasing the largest number available, keeps financing sustainable long-term.
Many lenders also require a personal guarantee on top of whatever asset backs the line, meaning the owner remains personally responsible for repayment if the business can't cover it. That guarantee shows up on both secured and unsecured products, so pledging business assets doesn't automatically remove personal exposure. Understanding where a personal guarantee applies, and where it doesn't, is part of evaluating the real risk behind either option.
Find Out What Your Business Qualifies For
Not sure whether a secured or unsecured line fits your current stage? A free Business Fundability Scan shows exactly where your business stands with lenders before you apply, so you can target the right credit line instead of guessing.
How Much Can You Actually Borrow?
Borrowing limits on a secured credit line depend heavily on the asset pledged and the lender's program. Many asset-backed options allow qualified businesses to access significantly higher limits than unsecured options. Interest applies only to the amount drawn, not the full approved limit. That structure matters for financial controllers managing tight cash flow projections, since unused credit costs nothing while it sits available.
Small and mid-sized businesses without this kind of access often overpay for capital they don't need yet, tying up funds in lump-sum loans that accrue interest from day one. An **asset backed line of credit** avoids that trap. Draw what the payroll run or inventory purchase requires, repay it, and the credit line replenishes automatically. No reapplication, no fresh underwriting cycle for every draw.
Consider a business with a $100,000 secured line backed by equipment and receivables. If it draws $30,000 to cover a seasonal inventory purchase, interest accrues only on that $30,000, not the remaining $70,000 sitting untouched. Once the business repays that draw, the full $100,000 becomes available again without a new application. That repeatable cycle is what separates a revolving line from a term loan, where the entire balance accrues interest from disbursement regardless of whether the business has put the funds to work yet.
Does the borrowing limit change over time?
Limits on collateralized credit typically grow as a business builds payment history and strengthens the assets backing it. Lenders reassess risk based on repayment behavior, so consistent, on-time draws and repayments often unlock higher ceilings at renewal.
What determines the exact number a business qualifies for?
No single formula applies across every lender. VIP Business Credit connects business owners to a network spanning traditional banks, alternative finance providers, and specialized lending programs, so a credit ceiling can be matched to the company's stage, industry, and risk profile rather than a one-size-fits-all cap. Owners who want a baseline before approaching that network typically start with the firm's 12-month business credit coaching program, which pairs EIN-based credit building with ongoing access to the lender pool, so a company's qualifying ceiling tends to move as the underlying credit file strengthens, not just as revenue grows.
Factors that typically shape the final number include a business's fundability score alongside the following:
- Pledged asset value — equipment, receivables, or deposits pledged against the line
- Business stage — newer ventures often start lower than established firms
- Industry risk profile — some sectors qualify for higher ceilings than others
- Repayment history — consistent draws and payoffs support future increases
How Do You Qualify and Graduate?
Qualification hinges on payment history, time in business, and revenue — not a credit score alone. Lenders reviewing a secured credit line want proof that a company manages debt responsibly before removing the security requirement. Missing that proof costs business owners years of unnecessarily tied-up cash and slower access to larger credit lines.
Graduation follows a predictable path. Account reviews that determine eligibility for an unsecured line typically start at the 12-month mark, once a consistent record of on-time payments exists. For companies under the same ownership for two years and generating consistent, qualifying annual revenue, transitioning away from an asset backed line of credit becomes realistic. Reaching that milestone often means the deposit or pledged asset backing the account gets released entirely.
What Does the Review Process Actually Check?
Reviewers look at payment consistency, revenue trends, and how long the current ownership has run the business. A spotless 12-month payment record carries significant weight in that evaluation. Businesses that miss payments or show insufficient revenue usually stay on collateralized credit terms longer.
How Can Owners Prepare Before Applying?
Preparation starts with knowing exactly where the business stands. VIP Business Credit's pre-qualification workflow shows owners which financing programs they qualify for right away and which ones require more groundwork first. That clarity prevents wasted applications and protects credit inquiries from piling up.
Having the right paperwork ready also speeds up the review itself. Lenders typically ask for recent business bank statements, profit and loss statements covering the last 12 months, a balance sheet, an accounts receivable aging report, and both business and personal tax returns. Assembling these before applying, rather than scrambling after a lender requests them, shortens the time between application and funding decision.
A proprietary scoring tool, the Fundability Score, adds another layer of insight, backed by a broader platform that includes a Funding Explorer for surfacing best-fit products and Bureau Insights for monitoring how the credit bureaus lenders rely on actually see the file. It shows business owners precisely where their company stands with lenders before they ever submit an application. Combined with steady payment habits, that visibility turns the graduation timeline from guesswork into a clear, trackable plan.
How Does VIP Business Credit Help You?
VIP Business Credit puts a small, hands-on team behind every client's financing goals. Based in Sterling, Virginia, the firm operates with just 3 employees, which means clients work directly with people who know their file. not a call center reading from a script. That concierge-level structure matters for controllers and CFOs who need answers fast, not a ticket number.
Building a strong credit profile requires more than applying for financing once and hoping for the best. It requires consistent, reportable activity over time. VIP Business Credit addresses this by placing clients with pre-qualified vendors in their industry who report payment activity to major credit bureaus, laying the groundwork for a secured credit line or better.
How does vendor placement build business credit?
Vendor accounts create a track record. When a vendor reports on-time payments to the bureaus lenders check, that history becomes evidence of reliability. The same evidence underwriters look for before approving an asset backed line of credit. Dun & Bradstreet's Paydex score, which tracks payment timeliness on a 0-100 scale, is one of the benchmarks lenders reference most often, and a score of 80 or higher typically signals the kind of reliable payment history that supports stronger approval terms.
Research Note: Payment Scoring
Dun & Bradstreet, one of the major commercial credit bureaus, compiles reported trade-line payment data into the Paydex score, a 0-100 rating that reflects how consistently a business pays its obligations. Lenders and vendors reference that score when assessing creditworthiness, which is part of why consistent, on-time vendor payments carry weight well beyond the vendor relationship itself.
Does the support stop after approval?
No. VIP Business Credit provides ongoing account management to confirm reporting accuracy, keep payment schedules on track, and strengthen the credit profile monthly.
That management includes a progressive plan built for growth:
- Expanding available credit limits as the business matures
- Diversifying vendor relationships to broaden reporting sources
- Monitoring account performance so gaps get caught early
- Preparing the profile for stronger collateralized credit terms over time
Each step builds toward the next, so financing options expand as the business loans does — not the other way around.
What's Your Next Step Toward Funding?
Business owners move forward by starting with a clear picture of their credit standing, not a loan application. A Business Fundability Scan shows exactly where a company stands with lenders, exposing credit gaps before they turn into denials. That single step saves owners from wasted applications and hard credit pulls that damage a fundability profile before financing even begins.
From there, the path typically involves building toward a secured credit line, an asset backed line of credit, or another form of collateralized credit matched to the business's stage and cash flow needs. Each option carries different security requirements and reporting implications, so sequencing matters.
How does VIP Business Credit support that process?
Advisors verify that vendor accounts report correctly to Dun & Bradstreet, since inaccurate reporting undermines the credit file lenders review. Errors get escalated quickly, protecting the data underwriters trust when setting terms and limits. This attention to reporting accuracy is what separates a fundable business profile from one that stalls out during underwriting.
Is this a one-time transaction or ongoing support?
VIP Business Credit operates as a long-term partner, not a broker chasing a single closed deal. Pricing stays transparent from the first conversation, with no hidden fees surfacing later. That structure gives controllers and CFOs a predictable partner for financing decisions that unfold over months, not days.
Local business owners can connect in person at the Sterling, Virginia office located at 21000 Southbank St Ste 106-380, Sterling VA 20165. Companies outside the immediate area work with the same advisors digitally, receiving the identical scan, reporting checks, and long-term guidance regardless of location.
FAQ
What collateral qualifies for a secured business line of credit?
Cash deposits, equipment, inventory, or real estate all serve as collateral. The pledged asset backs the account, giving lenders a fallback if payments stop and often resulting in better rates and terms.
How much can a business borrow with a secured line of credit?
Secured revolving lines vary widely for Northern Virginia businesses, depending on collateral amount and lender requirements. Cash-secured lines start with a minimum deposit set by the lender.
Where can Northern Virginia business owners find secured line of credit options?
VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders offering secured line of credit options. This access widens the field since terms, collateral requirements, and rates vary by lender.
What happens if a business misses a payment on a secured line of credit?
Missing a payment puts the pledged asset at risk, since the lender can claim it to recover its losses. A missed payment can also reset the timeline toward graduating to an unsecured line, since reviewers look for a consistent, on-time payment history before removing the security requirement.
Can a business switch from a secured line to an unsecured line later?
Yes. Businesses that build a steady 12-month or longer payment record, show consistent qualifying revenue, and keep the same ownership for at least two years often become eligible to graduate to an unsecured line, with the pledged asset released once that milestone is reached.
Facts
- VIP Business Credit is located in Sterling, VA, US.
- VIP Business Credit helps entrepreneurs in Northern Virginia and the Greater Washington, DC region build EIN-based business credit.
- VIP Business Credit connects to over 1,000 national and local lenders.
- VIP Business Credit offers a proprietary tool called Fundability Score.
About The Author
Lee Johnson is the Co-Founder & CEO of VIP Business Credit, a seasoned Real Estate Investor, Business Growth Strategist, and Master Certified Professional Coach with more than 500 coaching hours and over 25 years of experience in business funding, credit building, and generational wealth strategies. He holds a Bachelor of Science from Fairleigh Dickinson University and a Master of Business Administration from the University of Phoenix. Since 2005, Lee has built a personal real estate investment portfolio of over 1,700 units valued at approximately $254 million across multiple U.S. markets. Lee's mission is to help small business owners — including those in home services, trucking, and real estate — achieve financial freedom by first establishing a strong business credit profile, then accessing the highest loan amounts at the best terms available. He and the VIP Business Credit team serve business owners nationwide through the company's signature 12-month business credit coaching program.
Connect with Lee and VIP Business Credit:
- 📞 Phone: [+1 (571) 248-3863](tel:+1 (571) 248-3863)
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule a Consultation
- 🌐 Website: vipbizfunds.com
- 🎯 FREE Business Funding Pre-Qualification Scan: Start Your Scan
- 📍 Location: Sterling, VA and surrounding areas, including Tysons, Fairfax County, Ashburn, and the Washington, DC metro
Conclusion
Choosing between a secured and unsecured business line of credit comes down to what a business can pledge and what it needs the financing to do. A secured credit line, whether backed by cash, equipment, inventory, or receivables, typically unlocks higher limits and better pricing in exchange for a pledged asset. An unsecured line protects those assets but caps borrowing power at a lower ceiling tied mostly to credit history and revenue.
Neither path is permanent. Businesses that build a consistent payment record, strengthen the assets backing their line, and maintain steady revenue often graduate from a secured arrangement to an unsecured one, freeing up pledged assets along the way. Understanding where personal guarantees apply, what documentation lenders expect, and how vendor reporting builds a credit file turns that decision from a guess into a plan.
For business owners in Northern Virginia and the Greater Washington, DC region, matching the right product to the right stage of growth starts with a clear picture of where the business stands today, not with the application itself.
Ready to Take the Next Step?
Whether you're exploring a cash-secured line, an asset backed line of credit, or want to know if you already qualify for unsecured financing, VIP Business Credit's team can walk you through the options. Schedule a consultation or start with a free Fundability Scan to see where your business stands today.


