Business Credit for Trucking Companies: How to Get Funded Without Personal Guarantees
Business Credit for Trucking Companies: How to Get Funded Without Personal Guarantees
Securing business credit is a crucial step for trucking companies looking to thrive in a competitive market. Many trucking businesses face financing challenges, particularly when personal guarantees are involved. This article will explore how trucking companies can obtain funding without risking personal assets, focusing on the importance of business credit, the application process, and various funding sources available. Readers will learn about the eligibility criteria, benefits of non-personal guarantee funding, and how to build a **strong business credit profile**. By the end of this guide, trucking companies will have a clear understanding of how to navigate the funding landscape effectively. This guidance applies equally to trucking companies throughout the Washington D.C. metro area, including those based in Ashburn, Tysons, Reston and Herndon, Arlington, and Fairfax County.
While the goal is to avoid personal guarantees, it's important to understand the historical context and challenges where they were often deemed necessary for businesses to qualify for credit.
Research on small business lending has documented cases where a lender certified that a business would not have qualified for credit without a personal guarantee, with the guarantee required as a condition of the loan. — Loan Guarantees: Costs of Default and Benefits to Small Firms, A.L. Riding, 2001
Key Takeaways
- Trucking companies can secure business credit without personal guarantees by building a strong business credit profile.
- Establishing an EIN and registering with business credit bureaus separates personal and business finances effectively.
- Eligibility for non-personal guarantee funding typically requires operational history, minimum revenue, and solid credit profiles.
- Funding sources without personal guarantees include vendor credit lines, community bank loans, and invoice factoring.
- Non-personal guarantee funding protects owners’ personal assets and improves business credibility with lenders and suppliers.
- EIN-only loans allow trucking companies to obtain financing based on business credit without risking personal assets.
- Building business credit involves legal entity registration, opening business bank accounts, and establishing trade lines with vendors.
- Regularly monitoring and managing business credit scores enhances funding opportunities and loan terms for trucking companies.
- SBA loans and alternative financing options offer favorable terms for trucking companies seeking funding without personal guarantees.
Application Process
The application process for business credit involves several key steps that trucking companies must follow to secure funding. First, it is essential to research various funding options available in the market. This includes understanding the types of loans and credit lines that do not require personal guarantees. Next, companies should prepare the necessary documentation, which typically includes financial statements, business plans, and proof of revenue. Finally, submitting the application accurately and promptly is crucial to ensure a smooth approval process.
Eligibility Criteria
To qualify for business credit, trucking companies must meet certain eligibility criteria. Common requirements include:
- Business Operation Duration: Lenders often prefer businesses that have been operational for a minimum period, typically at least six months to a year.
- Annual Revenue Requirements: Many lenders set a minimum annual revenue threshold that businesses must meet to qualify for funding.
- Strong Business Credit Profile: A solid business credit profile is essential, as it reflects the company's creditworthiness and ability to repay loans.
Meeting these criteria increases the chances of securing funding without personal guarantees.
Potential Funding Sources
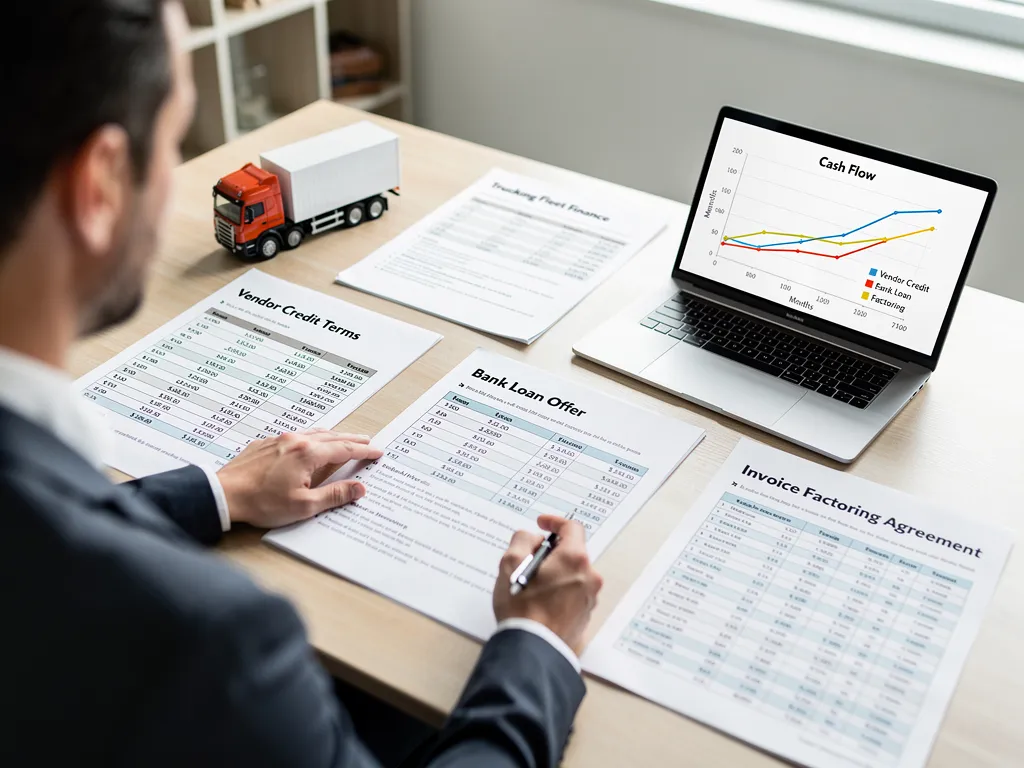
Trucking companies have access to various funding sources that can provide the necessary capital without requiring personal guarantees. Some of these options include:
- Vendor Credit Lines: These allow businesses to purchase goods and services on credit, helping to manage cash flow.
- Community Bank Loans: Local banks often offer favorable terms for small businesses, including trucking companies.
- **Invoice Factoring**: This involves selling unpaid invoices to a third party at a discount, providing immediate cash flow.
This table highlights the various funding sources available to trucking companies, showcasing their unique benefits.
Academic research further supports the significance of trade credit for the operational dynamics of trucking firms.
A study of trade credit supply among French trucking firms used a difference-in-differences approach to isolate how shocks to trucking firms' finances affected the credit extended to them by suppliers, underscoring how closely trade credit access is tied to a trucking firm's financial standing. — Trade Credit and Industry Dynamics: Evidence from Trucking Firms, J.N. Barrot, 2016
The evolution of alternative financing methods, such as invoice factoring, has significantly broadened options for businesses seeking immediate cash flow.
The factoring and invoice discounting industry has grown substantially, with a rising number of companies and banks now offering these services as invoice discounting has become an increasingly mainstream financing tool. — Factoring: The Law and Practice of Invoice Finance, 2006
Benefits of Non-Personal Guarantee Funding
Securing funding without personal guarantees offers several advantages for trucking companies. These benefits include:
- Asset Protection: By avoiding personal guarantees, business owners can protect their personal assets from potential business liabilities.
- Improved Credibility: Establishing a strong business credit profile enhances the company's credibility with lenders and suppliers.
- Access to Higher Credit Limits: Companies that build a solid business credit history may qualify for larger credit limits, enabling them to scale operations effectively.
These benefits make non-personal guarantee funding an attractive option for trucking companies seeking financial stability.
Ready to build a business credit profile that stands on its own? VIP Business Credit helps trucking companies establish EIN-only credit, open the right trade lines, and qualify for funding without putting personal assets on the line. Start your free Business Success Scan to see where your business stands today.
What Is Business Credit and Why Is It Essential for Trucking Companies?
Business credit refers to the creditworthiness of a business, which is evaluated based on its financial history and credit profile. It is essential for trucking companies for several reasons:
- Access to Funding: A strong business credit profile allows companies to secure loans and credit lines necessary for operations and growth.
- Separation of Finances: Business credit helps separate personal and business finances, reducing personal liability.
- Credibility Enhancement: A solid business credit score enhances the company's reputation with lenders and suppliers.
What Is Business Credit and How Does It Differ From Personal Credit?
Business credit is a measure of a company's creditworthiness, similar to personal credit scores. It is determined by various factors, including payment history, credit utilization, and the length of credit history, and a higher score indicates a lower risk for lenders, making it easier for companies to secure financing. It differs from personal credit in several key ways: while personal credit scores are based on an individual's financial behavior, business credit scores reflect the financial health of the business itself, and business credit does not impact personal credit scores, which allows owners to keep their personal financial standing separate from the company's.
Why Business Credit Matters for Trucking Companies
For trucking companies, business credit is crucial because it directly impacts their ability to obtain financing. Companies with strong business credit profiles are more likely to receive favorable loan terms, lower interest rates, and higher credit limits, since lenders view higher scores as a sign of lower risk. This access to funding is vital for maintaining and expanding operations in a competitive industry, and it shapes the terms companies are offered whenever they seek new capital.
Benefits of Business Credit
Having a strong business credit profile offers several benefits, including:
- Better Financing Options: Companies with strong credit can access a wider range of financing options, including loans with lower interest rates.
- Improved Cash Flow Management: Business credit allows companies to manage cash flow more effectively, ensuring they can meet operational expenses.
Securing Funding Without Personal Guarantees

To secure funding without personal guarantees, trucking companies should focus on establishing a strong business credit profile. This can be achieved by:
- Establishing a Business Credit Profile: Registering with business credit bureaus and obtaining an Employer Identification Number (EIN) are essential steps.
- Utilizing Vendor Credit Lines: Building relationships with suppliers that offer credit can help establish a positive credit history.
How Does EIN Business Credit Separate Personal and Business Finances?
EIN business credit allows trucking companies to separate their personal and business finances effectively. By obtaining an EIN, businesses can establish their credit profiles independently of their owners. This separation protects personal assets and simplifies financial management, making it easier to track business expenses and income.
What Are the Benefits of Building Business Credit for Trucking Companies?
Building business credit offers several benefits for trucking companies, including:
- Separation of Finances: Establishing business credit helps maintain a clear distinction between personal and business finances.
- Access to Larger Funding Opportunities: Companies with strong credit profiles can qualify for larger loans and credit lines.
- Lower Interest Rates: A solid business credit history often results in lower interest rates on loans, reducing overall financing costs.
How Can Trucking Companies Obtain EIN Only Loans Without Personal Guarantees?
Trucking companies can obtain EIN-only loans without personal guarantees by following a structured approach. This includes:
- Researching Lenders: Identifying lenders that offer EIN-only loans is the first step in the process.
- Preparing Documentation: Companies must prepare the necessary documentation, including financial statements and business plans.
- Submitting Applications: Once the documentation is ready, companies can submit their applications to the selected lenders.
Eligibility Requirements
To qualify for EIN-only loans, trucking companies must meet specific eligibility requirements. These typically include having a strong business credit profile and demonstrating the ability to repay the loan. Lenders may also require documentation of business operations and revenue.
Application Process
The application process for EIN-only loans involves several steps. Companies should ensure they have all necessary documentation prepared, including financial statements and proof of revenue. Submitting a complete and accurate application increases the chances of approval.
Potential Lenders
Several lenders offer EIN-only loans for trucking companies. These may include:
- Online Lenders: Many online platforms specialize in providing loans to small businesses, including trucking companies.
- Credit Unions: Local credit unions often offer favorable terms for small business loans.
- Alternative Financing Companies: These companies may provide unique financing solutions tailored to the needs of trucking businesses.
The table below compares the main categories of EIN-only lenders available to trucking companies.
What Is an EIN Only Loan and How Does It Work?
An EIN-only loan is a type of financing that allows businesses to secure funding using their Employer Identification Number (EIN) instead of personal guarantees. This type of loan is designed for businesses that have established a strong credit profile and can demonstrate their ability to repay the loan. The process typically involves submitting an application along with necessary documentation, and approval is based on the business's creditworthiness.
For example, a trucking company that has registered its EIN, opened a dedicated business bank account, and built a year of on-time vendor trade lines can approach a lender with a credit profile that stands on its own. The lender reviews the business's payment history, revenue, and trade references rather than the owner's personal credit score or assets, which is what makes the loan "EIN-only." This structure matters most for growing fleets, since it means the company can take on additional financing to add trucks or cover fuel costs without putting the owner's house, savings, or personal credit on the line.
Which Lenders Offer No Personal Guarantee Business Loans for Trucking?
Several lenders provide no personal guarantee business loans specifically for trucking companies. These may include:
- Online Lenders: Many online lenders offer flexible financing options without requiring personal guarantees.
- Credit Unions: Local credit unions may provide favorable terms for small business loans without personal guarantees.
- Alternative Financing Companies: These companies often specialize in providing unique financing solutions tailored to the trucking industry.
What Are the Best Trucking Business Financing Options Without Personal Guarantees?
Trucking companies have several financing options available that do not require personal guarantees. Some of the best options include:
- **Credit Line Hybrid**: This type of financing combines features of credit lines and loans, providing flexibility for businesses.
- **Equipment Financing**: This allows companies to purchase or lease equipment without personal guarantees.
- Revenue Financing: This option provides funding based on future revenue projections, allowing businesses to access capital without personal liability.
How Do Commercial Truck Loans Without Personal Guarantee Compare?
Commercial truck loans without personal guarantees offer several advantages over traditional loans. These loans typically have lower interest rates and more flexible repayment terms. Additionally, they allow trucking companies to secure financing without risking personal assets, making them an attractive option for business owners.
What Role Do SBA Loans Play in Trucking Financing Without Personal Guarantees?
SBA loans play a significant role in trucking financing by providing favorable terms and conditions for small businesses. These loans often feature lower interest rates, longer repayment terms, and flexible uses. For trucking companies, SBA loans can be an excellent option for securing funding without personal guarantees, as they are backed by the government, reducing the risk for lenders. Trucking companies in the Washington D.C. metro area can review SBA loan options for the region to see current terms and eligibility.
How to Build Business Credit for Trucking Companies Step-by-Step?

Building business credit involves several key steps that trucking companies should follow:
- Establish a Legal Business Entity: Registering the business as a legal entity is the first step in building business credit.
- Open a Dedicated Business Bank Account: This helps separate personal and business finances, which is crucial for establishing credit.
- Register with Business Credit Bureaus: Ensuring the business is listed with major credit bureaus, such as Dun & Bradstreet, helps build a credit profile.
What Are the Key Steps to Establish Strong Business Credit Using EIN?
To establish strong business credit using an EIN, trucking companies should focus on the following steps:
- Obtain an EIN: This is essential for separating personal and business finances.
- Open a Business Bank Account: A dedicated account helps track business expenses and income.
- Establish Trade Lines: Building relationships with suppliers that offer credit can help establish a positive credit history.
How Can Trucking Companies Monitor and Improve Their Business Credit Scores?
Monitoring and improving business credit scores is essential for trucking companies. Companies should regularly check their credit reports for inaccuracies and ensure timely payments on all debts. Additionally, managing credit utilization effectively can help improve credit scores over time.
What Are Common Questions About Business Credit and EIN Only Loans for Trucking Companies?
Trucking companies often have questions regarding business credit and EIN-only loans. Common inquiries include:
- How long does it take to build business credit? Most trucking companies start seeing usable trade lines and a working credit profile within three to six months of consistent, on-time payments, though a fully mature profile with higher limits can take a year or longer to establish.
- What factors affect business credit scores? Payment history, credit utilization, the age and number of trade lines, and public records such as liens all play a part in determining a business credit score.
- Can I obtain funding without a personal guarantee? Yes. Trucking companies with an established EIN, a dedicated business bank account, and a solid trade credit history can qualify for vendor credit lines, EIN-only loans, and other financing that does not require a personal guarantee.
Addressing these questions can help trucking companies navigate the complexities of business credit and financing options effectively.
Trucking companies that want to dig deeper into these strategies can find additional guidance in our blog, browse common questions in our FAQs, or review our pricing for coaching and credit-building support.
For a closer look at qualifying criteria, visit our business credit page, or explore business loan options tailored to funding without personal guarantees. Trucking companies ready to move forward can consider VIP Business Funds as a partner in building a lender-ready credit profile.
About the Author
Lee Johnson is the Co-Founder and CEO of VIP Business Credit, a Sterling, Virginia–based finance enablement firm dedicated to helping entrepreneurs and small business owners build lender-ready business credit profiles and secure capital on the best possible terms.
With over 25 years of experience in business funding, credit building, and generational wealth strategies, Lee brings deep expertise to every client engagement. He holds a Bachelor of Science from Fairleigh Dickinson University and a Master of Business Administration from the University of Phoenix. He is also a Master Certified Coach with more than 500 coaching hours, and has built a personal real estate investment portfolio of over 1,700 units valued at approximately $254 million across multiple U.S. markets.
Lee's mission is to empower small business owners — including those in home services, trucking, and real estate — to achieve financial freedom by first establishing strong business credit, then accessing the highest loan amounts at the best terms available. He and his team serve business owners nationwide through VIP Business Credit's signature 12-month Fundability coaching program.
Connect with VIP Business Credit:
- 📞 Phone: +1 (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule a consultation to discuss your business credit goals
- 🌐 Website: vipbizfunds.com
- 🎯 FREE Business Funding Pre-Qualification Scan: Start your scan
VIP Business Credit proudly serves business owners in Sterling, VA and throughout the Greater Washington D.C. region.
Research & Sources
Research & Sources
- A.L. Riding, Loan Guarantees: Costs of Default and Benefits to Small Firms (2001): documents cases where lenders required a personal guarantee as a condition of extending credit to small businesses.
- J.N. Barrot, Trade Credit and Industry Dynamics: Evidence from Trucking Firms (2016): a difference-in-differences study of French trucking firms showing how financial shocks affect the trade credit suppliers extend to carriers.
- Factoring: The Law and Practice of Invoice Finance (2006): traces the growth of the factoring and invoice discounting industry as an increasingly mainstream financing tool.


