Business Loan Eligibility FAQs
Business Loan Eligibility FAQs
Qualification standards typically require a personal credit score of 670 or higher, $100,000+ in annual revenue, and one to two years in business. Lenders review tax returns, bank statements, and financial statements, sometimes requiring collateral or a personal guarantee. VIP Business Credit's Business Funding Pre-Qualification Scan identifies gaps against these criteria in minutes, with zero impact on personal credit.
Key Takeaways
- Most lenders require a personal credit score of 670 or higher to qualify for business financing.
- Businesses typically need $100,000 in annual revenue and one to two years operating history.
- SBA-guaranteed loans offer competitive rates, lower down payments, and flexible collateral requirements for qualified borrowers.
- VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders matching their eligibility profile.
What Are the Core Business Loan Requirements?
Core business loan requirements boil down to one question: does a lender see enough evidence that a business can repay what it borrows? According to Sunward's Business Loan Requirements Guide, applying for financing means meeting specific qualifications that lenders use to assess risk before approving an application. Business owners who understand this framework in advance submit stronger applications and face fewer surprises during underwriting.
Lenders assess risk differently depending on loan type and lender category. Most look at a similar core set of factors. These loan requirements typically include:
- Time in business and revenue history
- Personal and business credit standing
- Collateral or personal guarantee availability
- Industry risk and cash flow consistency
A broad lender network matters here. VIP Business Credit connects clients to a wide range of lending sources, matching financing strategy to a business's stage, sector, and risk profile rather than forcing every applicant into one mold.
How does loan structure affect qualification?
Many business owners don't realize that loan structure itself shapes eligibility. VIP Business Credit's core focus centers on helping clients secure high-limit credit lines tied to the company's EIN rather than the owner's Social Security number. This separation protects personal liability while building a credit profile lenders can evaluate on business merit alone.
Do requirements change for newer businesses versus established ones?
Yes, significantly. A newer venture usually needs to prove it is ready to qualify in the first place. An established firm pursuing expansion or consolidation faces different underwriting questions. VIP Business Credit's approach supports both situations, guiding startups toward first approvals and helping mature businesses access better-priced capital for scaling. Knowing which category applies helps owners prepare the right documentation before approaching any lender.
How Does Your Personal Credit Score Matter?
A personal credit score shapes nearly every lender's first review of a small business loan application. Most loan requirements call for a score of 670 or higher, according to Business Loan Requirements: What You Need to Qualify (published Jul 17, 2026), alongside annual revenue above $100,000 and one to two years of operating history. That threshold explains why many of the most common qualification questions business owners face center on personal credit history before the conversation ever reaches cash flow or collateral. Lenders treat this number as a proxy for financial discipline, and a thin or damaged credit file signals risk even when the business itself performs well.
Building credit under the company's own EIN, rather than relying solely on the owner's Social Security number, gradually shifts that weight. As a business establishes its own credit identity, personal credit carries less influence on approval decisions over time, and liability separates more clearly between owner and company.
Can a business owner improve approval odds without fixing personal credit first?
Yes, to a degree. Strengthening business credit in parallel reduces dependence on the owner's personal score, though most lenders still review both early on. A structured, comprehensive credit-building program addresses this gap directly, pairing education with coaching. Owners understand underwriting criteria rather than guessing at it.
Local advisors supplement that education with concierge-level guidance, reviewing a business's credit position and recommending next steps before an application goes out. Common topics covered include:
- How personal and business credit scores interact during underwriting
- Which eligibility FAQs lenders raise most often during review
- Practical steps for building a credit profile tied to the business itself, not the owner
Working through these questions early prevents denials that cost time and momentum later.
What Revenue and Time-in-Business Benchmarks Apply?
No single revenue figure or age-of-business cutoff applies across every lender. Instead, underwriters generally look for businesses that meet established size standards, show a clear ability to repay, and operate with a sound business purpose. These three factors shape most loan requirements, regardless of lender type.
Size standards exist to confirm a business fits the scale a given loan program targets. A lender funding microloans expects a different profile than one writing large working-capital lines. Repayment ability matters just as much. Lenders want evidence that cash flow can comfortably cover new debt on top of existing obligations.
Does a Newer Business Qualify for Funding?
Yes, a newer venture can still qualify, though the path looks different than it does for an established firm. VIP Business Credit's approach supports both groups by matching financing strategies to a business's particular stage, sector, and risk profile. A startup with limited history may be guided toward programs built for early-stage eligibility FAQs. A company with years of revenue gets matched to products suited to scale.
What If My Business Doesn't Fit Standard Benchmarks?
Not fitting one lender's benchmarks doesn't rule out financing altogether. Common qualification questions around revenue thresholds and time in business often have more than one answer, since requirements shift by lender and program. This is where lender variety matters most: VIP Business Credit connects clients to a network of more than 1,000 national and local lenders, covering a range of loan programs built for different stages and risk levels. That breadth means a business falling short of one lender's benchmark may still fit comfortably within another's criteria, so rather than treating one rejection as final, business owners gain the chance to find the specific program built for where their company stands today.
Which Documents Do Lenders Require for Approval?
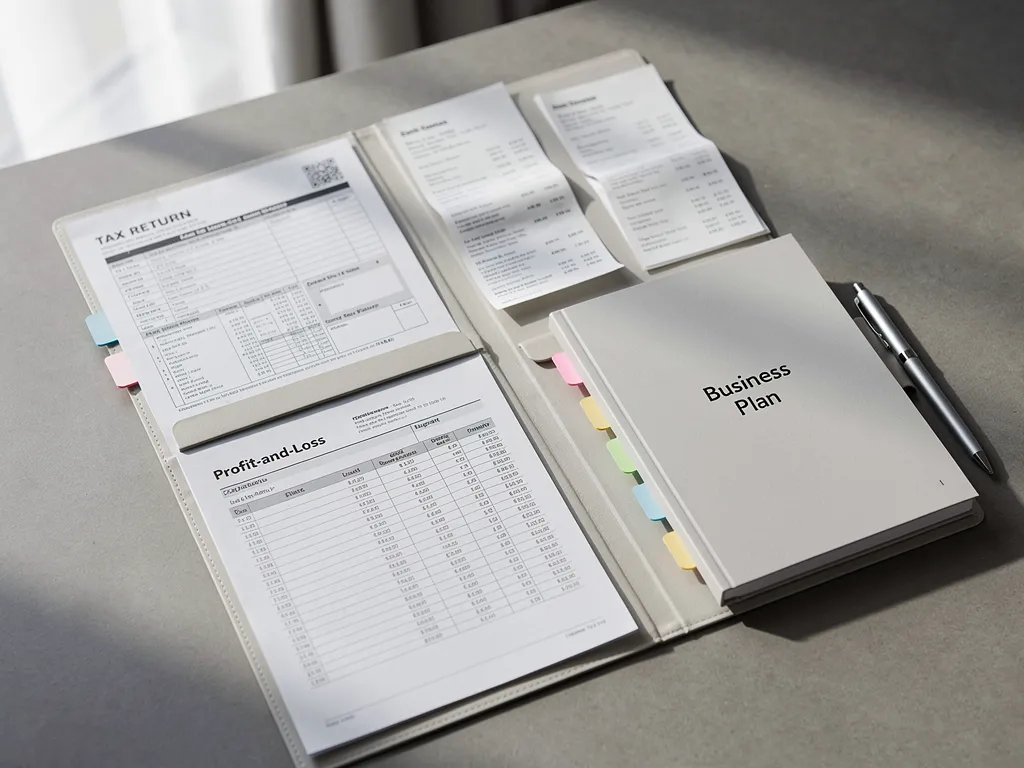
Lenders require a defined paperwork package before releasing capital. Business Loan Requirements: What You Need to Qualify, published Jul 17, 2026, confirms that most applications call for tax returns, bank statements, financial statements, and a written business plan. Missing or disorganized paperwork slows underwriting and can push a growing company past the window it needed capital for.
A typical document checklist includes:
- Business and personal tax returns from recent fiscal years
- Bank statements showing cash flow and deposit history
- Financial statements, including profit-and-loss reports and balance sheets
- A business plan outlining revenue strategy and growth projections
These items answer most of the standard loan requirements reviewers check first. Reviewers use them to confirm revenue stability, not just to check a box.
Do All Lenders Ask for Collateral?
Not every lender does, but many add conditions beyond the core paperwork. Some require collateral, a personal guarantee, or both, before finalizing approval. Business owners should treat these as part of the broader set of qualification questions a lender poses, not as separate hurdles. Reviewing them early avoids surprises during final underwriting.
How Can Business Owners Prepare Their Documentation?
Preparation starts with consistency. VIP Business Credit helps clients strengthen the foundational credibility signals, like matching business identity data across filings and active trade credit reporting, that support a smoother document review. Lenders cross-check these details against submitted statements, so inconsistencies raise red flags before a file ever reaches a decision-maker.
Education matters just as much as paperwork. VIP Business Credit's credit-building program includes coaching that helps owners organize their records and understand how underwriters evaluate submitted files. Clients working through common eligibility FAQs gain a clearer sense of which documents carry the most weight. Why thorough preparation shortens the path from application to funded account.
Are SBA Loans Right for Your Business?
SBA loans suit business owners who want government-backed terms without the steep costs often attached to alternative financing. Rates and fees on SBA-guaranteed loans generally run comparable to non-guaranteed loan products. Businesses aren't paying a premium for the backing. That makes these programs worth a serious look for owners weighing their options.
Several SBA programs sweeten the deal further. Some offer lower down payments, flexible overhead requirements, and no collateral requirement at all. For a business with limited assets to pledge, that last point can be the difference between approval and rejection.
What Makes SBA Loans Different From Other Financing?
The backing structure changes the risk calculation for lenders, not the application process itself. Because the government guarantees a portion of the loan, lenders can extend more favorable terms than they might otherwise offer, including the lower down payments and reduced collateral requirements noted above. This explains why down payment requirements and collateral rules stay flexible on certain SBA products: the lender is carrying less exposure, so it can afford to ask for less upfront from the borrower. Business owners weighing SBA financing against other options should factor this trade-off into the comparison, since the paperwork and approval timeline for SBA programs can run longer than some alternative lenders require.
How Does an Advisor Help With SBA Loan Decisions?
A qualification questions session with a business credit advisor identifies whether an SBA loan or an alternative product fits better. VIP Business Credit's lender network spans traditional banks, alternative finance providers, and specialized programs, which can include SBA-type options among the mix. Access to this network means an SBA loan gets compared against other paths before a client commits.
Connecting to over 1,000 national and local lenders widens that comparison even further. Instead of evaluating one SBA program in isolation, owners see how it stacks up against other loan requirements and structures. Reviewing common eligibility FAQs alongside this broader lender pool helps business owners make a confident, well-informed choice rather than settling for the first offer that comes through the door.
SBA Loans vs. Alternative Financing
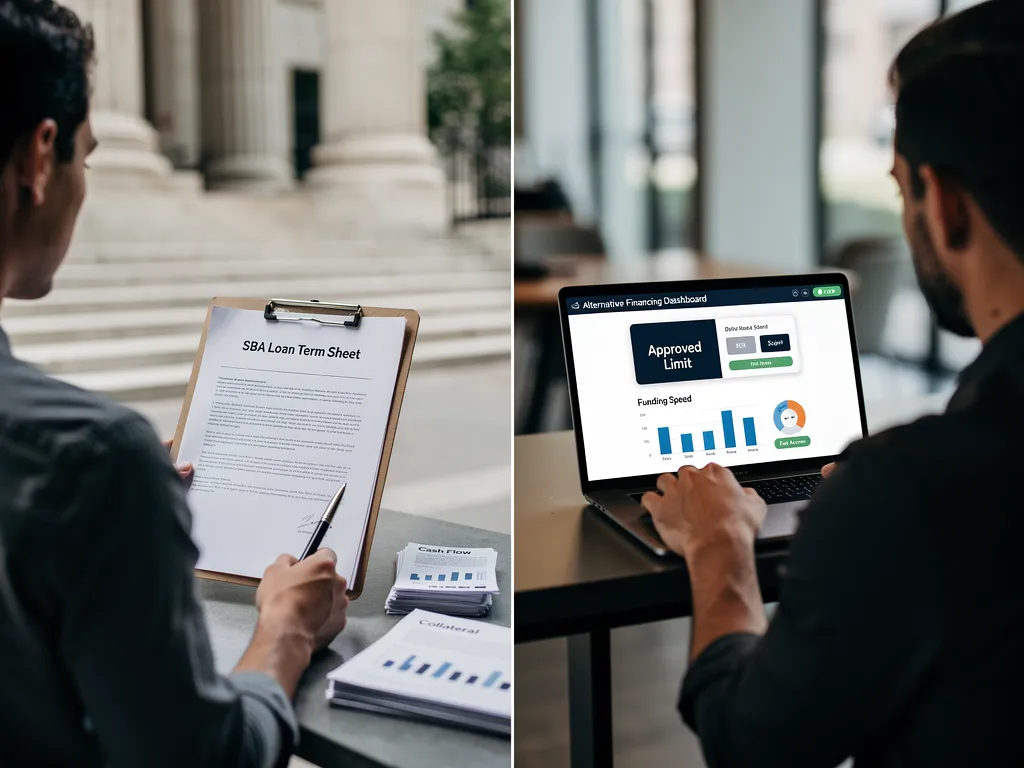
The trade-offs between SBA-guaranteed loans and alternative financing come down to cost, speed, and collateral flexibility:
Do All Lenders Use the Same Criteria?
Lenders do not share one standard playbook for approving business loans. Evaluation criteria shift based on the lender type and the stage of the business applying, according to Sunward's Business Loan Requirements Guide. A startup seeking its first credit line faces a different review than an established company refinancing equipment debt.
This variation explains why many qualification questions sound inconsistent from one lender to the next. A bank may weigh collateral heavily. An alternative finance provider may focus more on monthly cash flow. Neither approach is wrong; they reflect different risk models.
Why does loan criteria differ by lender type?
Banks and credit unions typically prioritize established financials, collateral, and a proven track record. Alternative lenders and specialized programs often accept thinner credit files in exchange for faster underwriting or industry-specific terms. Matching a business to the right lender category, rather than applying to every option blindly, saves time and protects credit inquiries.
VIP Business Credit's local Business Credit Advisors exist specifically to navigate these differences. Rather than leaving owners to guess which loan requirements apply to their situation, advisors deliver personalized, concierge-level guidance tied to each business's profile. That guidance draws on a broad lender network spanning traditional banks, alternative finance providers, and specialized programs. A strategy built for a five-year-old manufacturing firm looks nothing like one built for a two-year-old service business.
Does business age change what lenders look for?
Yes. Newer ventures often need options built around limited operating history, while established firms pursuing expansion or consolidation benefit from better-priced capital tied to stronger financials. VIP Business Credit structures its approach around both situations, recognizing that lender priorities move as a business matures.
Owners who understand this variation can approach eligibility FAQs with more confidence. Instead of assuming rejection from one lender means disqualification everywhere, they can recognize a mismatch in criteria and pursue a better-fit option.
How Can You Strengthen Your Qualification Profile?
Strengthening a qualification profile starts with separating business and personal finances. Building credit tied to the business's EIN, rather than the owner's Social Security number, draws a clear line between personal and business liability. This separation protects personal assets while giving the business its own credit identity in the eyes of lenders.
A stronger profile also depends on knowing where gaps exist before an application goes out. Understanding a lender's requirements in advance sets an application up for success. Underwriters reject incomplete or mismatched submissions far more often than well-prepared ones. A pre-qualification review helps owners see which funding programs they already qualify for and which ones need more groundwork first.
What steps actually move the needle on qualification?
Three practices consistently strengthen how lenders and vendors view a business:
- Align business identity data across registrations, bank records, and credit bureau files so nothing contradicts itself.
- Report trade credit consistently, since steady reporting history signals lower risk to lenders and card issuers.
- Review pre-qualification results before submitting formal applications, to avoid wasted inquiries on mismatched programs.
Why does identity consistency matter so much?
Lenders cross-check business name, address, and ownership details against multiple databases during underwriting, including credit bureau files, state registration records, and bank account information. Mismatched or outdated information raises red flags, even when the underlying business is financially sound, because an underwriter reading conflicting data has no easy way to tell whether it signals a clerical error or something more serious. Keeping these records consistent removes friction that has nothing to do with actual creditworthiness, letting the application move forward on the strength of the business's real financial position instead of stalling over paperwork details.
Taken together, these steps build a more complete and defensible application. Loan requirements become easier to meet when the underlying credit file is clean and consistent. Owners who treat qualification as an ongoing practice, rather than a one-time task before applying, tend to face fewer surprises during underwriting and move through the funding process with greater confidence.
What Should You Do Before You Apply?
Preparation separates a strong application from a rejected one. Business owners gain the most ground by organizing financial records, clarifying their funding purpose, and lining up guidance before submitting anything to a lender. Skipping this step often leads to delays, denials, or financing that doesn't actually fit the business.
Each business carries its own mix of revenue patterns, industry risk, and growth stage. Because of that, generic checklists rarely answer every owner's qualification questions completely. Specific concerns about eligibility are best resolved with guidance tailored to that business's actual numbers and history, rather than one-size-fits-all advice.
Why does working with the right lender matter?
Not every lender serves every business well. Securing financing that actually sustains operations, whether revenue is strong or slowing, depends on partnering with a lender who understands the business's size, industry, and specific lending needs. A bank unfamiliar with a company's sector may misjudge risk or offer products that don't match its cash flow.
What should a business confirm before submitting an application?
Before applying, owners should review a short set of readiness items:
- Current revenue trends and cash flow stability
- Documentation that supports the business's financial history
- Clear goals for how the funds will be used
- A relationship with an advisor who can answer loan requirements questions specific to the business
VIP Business Credit approaches this groundwork as a long-term partnership, not a one-time transaction. The firm's pricing stays transparent, with no hidden surprises buried in the fine print. Though rooted in Northern Virginia, VIP Business Credit serves clients digitally and connects them to lenders nationwide, giving business owners eligibility FAQs answered by someone invested in their actual outcome, not just the next closed deal.
FAQ
What credit score do I need to qualify for a business loan?
Most lenders require a personal credit score of 670 or higher to qualify for business financing. VIP Business Credit's Business Funding Pre-Qualification Scan identifies gaps against this criteria in minutes, with zero impact on personal credit.
How much revenue and time in business do lenders expect?
Lenders typically expect $100,000 or more in annual revenue and one to two years of operating history. They also review tax returns, bank statements, and financial statements during underwriting.
How does VIP Business Credit help me find the right lender?
VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders, matching financing strategy to a business's stage, sector, and risk profile.
Conclusion
In closing, understanding your business loan eligibility requirements empowers you to approach lenders with confidence and clarity. By addressing foundational elements, your business structure, financial documentation, credit profile, and operational history, you position your company as a credible borrowing partner. The path to securing capital becomes less daunting when you know exactly what lenders evaluate and how to strengthen each area. Take time to assess your current standing, identify gaps, and build the credibility signals that matter most. Your business's growth depends on access to the right capital at the right time. That access begins with meeting the standards lenders use to evaluate risk.
Serving the DC Metro Area
VIP Business Credit is rooted in Northern Virginia and works with business owners across the region, while also serving clients digitally and connecting them to lenders nationwide. Business owners in the following areas can find local guidance on eligibility and qualification:
- Business credit Sterling VA
- Business loans Ashburn VA
- Business funding Tysons VA
- Business credit Reston VA
- Working capital Arlington VA
- Business loans Fairfax County VA
- Business funding DC metro
Contact
- 📞 Phone: +1 (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule a Consultation
- 🌐 Website: vipbizfunds.com
- 🎯 FREE Business Funding Pre-Qualification Scan: Start Your Scan
Serving Sterling, VA and surrounding areas.
About The Author
Lee Johnson is the Co-Founder & CEO of VIP Business Credit and a Master Certified Professional Coach with over 500 coaching hours and 25+ years of experience in business funding, credit building, and generational wealth strategies. He holds a Bachelor of Science from Fairleigh Dickinson University and an MBA from the University of Phoenix. Lee has also built a personal real estate investment portfolio exceeding 1,700 units valued at approximately $254 million across multiple U.S. markets.
Lee's mission is to help small business owners, including those in home services, trucking, and real estate, achieve financial freedom by first establishing a strong business credit profile, then accessing the highest loan amounts at the best terms available.
Frequently Asked Questions
What credit score do I need to qualify for a business loan?
Most lenders require a personal credit score of 670 or higher to qualify for business financing. VIP Business Credit's Business Funding Pre-Qualification Scan identifies gaps against this criteria in minutes, with zero impact on personal credit.
How much revenue and time in business do lenders expect?
Lenders typically expect $100,000 or more in annual revenue and one to two years of operating history. They also review tax returns, bank statements, and financial statements during underwriting.
How does VIP Business Credit help me find the right lender?
VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders, matching financing strategy to a business's stage, sector, and risk profile.
Do all lenders require collateral for a business loan?
No. Some lenders approve financing without collateral, while others require it, a personal guarantee, or both before finalizing approval. Several SBA programs, for example, offer no collateral requirement at all. Reviewing a lender's conditions early avoids surprises during final underwriting.
Does a business's age affect its loan qualification?
Yes. Newer businesses are often guided toward programs built for limited operating history, while established firms pursuing expansion or consolidation typically qualify for better-priced capital tied to stronger financials. VIP Business Credit matches financing strategy to each stage.


