How a Business Credit Advisor Unlocks Funding
How a Business Credit Advisor Unlocks Funding
By VIP Business Credit Editorial Team · Updated 2026-09-07
Personalized business credit advisors at VIP Business Credit deliver expert guidance through local Business Credit Advisors paired with a proprietary readiness platform, which includes a Capital-Ready Score, Funding Explorer, and Bureau Insights. This concierge approach connects small business owners to business credit, closing credit gaps and matching each business with funding options suited to its stage and risk profile.
Key Takeaways
- VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders for funding opportunities.
- Our proprietary Capital-Ready Score tool evaluates your business credit readiness and funding potential accurately.
- We serve Northern Virginia and Greater Washington, DC entrepreneurs building EIN-based business credit strategically.
- Professional credit coaching from our Sterling, VA team supports your business's funding readiness and financial growth.
What Does a Business Credit Advisor Actually Do?
A business credit advisor guides a company through the funding process from start to finish, from diagnosing credit gaps to matching the business with lenders suited to its stage and risk profile. At VIP Business Credit, that guidance comes from local, named advisors who work directly with clients rather than routing calls through an anonymous support queue. Business owners speak with the same person across their funding journey, not a rotating cast of representatives.
This kind of advisory work stays close-knit. VIP Business Credit runs as a small, focused team of 3 employees, a structure that keeps the experience personal instead of impersonal. Owners get direct access to expertise instead of getting lost in a corporate call center's phone tree.
Is a Business Credit Advisor the Same as a Broker?
No. A broker typically closes one transaction and moves on. VIP Business Credit positions itself as a long-term partner, offering transparent, no-surprise pricing instead of the hidden fees that often come with one-time transactional deals. That distinction matters for entrepreneurs who need ongoing capital as their business grows, not just a single loan approval.
How Involved Is a Credit Coaching Consultant Day to Day?
A credit coaching consultant stays reachable throughout the funding process, not just at the point of sale. Clients can contact the advisor team by phone or email whenever questions arise, whether that's mid-application or months after funding closes.
This ongoing access separates real advisory support from a transactional sales pitch. Business owners get business funding guidance built around their specific circumstances, delivered by people who know their file and their goals. The result is a working relationship that adapts as the company's credit needs change, rather than a single interaction that ends once the paperwork is signed.
Why Separate Business and Personal Credit?
Separating business and personal credit shields a founder's Social Security number from company debt while building a credit file tied strictly to the business's EIN. Mixing the two turns everyday business risk into personal risk—one missed vendor payment or slow sales quarter can suddenly threaten a home, savings, or personal credit score. That exposure is the core problem this separation solves.
A business credit advisor works with owners to build financing profiles under the company's EIN instead of a personal SSN, opening access to high-limit loans and revolving credit lines without putting personal assets on the line. This matters especially for entrepreneurs across Northern Virginia and the Greater Washington, DC region. Local guidance helps small firms establish EIN-based credit from the ground up rather than relying on the owner's personal history.
Does an EIN Really Replace a Business Owner's SSN?
Not entirely, but a strong EIN-based file reduces how often a lender pulls personal credit. Financing strategies get matched to a business's stage, sector, and risk profile. A five-year-old retail company and a two-year-old contracting firm won't be steered toward the same products.
Cash flow trouble makes this urgency concrete. Data cited by Business Credit indicates that lack of cash flow sinks around 80% of startups. A business carrying no separate credit identity has fewer cushions to fall back on when revenue stalls.
A credit coaching consultant and ongoing business funding guidance help close that gap by building the separation early. A cash crunch forces owners to choose between:
- Paying business debt personally
- Defaulting and damaging personal credit
- Running out of working capital entirely
Early separation, tied clearly to VIP Business Credit's process at vipbizfunds.com, keeps that choice off the table.
How Does Credit Coaching Build a Stronger Profile?
Credit coaching strengthens a business profile by translating underwriting criteria into concrete, sequenced actions. A credit coaching consultant reviews how lenders actually see a company's funding readiness. Financial position, then closes the gaps that keep applications stuck in review. That review process, not guesswork, is what separates a fundable business from one that keeps collecting declines.
The work starts with identity, not credit lines. Applying for a DUNS number — the identifier many commercial lenders and vendors use to track a business separately from its owner — is often the first coached step. Establishing this number early gives a company an independent credit profile before it ever applies for financing.
What does a structured credit-builder process actually involve?
A structured process guides owners through establishing and managing business credit history in stages, rather than all at once. Early steps typically include:
- Setting up trade lines that report to business credit bureaus
- Sequencing applications so early approvals support later ones
- Monitoring how usage and payment history shape the profile over time
Skipping this order is a common reason businesses get denied for credit they were otherwise ready to carry.
Why does coaching work better than a generic template?
Coaching works because it adapts to the business, not the other way around. A local business credit advisor delivers concierge-level guidance tied to the company's actual financials, industry, and timeline. Templates assume every business looks the same. A coach recognizes when a retail operation needs different documentation than a contracting firm.
That personalized layer is where real business funding guidance earns its value. Owners get a specific roadmap instead of a checklist, and they get someone reviewing the results as the profile builds. Catching problems before a lender does.
What Tools Reveal Your Funding Readiness?
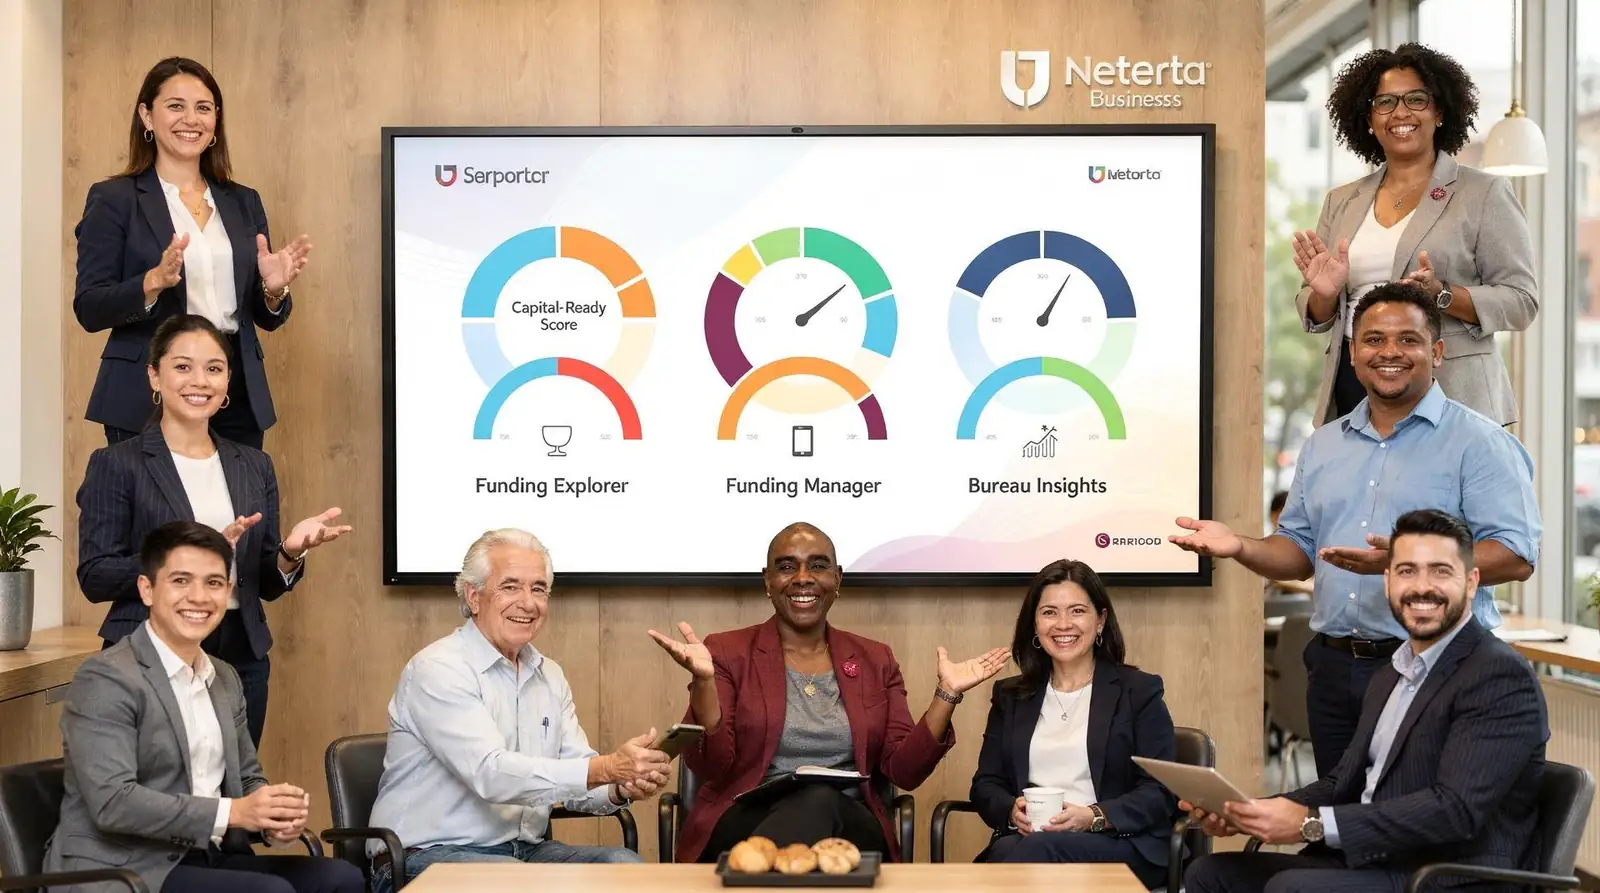
Four connected tools reveal how ready a business is for financing: a Capital-Ready Score, a Funding Explorer, a Funding Manager, and Bureau Insights. Together, the tools show business owners how underwriters actually view the company, revealing blind spots that owners often miss on their own. Guessing at eligibility wastes time and can trigger a hard credit inquiry that leads nowhere.
This four-part system, offered through VIP Business Credit's platform at vipbizfunds.com, supports a clear, step-by-step process. Each stage is designed to improve a company's readiness so it can qualify for better terms, higher credit limits, and lower rates. A business credit advisor typically walks owners through the results, translating raw numbers into a workable plan.
How does the pre-qualification process work?
A pre-qualification workflow sorts financing programs into two groups: those a business qualifies for right now, and those that need more preparation first. Owners see exactly which gaps stand between them. Approval, instead of discovering those gaps only after a denial letter arrives.
Can these tools match a business to the right lender?
Lender matching features identify realistic funding options based on a company's current profile. Instead of applying to every lender available, an owner applies where approval odds run strongest. A credit coaching consultant reviews those matches and explains the reasoning behind each recommendation.
This combination of scoring, matching, and tracking forms the backbone of sound business funding guidance. Owners who use it stop guessing and start applying with a real strategy behind every submission.
How Many Lenders Should You Have Access To?
More lender access means more chances at approval, better rates, and terms that fit a specific business stage. VIP Business Credit connects clients to a network of more than 1,000 national. Local lenders, a range far wider than what a single bank relationship offers. A business owner working with only one or two banks sees a narrow slice of what's actually available.
That network spans traditional banks, alternative finance providers, and specialized programs. It's not a short list of preferred partners recycled for every applicant. Different lenders weigh revenue, time in business, and industry risk differently, so breadth matters as much as the total count.
Why does lender variety matter more than lender quantity?
Variety solves a matching problem, not just a numbers problem. A startup six months old needs different lending programs than a manufacturer with a decade of revenue history. This wide lender access serves both newer ventures seeking their first approvals and established firms looking to scale. The right fit depends on where a business actually stands.
Working with a business credit advisor helps translate that lender map into a workable plan. A credit coaching consultant reviews where a file stands today and what gaps block approval tomorrow. That combination of broad access and personalized business funding guidance is anchored locally too. VIP Business Credit's office sits at 21000 Southbank St Ste 106-380, Sterling VA 20165, grounding the advisory relationship in a real, reachable place rather than a call center script.
What Does Business Funding Guidance Look Like?
Practical business funding guidance looks like a structured mix of products and coaching, not a single loan application. Small business owners typically work through business loans, revolving lines of credit, and a full credit-building program designed to establish the company's profile under its own EIN. Underwriting education runs alongside every product, so owners understand why a lender approves one file and declines another.
A business credit advisor does more than match a business to a lender. Financing arrangement is only part of the job. Strengthening credibility signals matters just as much: keeping business identity data consistent across registrations and directories, and ensuring trade credit activity reports correctly to the bureaus lenders check. Sloppy or mismatched business records raise red flags long before a lender reviews revenue numbers.
Some guidance paths include 0% introductory business credit cards, which give owners breathing room to cover marketing pushes, payroll cycles, or inventory purchases without immediate interest costs. These cards work best as a bridge, not a permanent solution.
How does a credit coaching consultant help beyond approval?
A credit coaching consultant teaches owners to manage, leverage, and recycle credit lines so the benefit outlasts the first approval. Recycling means paying down balances strategically and reopening capacity for the next growth push, rather than letting a line sit maxed out.
What products fall under a typical funding plan?
Owners who follow this layered approach — financing paired with credibility repair and ongoing coaching — build a profile that qualifies for stronger terms each time they return to the market.
How Do You Avoid Common Credit Mistakes?
Avoiding credit mistakes starts with preparation, not luck. Most rejections trace back to two preventable gaps: missing documentation and a mismatched financing request. Small to midsize business owners who close those gaps before applying see far fewer denials.
A written business plan is the first safeguard. The U.S. Small Business Administration notes that business plans help owners secure funding and attract new partners. A clear plan convinces lenders that working with a company is a sound decision. Skipping this step is one of the most common — and most avoidable — mistakes an owner can make.
Why do lenders reject strong-looking applications?
Lenders and investors need confidence they will see a return before they extend credit. Incomplete documentation, vague revenue projections, or missing financial statements erode that confidence quickly. A business credit advisor reviews these materials in advance, catching gaps a business owner might not know to look for.
Does location limit access to credit guidance?
Support rooted in Northern Virginia and Loudoun County reaches clients well beyond that region, since guidance is delivered digitally. Geography should never be the reason a business owner goes without expert business funding guidance.
Matching the financing request to the business's actual stage prevents another frequent error. A newer venture chasing a scaling-stage credit line will likely be declined. An established firm settling for starter-level products leaves better terms on the table. A credit coaching consultant helps identify which stage a business is in and which products fit it.
Common mistakes to watch for:
- Applying without a documented business plan
- Submitting incomplete financial records
- Requesting products built for a different business stage
- Assuming location restricts access to expert guidance
Correcting these four issues before submitting an application meaningfully reduces avoidable denials and protects the owner's time.
What's the Roadmap to Get Started Today?
Getting started begins with an honest look at where a company's credit profile stands today, not with applying for the biggest loan available. VIP Business Credit, found online at vipbizfunds.com, builds its process around that starting point, then layers in lender access, purpose-built software, and guided execution so owners move through a complex funding marketplace without putting personal assets at risk.
The philosophy driving this roadmap is simple: build the business credit profile first, then chase the highest loan amounts at the best terms. Skipping that first step often costs owners better rates later. A rushed application can lock a business into weaker terms for years.
What are the actual steps?
The path typically follows this sequence:
- Assess the current credit profile — identify gaps a lender would flag immediately.
- Work with a business credit advisor to map which funding products fit the business today versus later.
- Build a business plan that functions as a roadmap through every stage of the company, since a solid plan guides funding decisions as much as day-to-day operations.
- Strengthen credit fundamentals before applying for larger credit lines.
- Apply strategically, once the profile supports stronger terms.
Who provides support along the way?
A credit coaching consultant stays available throughout this process, not just at signup. Ongoing access to the advisor team by phone or email means owners get business funding guidance exactly when a question comes up, whether that's mid-application or months into managing a new credit line. This continuity is what separates a real roadmap from a one-time transaction.
Owners who follow this order — profile first, funding second — put themselves in a stronger position to negotiate terms rather than accept whatever a lender offers first.
FAQ
What does a business credit advisor do?
A business credit advisor diagnoses credit gaps and matches a business with lenders suited to its stage and risk profile. VIP Business Credit's local advisors guide clients directly through the entire funding journey, from start to finish.
How does VIP Business Credit differ from a broker?
VIP Business Credit acts as a long-term partner rather than closing a single transaction. The company offers transparent, no-surprise pricing and stays involved as an entrepreneur's credit needs evolve over time.
Why build credit under an EIN instead of personal credit?
Building credit under the business's EIN separates company debt from a founder's Social Security number, protecting personal assets. This approach opens access to high-limit loans and revolving credit lines without personal exposure.
Conclusion
In closing, building business credit with personalized guidance transforms how lenders evaluate your company. A dedicated Business Credit Advisor walks you through each step—from understanding your Capital-Ready Score to executing strategies that strengthen your profile across the bureaus lenders use. This hands-on partnership, paired with access to over 1,000 lending options, removes the guesswork from funding decisions. You move forward with clarity, confidence, and a clear roadmap to sustainable growth rooted in genuine business creditworthiness.


