Fintech Business Loans: Fast Funding Solutions
Fintech Business Loans: Fast Funding Solutions
Fintech business loans deliver fast, technology-driven funding through streamlined online applications rather than traditional bank underwriting. VIP Business Credit's Business Credit Scan matches business owners to pre-qualified funding options in 2-6 minutes, with zero impact on personal credit, connecting entrepreneurs to over 1,000 lending options nationwide for rapid working capital.
Key Takeaways
- VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders for fast funding solutions.
- Fintech business loans eliminate lengthy traditional bank applications, offering streamlined approval timelines for qualified businesses.
- Small business loan applicants with 6+ months operating history and $15,000+ monthly revenue qualify for modern financing options.
What Are Fintech Business Loans and Why Do They Matter?
Fintech business loans pair financial services with modern technology to speed up how companies access working capital. This shift matters because the old lending path often costs small business owners more than money — it costs them time they cannot spare. Slow approvals mean missed inventory buys, stalled payroll, and lost contracts that never come back around.
Traditional bank loans typically demand lengthy applications, strict credit requirements, and approval timelines that stretch for weeks. Many small businesses cannot afford that wait. A supplier discount that expires in five days does not pause for a loan committee.
Online commercial lending platforms close that gap through automation, data-driven underwriting, and streamlined document review. Instead of a single bank deciding yes or no, digital lenders and marketplaces evaluate a business's real-time financial picture and respond in a fraction of the time.
Why Does Speed Matter So Much for Small Business Funding?
Cash flow gaps do not wait for paperwork. A missed payroll cycle or an unfilled purchase order can stall growth or damage vendor relationships within days, not months. Faster approval turns a funding decision into a business advantage rather than a bottleneck.
How Does VIP Business Credit Fit Into This Picture?
VIP Business Credit, based in Sterling, Virginia, helps entrepreneurs secure capital through digital business financing strategies matched to their stage and sector. The firm connects business owners to more than 1,000 national and local lenders, spanning traditional banks and alternative finance providers alike.
That breadth matters because no single lender fits every business. A retail startup and an established logistics company need different underwriting criteria, different terms, and different speeds. Access to a wide lender network means owners spend less time guessing and more time building.
How Does Online Commercial Lending Actually Work?
Digital lending platforms replace paper-heavy bank underwriting with automated review systems built for speed. Online commercial lending connects a business directly to a marketplace of funders through a single digital application, rather than forcing an owner to visit branch after branch. Approval decisions that once took weeks now happen much faster. The underlying technology reads bank data and business performance instead of waiting on manual file review.
That speed comes from a deliberate design choice. Digital-first platforms exist to deliver faster approvals, more flexible funding structures, and a smoother borrowing experience than traditional banks typically offer. Some lenders have trimmed the entire process down to a short application paired with a handful of months of business bank statements, cutting out the stacks of documentation older lending models required.
What Does a Typical Online Application Require?
Most fintech business loans start with basic business details, revenue history, and recent bank statements. Underwriting software then cross-checks that information against risk models built for speed rather than paperwork volume. Owners generally see a decision or a term sheet well before a traditional bank would finish its initial file review.
How Can a Business Owner Prepare Before Applying?
A business credit scan gives owners a clear picture of where their company stands with lenders before they submit anything. This kind of review surfaces credit gaps and outlines a roadmap for building a stronger credit profile ahead of an application.
Preparation typically includes:
- Reviewing business bank statements for consistency and cash flow strength
- Checking that business credit files reflect accurate, matching identity data
- Understanding which lending categories fit the business's stage and revenue
Digital business financing works best when paired with guidance. VIP Business Credit connects clients to a broad network of national and local lenders across multiple categories, matching each business to funding suited to its specific risk profile and growth stage. Schedule a free consultation to map out the right fit before applying.
What Makes Digital Business Financing Faster Than Bank Loans?
Speed comes down to automated underwriting instead of manual paperwork review. Fintech business loans rely on software that pulls bank statements, revenue data, and credit history in minutes rather than weeks. Traditional bank loans still depend on loan officers manually reviewing files, scheduling meetings, and routing applications through committees. That difference in process, not just technology, explains the gap in turnaround time.
Some online lenders offer significantly faster approval timelines than traditional banks, reflecting broader trends across the online commercial lending industry. That leaves owners free to run daily operations instead of sitting by the phone waiting for a decision. Other online commercial lending platforms move even quicker, often turning around approval decisions within the same business day.
Why Do Same-Day Approval Rates Run So High?
Same-day funding models often post approval rates far above what conventional banks report. Platform Funding's site cites a 95 percent approval rate across most industries served, a result of streamlined, data-driven review rather than rigid checklist underwriting. Automated systems evaluate real business performance instead of relying solely on credit scores.
How Does Preparation Speed Up Digital Financing Approval?
Preparation still matters, even with fast digital business financing. VIP Business Credit walks companies through a step-by-step process that strengthens capital readiness before an application ever goes out. This groundwork helps owners qualify for:
- Better repayment terms
- Higher credit limits
- Lower interest rates
VIP Business Credit's platform tools show owners how underwriters actually view their business, well before submission. Run the free business credit scan to spot weak points early, which means fewer rejections and faster funding once the application is filed. Preparation and automation work together, and that combination is what separates a same-day approval from a monthslong bank process.
Which Fintech Loan Types Fit Your Business Needs?
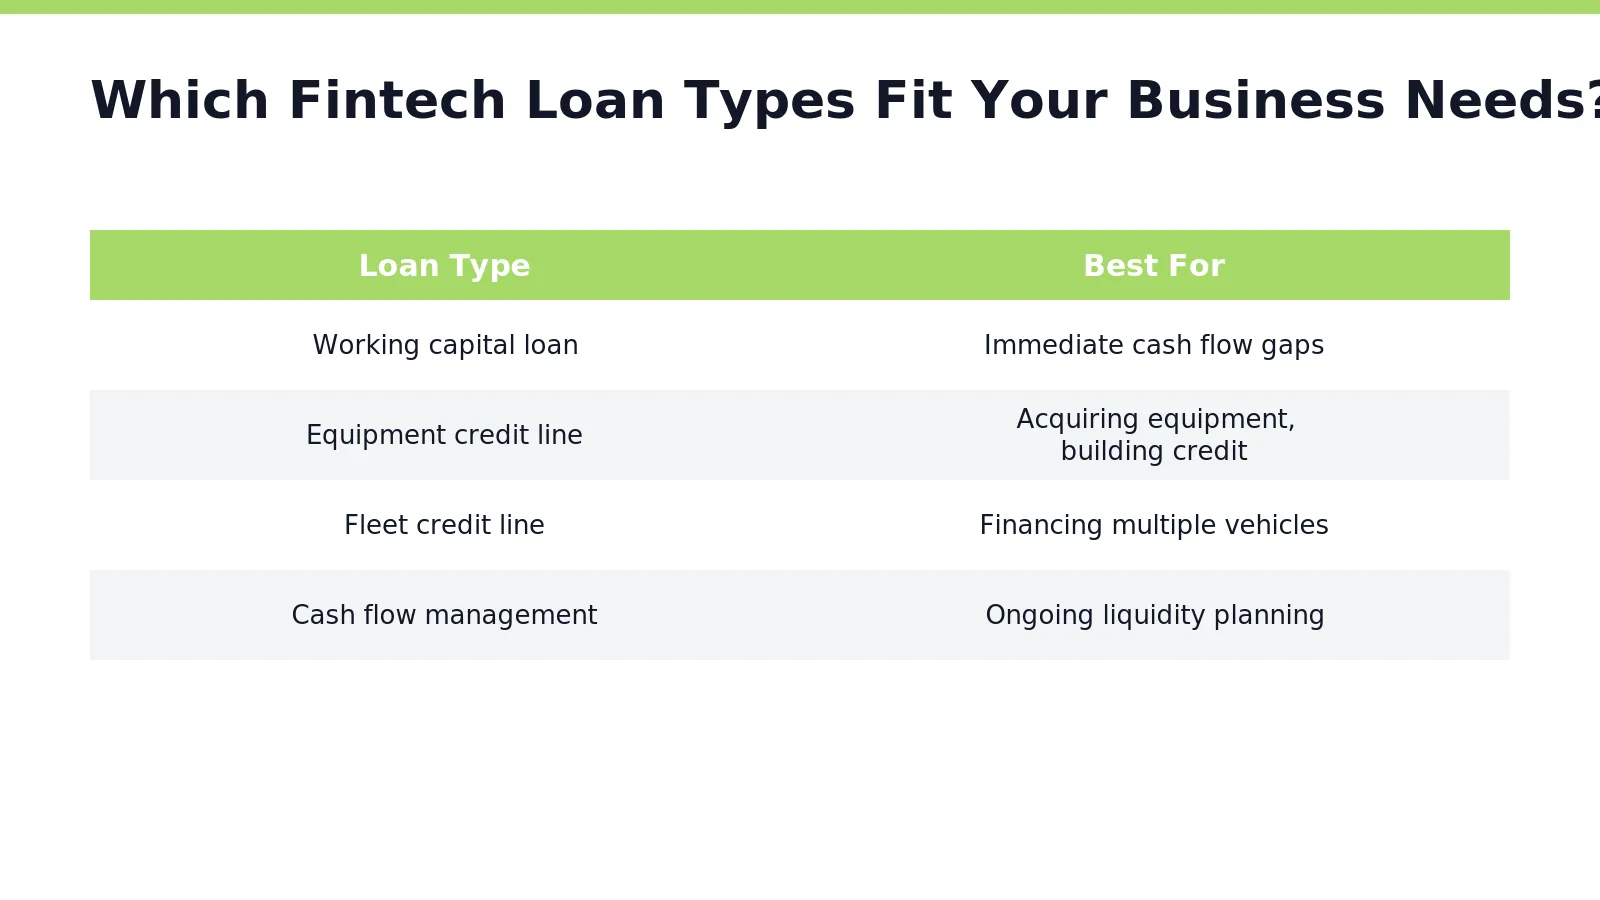
Four financing structures cover most working capital gaps small business owners face today. Each product solves a different problem, from smoothing cash flow to funding physical assets. Matching the tool to the need matters more than chasing the lowest rate alone.
Fintech business loans built for short-term cash needs move fastest. Working capital loans exist specifically to stabilize cash flow and meet immediate business needs, making them the go-to choice when payroll, inventory, or an unexpected expense can't wait for a traditional approval cycle. Speed here isn't a luxury; it's the entire point of the product.
Equipment and fleet financing serve a different purpose: building assets and credit simultaneously.
What's the difference between equipment credit lines and fleet credit lines?
Equipment credit lines let a business acquire needed machinery or tools right away, build business credit through consistent use, and deduct payments as legitimate business expenses. Fleet credit lines apply that same structure to vehicles, financing multiple units at once while building business credit and locking in available tax deductions. Both convert a purchase into a credit-building opportunity instead of a one-time cash drain. Explore vehicle financing options built around this same structure.
How does cash flow management fit into fintech financing?
Cash flow management isn't a loan product; it's a strategy layered on top of financing decisions. The goal is straightforward: working capital should be available when a business needs it, not discovered missing after the fact.
Choosing among these options within online commercial lending channels comes down to timing and purpose, not just approval odds. Digital business financing platforms make comparing them faster than traditional bank visits ever allowed.
How Much Can You Qualify For?
Qualification amounts depend on business age, revenue, and how a lender weighs risk. Baseline requirements typically include operating within the United States, maintaining at least six months in business, and meeting a minimum monthly revenue threshold. Businesses that miss any of these marks often face higher rates or outright denial, losing access to capital right when growth opportunities demand it most.
Funding ranges vary widely across the fintech business loans landscape. Some lenders extend financing up to $3 million for qualified businesses, while other products focus on shorter-term working capital needs. Working capital offerings in the online commercial lending space commonly start around $25,000, giving founders room to match funding size to a specific cash flow gap rather than settling for a one-size-fits-all number.
What factors affect how much a business can qualify for?
Lenders weigh time in business, monthly revenue, and industry risk when setting a funding ceiling. A newer company with strong monthly revenue can sometimes qualify for more than an older business with inconsistent cash flow. Credit profile structure matters too, since separating personal and business liability changes how underwriters view risk.
Does qualification amount depend on personal credit?
Not entirely. Building credit under the company's EIN rather than the owner's Social Security number shifts underwriting focus toward business performance. This is a core piece of VIP Business Credit's approach: guiding clients toward high-limit business loans and lines of credit while protecting personal assets through EIN-based credit.
Common qualification factors include:
- Time in business (six months or more, generally)
- Monthly revenue thresholds
- Business bank account activity
- Credit profile structure (personal vs. EIN-based)
Digital business financing platforms streamline this evaluation, often delivering a funding estimate within minutes rather than weeks.
What Role Does Your Credit Profile Play?
A business credit profile shapes which lenders say yes, how much capital gets offered, and what rates come attached. Personal credit scores alone rarely tell the full story of a company's financial health. Many lenders now factor in cash flow, revenue patterns, and industry data alongside credit scores. A single number does not always paint a complete picture of a business's actual performance.
That distinction matters for entrepreneurs applying for fintech business loans, where underwriting often moves faster and pulls from broader data sets than traditional bank review.
Why Does a Strong Credit Profile Matter for Funding Approval?
Lenders use a business credit profile to gauge risk before extending capital. Weak or inconsistent credit signals lead to higher rates, smaller offers, or outright denial, while a strong, well-documented profile puts a business in a better position to negotiate favorable terms.
FAQ
How fast does VIP Business Credit match businesses to funding?
VIP Business Credit's Business Fundability Scan matches business owners to pre-qualified funding options in 2-6 minutes, connecting them to fast, technology-driven working capital solutions.
How many lenders does VIP Business Credit connect entrepreneurs to?
VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders, spanning traditional banks and alternative finance providers to match different business needs.
Does applying through VIP Business Credit affect personal credit?
No, the Business Fundability Scan matches business owners to pre-qualified funding options with zero impact on personal credit during the initial matching process.
To view available service tiers and options, explore our fintech funding program pricing to get started.
Contact Us
- 📞 Phone: +1 (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Book a Consultation: Schedule a free consultation
- 🌐 Website: vipbizfunds.com
Proudly serving Sterling, VA and the surrounding areas, including Ashburn, Tysons, Reston, Herndon, Arlington, Fairfax County, and Washington, DC.


