Factoring vs Mca: Invoice Factoring vs Merchant Cash Advance
Factoring vs Mca: Invoice Factoring vs Merchant Cash Advance
Invoice factoring converts unpaid B2B invoices into immediate cash by selling them to a factoring company. Merchant cash advances provide upfront funds repaid through daily revenue deductions. Factoring suits businesses with outstanding invoices needing predictable, invoice-based cash flow; MCAs carry higher costs and daily repayment burdens. VIP Business Credit helps owners identify which sustainable financing path fits their business profile.
Key Takeaways
- Invoice factoring provides immediate capital by selling unpaid invoices, ideal for B2B companies with steady clients.
- Merchant Cash Advances require daily repayment from credit card sales, creating ongoing cash flow pressure for businesses.
- VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders offering diverse financing solutions.
- Banks increasingly restrict credit access, pushing Northern Virginia and Greater Washington, DC businesses toward alternative funding options.
What's the Real Difference Between Factoring and MCA? Exploring Factoring vs MCA
A merchant cash advance and invoice factoring solve the same problem — a shortage of cash — through opposite mechanics. Factoring vs MCA comes down to one core question: does the business borrow against future sales, or cash in money it has already earned? A merchant cash advance hands a company a lump sum in exchange for a percentage of future sales, meaning repayment rises and falls with revenue that hasn't happened yet. Invoice factoring works differently. It unlocks working capital by converting unpaid invoices into immediate cash, turning money already owed into money already in the bank.
That distinction highlights the deeper contrast between accounts receivable vs sales as the basis for funding. MCA repayment is tied to projected sales performance, an unpredictable figure. Factoring is tied to receivables — invoices for work already completed — a fixed, documented amount.
Which option gives faster access to cash? A quick funding comparison
Both solutions rank among the fastest alternative financing paths available, since neither relies on the slower approval timelines of traditional bank loans. For a true quick funding comparison, the deciding factor isn't speed — both move fast — it's what the business is willing to pledge against tomorrow's revenue versus yesterday's completed sales.
How does a lender network affect which option fits?
Businesses rarely need to guess in isolation. VIP Business Credit connects clients to a broad network of national and local lenders, matching each business to options suited to its stage, sector, and risk profile. That network spans more than 1,000 lending options, giving business owners room to compare structures like MCA and factoring side by side before committing to either one.
Why Are Business Owners Turning to Alternative Funding? A quick funding comparison perspective
Tighter bank lending standards explain much of the shift. Stricter regulations, an unpredictable economy, and thinner profit margins have pushed banks to raise the bar for small and medium-sized business loan approvals. Many qualified companies now get turned away because the underwriting rules changed, not because their business model failed.
That credit squeeze created real urgency. Facing fewer traditional options, business owners started looking for financing that moves faster and fits their actual cash flow needs. This search for speed and reliability sits at the center of any quick funding comparison between today's available options, including a straightforward look at factoring vs mca structures.
What Makes Alternative Financing Different From a Bank Loan?
Alternative financing typically evaluates a business on its operating performance rather than years of financial history. A comparison of accounts receivable vs sales volume, for example, determines eligibility for financing options like invoice factoring or a merchant cash advance. Approval timelines shrink from weeks to days because the underwriting focuses on cash flow evidence already in hand.
VIP Business Credit approaches this landscape as a long-term partner, not a one-time broker. Every recommendation comes with transparent, no-surprise pricing so business owners know the full cost before signing anything.
Who Benefits Most From These Funding Options?
Newer ventures chasing their first approval and established companies looking to scale both find a fit here. Some businesses need working capital just to cover payroll during a slow season. Others want better-priced capital to fund expansion without giving up equity.
Across Northern Virginia and the Greater Washington, DC region, entrepreneurs turn to VIP Business Credit to build credit tied to their EIN rather than personal credit history. That distinction protects personal assets while giving the business its own path toward stronger, lender-ready standing.
How Does a Merchant Cash Advance Work in the Factoring vs MCA Context?
A merchant cash advance delivers a lump sum of capital in exchange for a percentage of future sales. Repayment happens fast, often through daily or weekly deductions pulled straight from a business's bank account or its credit card receipts. That structure separates an MCA loan from a traditional term loan. A fixed monthly payment is due on a set date each month.
Speed is the main selling point. Approval can happen quickly, and funds often land within days rather than weeks. But that convenience carries a cost. This is where the real factoring vs mca comparison matters for a business owner weighing options during a cash crunch.
Why Do MCA Repayments Feel So Aggressive?
Daily or weekly withdrawals mean repayment starts almost immediately after funding. A business with uneven revenue can feel squeezed during slow weeks because the deduction doesn't pause for a bad sales day. Owners running a quick funding comparison should factor in how repayment timing lines up with actual cash flow, not just how fast the money arrives.
Is an MCA Based on Revenue or Receivables?
An MCA is tied to overall sales volume, not to specific unpaid invoices. That's a key distinction in the accounts receivable vs sales conversation — factoring advances cash against invoices already owed to a business, while an MCA advances cash against sales expected in the future.
Business owners exploring alternatives to high-cost daily repayment structures often benefit from working with a Business Credit Advisor. VIP Business Credit connects clients with local advisors who deliver personalized, concierge-level guidance on business loans, lines of credit, and a full credit-building program. Rooted in Northern Virginia and active across Loudoun County, the firm also serves clients digitally, nationwide.
How Does Invoice Factoring Turn Invoices Into Cash? Understanding accounts receivable vs sales
Invoice factoring converts unpaid customer invoices into working capital within days, not months. Rather than waiting the standard 30, 60, or even 90 days for customers to settle their bills, a business sells those outstanding invoices to a factoring company and receives an advance on their value almost immediately. This shifts the funding conversation from accounts receivable vs sales timing mismatches to something far more manageable: cash on hand when it's needed.
The mechanics are straightforward. A business delivers goods or services, generates an invoice, and submits it to the factoring provider. The provider then advances a large majority of that invoice's value up front, releasing the remaining balance—minus a fee—once the customer pays in full. This structure keeps capital moving without forcing the business owner into new debt.
Is Invoice Factoring the Same as a Loan?
No. Factoring is not borrowing; it's an advance against revenue a business has already earned but hasn't collected yet. A merchant cash advance, by contrast, delivers a lump sum against projected future sales, which is a meaningfully different repayment obligation. Sorting out factoring vs mca structures early prevents owners from committing to daily repayment terms that strain cash flow.
Why Does This Distinction Matter for Funding Decisions?
Choosing the right structure affects both cost and control. Understanding the difference between factoring and a cash advance is crucial to matching financing with how a company's cash actually moves. Business owners running a quick funding comparison should weigh repayment timing, cost, and how each option interacts with existing customer relationships before committing.
VIP Business Credit, based in Sterling, Virginia, guides business owners through these comparisons using broad lender access and purpose-built software. Advisors help separate personal and business liability by building credit under the company's EIN rather than the owner's Social Security number, giving business owners a clearer, more confident path toward sustainable capital.
Which Option Fits Your Receivables or Sales Volume? A factoring vs MCA decision guide
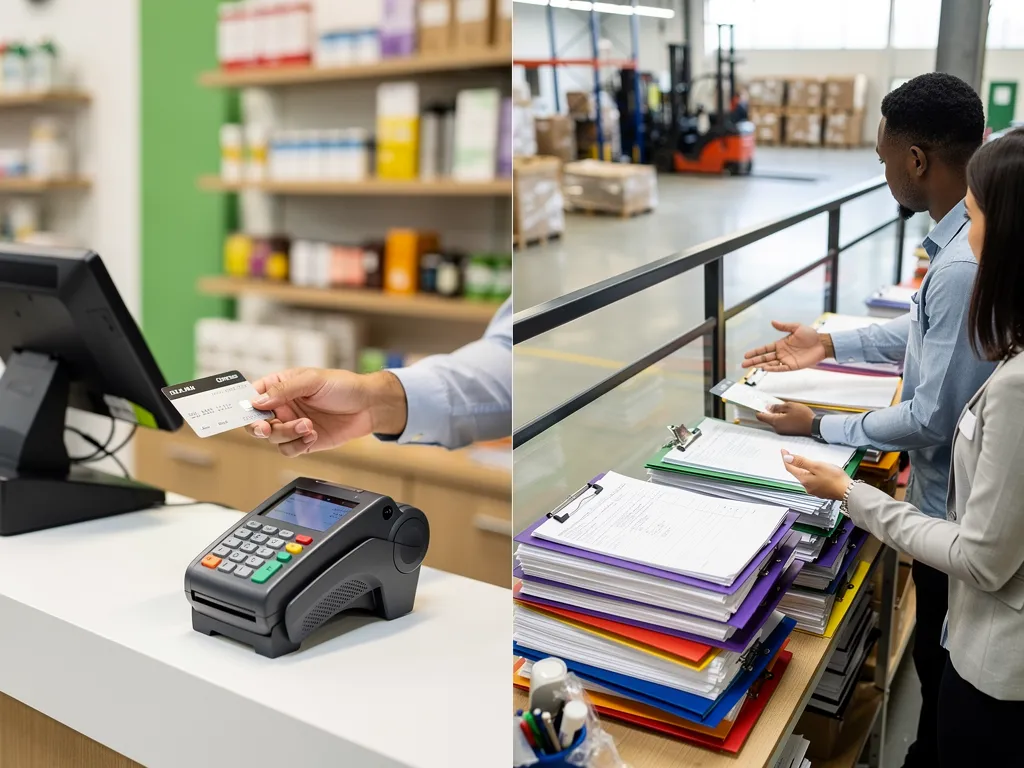
The right choice depends on where cash actually comes from: daily card swipes or unpaid customer invoices. A factoring vs MCA decision hinges less on preference and more on how a business generates revenue day to day. Retailers and restaurants with steady card transactions often lean one direction; B2B companies waiting on client payments lean another.
A merchant cash advance repays lenders through a percentage of future sales, pulled directly from daily or weekly revenue. This structure suits businesses with consistent, trackable transaction volume. But it ties repayment to sales performance, which can strain cash flow during slower stretches.
Invoice factoring works differently. It centers on accounts receivable vs sales volume, converting unpaid invoices into immediate working capital instead of borrowing against projected revenue. Businesses that bill clients on 30, 60, or 90-day terms often find factoring a more natural fit. It unlocks money already owed rather than money not yet earned.
Which financing option works best for B2B companies with slow-paying clients?
Invoice factoring generally suits B2B companies better, since it turns outstanding invoices into cash without waiting on client payment cycles. Businesses with strong receivables but thin cash reserves benefit most from this structure.
Running a quick funding comparison before applying helps clarify which path fits:
- Sales-based businesses (retail, restaurants, service shops): merchant cash advance often aligns with revenue patterns.
- Invoice-based businesses (manufacturers, wholesalers, B2B service firms): factoring converts receivables without adding sales-based repayment pressure.
- Newer ventures building initial approval history: matching financing to actual transaction type matters more than chasing the fastest offer.
VIP Business Credit connects clients to a broad lender network, matching each strategy to a business's stage, sector, and risk profile. That approach serves newer ventures seeking first approvals just as effectively as established firms with steady receivables looking to expand.
What Are the Real Cost and Repayment Trade-Offs?
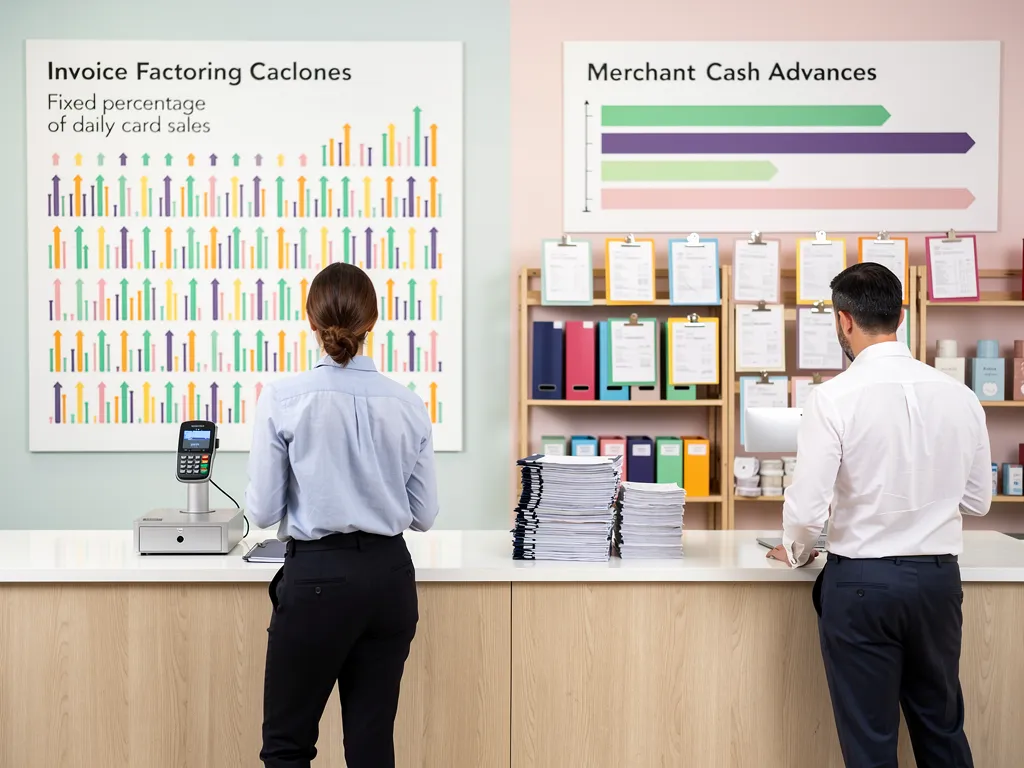
Repayment structure separates these two funding paths more than any other factor. Merchant cash advances and invoice-based funding differ greatly in repayment terms. In the risk each option carries for a business owner. A clear-eyed factoring vs MCA comparison has to start with how each product recovers its money.
Merchant cash advances collect a fixed percentage of daily card sales. A set daily or weekly withdrawal, until the advance is repaid in full. Invoice-based funding instead advances cash against unpaid invoices, tying repayment to when customers actually pay. That contrast highlights the real difference between accounts receivable vs sales as a repayment trigger. It also determines how much pressure lands on daily cash flow during a slow month.
Which option costs less over time?
Cost depends heavily on how long capital stays outstanding and how repayment is structured. Financing tied to unpaid invoices tends to align repayment with incoming cash, easing the risk of a shortfall. Advances tied to daily sales volume can compound quickly once sales dip, since fixed withdrawals keep coming regardless of revenue.
How fast can a business actually get funded? A quick funding comparison
For a quick funding comparison, both paths move fast. Owners can typically expect first funding within a few days of starting the application. Qualification requirements for each option stay relatively light. Speed alone should never decide which product fits a business.
VIP Business Credit's transparent, no-surprise pricing model gives owners the full cost picture before anything gets signed. Its credit-building program pairs coaching with financing guidance, helping owners understand underwriting criteria before they commit to either option.
A Worked Example: $50,000 in Funding, Two Different Paths
Numbers make the trade-offs concrete. Here's an illustrative look at how $50,000 in funding plays out differently depending on the structure a business chooses:
How Can Strong Business Credit Lower Funding Costs?
Strong business credit lowers funding costs by giving lenders confidence to offer better rates, longer terms, and higher limits. A company with an established credit profile looks like a safer bet on paper. That lower risk translates directly into lower pricing on loans, lines of credit, and factoring arrangements alike.
Emergency capital solutions like invoice factoring and merchant cash advances solve the immediate problem: cash today. Both can supply a steady stream of capital that fuels growth and keeps operations moving during a crunch. But neither option builds a credit foundation on its own. That's where a longer-term strategy matters.
Why Build Credit Under the Business's EIN Instead of an Owner's SSN?
Building credit under the company's EIN, rather than the owner's Social Security number, separates personal and business liability. This protects personal assets from business debt exposure. It also strengthens the company's own borrowing power over time. Future funding decisions rely less on personal credit history and more on the business's track record.
What Role Does Local Guidance Play in Cutting Funding Costs?
Local Business Credit Advisors offer concierge-level guidance tailored to each owner's situation. Rather than pushing a one-size-fits-all product, advisors help match financing choices to a business's credit-building goals. That guidance matters most when an owner is choosing between fast, expensive capital and slower, cheaper alternatives.
Combining broad lender access with purpose-built software and hands-on guidance helps owners shift away from repeated emergency borrowing. Instead of cycling through short-term fixes, businesses build toward sustainable, better-priced capital. Key advantages include:
- Lower interest rates tied to demonstrated creditworthiness
- Access to larger credit lines as the business profile strengthens
- Reduced reliance on personal guarantees over time
- A clearer path from short-term funding to long-term financial stability
Which Financing Path Should You Choose Next? Factoring vs MCA and beyond
Two financing roads lead to working capital, but they don't lead to the same destination. Both factoring vs mca options can hand a business a steady stream of cash to cover payroll, restock inventory, or fund a new contract. Only one of them, however, builds a credit profile that lenders recognize and reward over time. That distinction matters more than the speed of approval.
How Does a Business Decide Between the Two?
The decision comes down to timeline versus trajectory. A company facing an immediate cash gap may need capital within days, and either path can deliver it. But a company planning growth over the next one to three years needs a strategy that strengthens its standing with future lenders, not one that only closes today's gap.
VIP Business Credit approaches this decision as a quick funding comparison paired with a longer-term credibility check. Advisors examine where a business sits today, then match it to options that fit both urgency and growth plans. This process works for two very different types of clients:
- Newer businesses chasing their first real approval
- Established companies ready to scale, refinance, or access better-priced capital
Rooted in Northern Virginia, VIP Business Credit serves clients digitally and connects them to lenders across the country. Location never limits the options on the table.
Weighing accounts receivable vs sales as funding triggers helps clarify which product fits. Receivable-based options draw on invoices already earned; sales-based advances draw on future revenue. Combining broad lender access, purpose-built software, and hands-on guidance, VIP Business Credit gives owners the clarity to choose the path that protects both cash flow and long-term borrowing power.
FAQ
What is the main difference between invoice factoring and a merchant cash advance?
Invoice factoring converts unpaid B2B invoices into immediate cash. A merchant cash advance provides upfront funds repaid through daily deductions from future revenue.
Which option provides faster funding for a business?
Both invoice factoring and merchant cash advances deliver funds faster than traditional bank loans. The real choice depends on pledging future revenue versus converting already-completed invoices into cash.
How does VIP Business Credit help businesses choose between factoring and MCA?
VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders. Works with each business to match it with the financing option suited to its profile.
Conclusion
In closing, the choice between invoice factoring and merchant cash advances hinges on your business's cash flow pattern, repayment capacity, and tolerance for cost. Invoice factoring works best when you have predictable receivables. A merchant cash advance suits businesses with consistent daily or weekly card sales. Both accelerate capital access, but each carries distinct trade-offs in fees, repayment structure, and impact on your business credit profile. Understanding these differences—and how each option aligns with your financial runway—positions you to make a decision that strengthens rather than strains your operation.
About The Author
Lee Johnson is the Founder of VIP Business Credit, a seasoned Real Estate Investor, Business Growth Strategist, and Master Certified Professional Coach. Bringing over 25 years of experience in business finance and credit strategy, Lee specializes in guiding entrepreneurs to build fundable, lender-ready business credit profiles tied to an EIN rather than personal SSNs, separating business and personal liabilities.
Contact VIP Business Credit
- 📞 Phone: (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule A Business Financial Health Strategy Call
- 🌐 Website: vipbizfunds.com
- 🎯 FREE Business Success Scan: Get Your Free Scan
Proudly serving Sterling, Virginia, and surrounding communities across Northern Virginia and the Greater Washington, DC area.


