Medical Practice Financing: The Complete Guide to Funding Healthcare Growth with Healthcare Business Loans
Medical Practice Financing: The Complete Guide to Funding Healthcare Growth with Healthcare Business Loans
The financial landscape of medical practice financing can feel overwhelming for healthcare providers seeking to expand their services or upgrade their equipment. This comprehensive guide aims to demystify the various funding options available, focusing on healthcare business loans and their role in supporting medical practice growth. Readers will learn about the types of loans available, the application processes, eligibility criteria, and best practices for securing funding. Many healthcare providers face challenges in accessing the capital needed for growth, but understanding the financing landscape can provide effective solutions. This article will cover essential topics, including types of loans, application processes, and strategies for improving credit, ensuring that healthcare providers are well-equipped to make informed financial decisions.
Key Takeaways
- Healthcare business loans provide tailored financing solutions to support medical practice growth and equipment upgrades.
- Common loan types include SBA loans, term loans, lines of credit, equipment financing, invoice financing, and merchant cash advances.
- The loan application process involves assessing needs, gathering documentation, selecting lenders, submitting applications, and responding to underwriting.
- Eligibility depends on credit scores, business history, financial documentation, and sometimes collateral requirements.
- Best practices for securing funding include thorough preparation, clear lender communication, credit building, and developing a strong business plan.
- Medical equipment financing helps practices access modern technology while preserving cash flow and offering potential tax benefits.
- Practice acquisition loans offer flexible terms and competitive rates to facilitate healthcare practice purchases and expansions.
- Improving and maintaining strong credit scores significantly enhances loan approval chances and favorable financing terms.
- Using loan calculators and comparing financing options helps healthcare providers select the best loan for their specific needs.
Comprehensive Guide on Medical Practice Financing through Healthcare Business Loans
Medical practice financing is crucial for healthcare providers looking to grow their operations, acquire new equipment, or manage cash flow. Understanding the various financing options available can empower practitioners to make informed decisions that align with their business goals. Healthcare business loans are specifically designed to meet the unique needs of medical practices, offering tailored solutions that can facilitate growth and enhance service delivery. By exploring the different types of loans, application processes, and eligibility criteria, healthcare providers can better navigate the complexities of financing and secure the funding necessary for their success.
1. Types of Loans Available:
For medical practice financing, several types of loans cater to the specific needs of healthcare providers. Understanding these options can help practitioners choose the best fit for their financial requirements.
- SBA Loans: These loans are backed by the Small Business Administration and, per the SBA 7(a) Loan Program, offer favorable terms, including lower interest rates and longer repayment periods.
- Term Loans: Traditional loans that provide a lump sum of capital, which is repaid over a fixed period with interest.
- Business Lines of Credit: Flexible financing options that allow healthcare providers to draw funds as needed, making it ideal for managing cash flow.
- Equipment Financing: Loans specifically designed for purchasing medical equipment, where the equipment itself serves as collateral.
- Invoice Financing: A short-term funding option that allows businesses to borrow against their outstanding invoices.
- Merchant Cash Advances: A financing option where businesses receive a lump sum in exchange for a percentage of future credit card sales.
Understanding these loan types can help healthcare providers make informed decisions about their financing options.
Comparing Healthcare Financing Options at a Glance
The table below summarizes how the main healthcare business loan types compare, making it easier to narrow down the right fit before diving into applications.
2. Application Processes:
The application process for medical practice loans can vary depending on the lender and the type of loan. However, there are common steps that healthcare providers should follow to ensure a smooth application experience.
- Assess Business Needs: Determine the specific financial requirements and how much funding is needed.
- Gather Documentation: Prepare necessary documents, including financial statements, tax returns, and business plans.
- Choose the Right Lender: Research lenders that specialize in healthcare financing and compare their offerings; resources such as the SBA's Lender Match can help connect providers with SBA-approved lenders.
- Submit Application: Complete the application form and submit it along with the required documentation.
- Respond to Underwriting Questions: Be prepared to answer any questions from the lender during the underwriting process.
By following these steps, healthcare providers can streamline their loan application process and improve their chances of approval.
3. Eligibility Criteria:
Eligibility for medical practice loans typically depends on several factors that lenders consider when assessing a borrower's financial health.
- Credit Score Requirements: A strong credit score is often essential for securing favorable loan terms. While many lenders prefer a credit score of 680 or higher, some may consider lower scores depending on other factors.
- Business History: Lenders may look for a proven track record of financial stability and operational success.
- Financial Documentation: Accurate and comprehensive financial statements are crucial for demonstrating the practice's financial health.
- Collateral Requirements: Some loans may require collateral, such as equipment or real estate, to secure the loan.
Understanding these criteria can help healthcare providers prepare for the application process and improve their chances of securing funding.
4. Best Practices for Securing Funding:
To enhance the likelihood of obtaining financing, healthcare providers should consider implementing several best practices.
- Thorough Preparation: Ensure all documentation is complete and accurate before applying.
- Clear Communication with Lenders: Maintain open lines of communication with potential lenders to clarify any questions or concerns.
- Focus on Credit Building: Work on improving credit scores by making timely payments and reducing debt.
- Develop a Solid Business Plan: A well-structured business plan can demonstrate the practice's potential for growth and profitability.
- Research and Compare Options: Explore various lenders and loan products to find the best fit for the practice's needs.
By following these best practices, healthcare providers can improve their chances of securing the funding necessary for growth.
What Are Healthcare Business Loans and How Do They Support Medical Practices?
Healthcare business loans are financial products specifically designed to meet the needs of medical practices. These loans provide the necessary capital for various purposes, including expansion, equipment purchases, and operational expenses. By offering tailored financing solutions, healthcare business loans enable practitioners to invest in their practices and enhance patient care.
Understanding Different Types of Medical Practice Financing Options
The loan types available to healthcare providers, SBA loans, term loans, business lines of credit, equipment financing, invoice financing, and merchant cash advances, are detailed above under "Types of Loans Available," including what each is best suited for. One additional option worth noting here:
- Traditional Bank Loans: Often used for larger purchases, these loans typically require strong credit and an established financial history.
Reviewing the comparison table above alongside this option gives healthcare providers a full picture of the financing landscape before narrowing in on a choice.
Eligibility Criteria and Credit Score Requirements for Healthcare Loans
Eligibility for healthcare loans often hinges on several key factors, including credit scores, business history, and financial documentation. A strong credit score is crucial, as it reflects the practice's financial health and ability to repay the loan. Many lenders prefer a credit score of 680 or higher, although some may consider lower scores depending on other factors. Additionally, a solid business history and accurate financial documentation can significantly enhance a practice's chances of securing funding.
How Can Medical Equipment Financing Options Help Upgrade Your Practice?
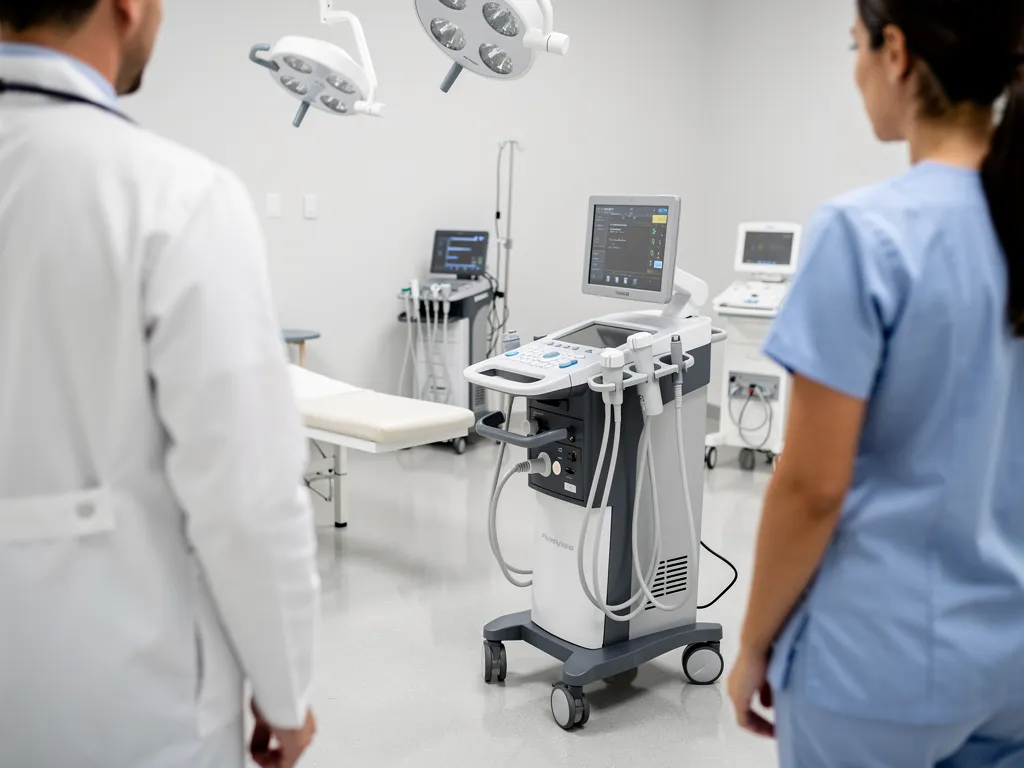
Medical equipment financing is a vital resource for healthcare providers looking to upgrade their facilities and improve patient care. By providing access to the latest technology and equipment, these financing options can enhance operational efficiency and patient outcomes.
Types of Financing Available
Healthcare providers can choose from various financing options for medical equipment, including:
- Equipment Loans: These loans provide the necessary capital to purchase equipment outright, with the equipment serving as collateral.
- Equipment Leasing: This option allows practices to use equipment without the upfront costs of purchasing, making it easier to upgrade as technology advances.
Benefits of Medical Equipment Financing
The advantages of medical equipment financing include:
- Preserved Cash Flow: Financing allows practices to maintain cash reserves for other operational needs.
- Access to Modern Equipment: Providers can acquire the latest technology, improving patient care and operational efficiency.
- Tax Advantages: Certain financing options may offer tax benefits, further enhancing the financial viability of equipment purchases.
Potential Impacts on Practice Efficiency and Patient Care
Investing in modern medical equipment can lead to significant improvements in practice efficiency and patient care. Enhanced technology can streamline operations, reduce wait times, and improve diagnostic accuracy, ultimately leading to better patient outcomes.
Loan Terms, Interest Rates, and Repayment Options for Equipment Financing
When considering equipment financing, healthcare providers should be aware of the various loan terms, interest rates, and repayment options available. Typical loan terms range from 3 to 7 years, with interest rates varying based on the lender and the borrower's creditworthiness. Understanding these factors can help practices make informed decisions about their financing options.
What Should You Know About Practice Acquisition Loans for Healthcare Providers?
Practice acquisition loans are essential for healthcare providers looking to purchase existing practices or expand their operations. These loans can provide the necessary capital to facilitate smooth transitions and ensure continued patient care.
Key Features of Practice Acquisition Financing
Key features of practice acquisition financing include:
- Flexible Terms: Many lenders offer customizable loan terms to suit the specific needs of healthcare providers.
- Competitive Interest Rates: Acquisition loans often come with favorable interest rates, making them an attractive option for financing.
- Quick Access to Capital: These loans can provide timely funding, allowing practices to seize acquisition opportunities as they arise.
Comparing SBA Loans and Private Lenders for Acquisition Purposes
When considering practice acquisition loans, healthcare providers often weigh the benefits of SBA loans against those offered by private lenders. SBA loans typically offer lower interest rates and longer repayment terms, making them a popular choice. However, private lenders may provide faster access to capital and more flexible terms, which can be advantageous in competitive acquisition scenarios.
How to Build and Improve Credit for Medical Practice Financing Success?
Building and maintaining a strong credit profile is crucial for healthcare providers seeking financing. A solid credit score can significantly impact loan eligibility and terms, making it essential for practices to prioritize credit health.
Strategies for Enhancing Credit Scores
Healthcare providers can enhance their credit scores through several strategies:
- Timely Payments: Consistently making payments on time is one of the most effective ways to improve credit scores.
- Monitoring Credit Reports: Regularly reviewing credit reports can help identify and address any inaccuracies or issues.
- Establishing Trade Lines: Building relationships with suppliers and vendors can create positive credit history.
Impact of Credit on Loan Eligibility
A strong credit score can improve a practice's chances of securing financing and obtaining favorable loan terms. Lenders often view higher credit scores as an indicator of financial responsibility, which can lead to lower interest rates and better repayment options.
Tips for Maintaining Good Credit
To maintain good credit, healthcare providers should:
- Regularly Monitor Credit: Keeping an eye on credit reports can help identify potential issues early.
- Promptly Dispute Errors: Addressing inaccuracies on credit reports can prevent negative impacts on credit scores.
Strategies for Credit Building Tailored to Healthcare Businesses
Healthcare providers can implement specific strategies to build credit, such as:
- Establishing Trade Lines: Working with suppliers to create credit accounts can help build a positive credit history.
- Maintaining Low Credit Utilization: Keeping credit card balances low relative to credit limits can positively impact credit scores.
Impact of Credit Scores on Loan Approval and Terms
Credit scores play a significant role in loan approval and the terms offered by lenders. Higher credit scores can lead to lower interest rates and more favorable repayment terms, making it essential for healthcare providers to prioritize credit health.
What Is the Application Process for Medical Office Financing?
The application process for medical office financing can be complex, with multiple stages, varying documentation requirements, and lender-specific underwriting standards all in play. Understanding the steps involved, from assessing financial needs through responding to underwriting questions, can help healthcare providers move through the process more efficiently and with fewer surprises along the way.
Step-by-Step Guide to Applying for Physician Practice Loans
- Assess Eligibility: Determine the practice's financial needs and eligibility for various loan options.
- Choose the Right Loan Type: Research different loan types to find the best fit for the practice's needs.
- Prepare Required Documentation: Gather necessary financial documents, including tax returns and business plans.
Common Documentation and Preparation Tips for Loan Approval
To improve the chances of loan approval, healthcare providers should:
- Gather Documents: Ensure all required documentation is complete and accurate.
- Fill Forms Carefully: Double-check all application forms for accuracy to avoid delays in processing.
What Are the Latest Trends and Market Insights in Medical Practice Financing?
Staying informed about the latest trends and market insights in medical practice financing can help healthcare providers make strategic decisions about their funding options.
2025-2026 Healthcare Financing Growth Statistics
Recent data from the Federal Reserve Banks' Small Business Credit Survey points to a growing demand for financing among small businesses, including a rising share of providers seeking loans to support day-to-day operations. This trend reflects the ongoing need for capital in the healthcare sector as practices adapt to changing market conditions.
Emerging Flexible Loan Products and Financing Innovations
Innovations in financing products are emerging to meet the evolving needs of healthcare providers. Flexible loan options, such as revenue-based financing and merchant cash advances, are gaining popularity as they offer quick access to capital without the stringent requirements of traditional loans.
How to Choose the Best Loan Options for Your Medical Practice?
Selecting the right loan option is crucial for healthcare providers looking to secure financing. By understanding the various products available, practitioners can make informed decisions that align with their business goals.
Comparative Analysis of Healthcare Business Loans and Financing Products
When comparing healthcare business loans, providers should consider factors such as interest rates, repayment terms, and eligibility requirements. This analysis can help identify the most suitable financing options for the practice's needs.
Using Loan Calculators and Tools to Assess Financing Needs
Loan calculators and financial assessment tools can be valuable resources for healthcare providers. These tools allow practitioners to estimate monthly payments, compare loan options, and assess their overall financing needs.
Where Can You Find Support and Resources for Medical Practice Financing?
Healthcare providers seeking financing can access various resources and support systems to aid in their funding journey, from government-backed loan programs to lender directories and educational materials built specifically for the healthcare sector. Tapping into these resources early in the process can help practices compare options, avoid common application pitfalls, and connect with lenders who understand the particular cash flow patterns and regulatory considerations that come with running a medical practice.
Government Programs and SBA Loan Updates for Healthcare Providers
Government programs, including SBA loans, offer valuable resources for healthcare providers seeking financing. Staying informed about updates and changes to these programs can help practitioners take advantage of available funding opportunities.
Educational Resources and Case Studies on Successful Practice Funding
Numerous educational resources and case studies are available to help healthcare providers understand the financing landscape. These resources can provide insights into successful funding strategies and best practices for securing financing.
Many healthcare providers are now turning to business loans to secure the funding needed for growth, and understanding the nuances of business insights can make those decisions easier to navigate. For those looking to understand the costs involved, pricing structures are readily available to help plan a budget effectively, and exploring frequently asked questions can provide quick answers to common concerns about medical practice financing. Healthcare providers across Northern Virginia and the DC metro area can also find region-specific guidance, including for practices in Ashburn, Tysons, Reston and Herndon, Arlington, and Fairfax County.
Improving business credit is also a key factor in securing favorable loan terms. For more information, visit VIP Business Funds to explore the full range of financing options available.
About The Author
Lee Johnson is the Co-Founder and CEO of VIP Business Credit, bringing over 25 years of experience helping entrepreneurs identify the right business loan types and meet startup funding requirements. He is also a Master Certified Professional Coach with more than 500 coaching hours, holding a Bachelor of Science from Fairleigh Dickinson University and a Master of Business Administration from the University of Phoenix. Since 2005, Lee has built a personal real estate investment portfolio exceeding 1,700 units valued at approximately $254 million across multiple U.S. markets. Serving Sterling, VA and the surrounding areas, Lee and his team at VIPBizFunds.com specialize in guiding new business owners from credit building to loan approval.
Contact Us
- 📞 Phone: +1 (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule your consultation
- 🌐 Website: vipbizfunds.com
- 🎯 FREE Business Funding Pre-Qualification Scan
Serving Sterling, VA and surrounding areas.
Sources
- U.S. Small Business Administration, SBA 7(a) Loan Program overview — program terms, rates, and eligibility guidelines referenced for SBA-backed healthcare financing.
- Federal Reserve Banks, Small Business Credit Survey — data on small business financing demand and credit access trends cited in discussions of healthcare financing growth.
- U.S. Small Business Administration, Lender Match — a resource for healthcare providers researching SBA-approved lenders.
Frequently Asked Questions
What credit score do I need to qualify for a healthcare business loan?
Many lenders prefer a credit score of 680 or higher for favorable terms, though some may still consider applicants with lower scores depending on business history, financial documentation, and other factors. Building and maintaining strong credit improves both approval odds and the rates offered.
How long does it take to get approved for a medical practice loan?
Approval timelines vary by lender and loan type. SBA loans often take longer due to more extensive underwriting, while options like business lines of credit, invoice financing, or merchant cash advances can provide quicker access to capital. Having documentation ready in advance helps speed up any application.
What is the difference between SBA loans and private lender financing for a practice acquisition?
SBA loans typically offer lower interest rates and longer repayment terms, making them attractive for long-term investments. Private lenders, on the other hand, often provide faster access to capital and more flexible terms, which can matter in competitive acquisition situations.
Can I finance medical equipment without a large upfront payment?
Yes. Equipment financing and equipment leasing both allow practices to acquire new technology without paying the full cost upfront. The equipment itself typically serves as collateral, which helps preserve cash flow for other operational needs.
What documents are typically needed to apply for medical practice financing?
Lenders generally request financial statements, tax returns, and a business plan, along with documentation that demonstrates business history and financial health. Gathering these in advance and double-checking accuracy can help avoid delays during underwriting.


