Commercial Real Estate Loans Northern VA in Northern Virginia
Commercial Real Estate Loans Northern VA in Northern Virginia
By VIP Business Credit Editorial Team Updated 2026-09-03
Commercial real estate loans in Northern Virginia finance office, retail, industrial, and flex-space purchases, refinances, and expansions across Fairfax and Loudoun County. These are a specialized subset of broader commercial loans tailored to meet the unique needs of the region’s property market. VIP Business Credit, based in Sterling, VA, connects Northern Virginia business owners to a network of over 1,000 lenders, matching each property deal to programs suited for the business's stage and risk profile. Their expertise spans traditional commercial mortgages northern virginia, SBA 504 real estate loans va, bridge loans, Sterling VA commercial property loans, owner occupied commercial real estate financing, and other financing options tailored to complex local needs.
Key Takeaways
- VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders specialized in commercial real estate loans northern va for tailored financing solutions.
- Based in Sterling, VA, VIP Business Credit serves Northern Virginia with a focus on business property financing va.
- VIP Business Credit's proprietary credit-assessment tool helps businesses evaluate their creditworthiness and borrowing potential, crucial for successful real estate acquisition va.
- Burke & Herbert Bank provides commercial real estate financing with expertise in zoning laws, land use, and environmental assessments, essential for commercial real estate loans northern va deals.
- Loan terms typically require a debt service coverage ratio (DSCR) greater than 1.25x, ensuring sufficient cash flow to cover loan payments.
- Loan-to-value (LTV) limits commonly reach up to 80% depending on property type and lender criteria, balancing borrowing power with risk management.
Why Do Commercial Real Estate Loans Differ In NoVA?
Northern Virginia's commercial lending market runs on deep-rooted local relationships, not generic underwriting formulas. Builders, property owners, and developers across the Washington metro region consistently turn to regional banks rather than distant national chains when they need financing for a new project. This preference exists for a reason: northern virginia cre financing works differently than generic lending elsewhere, and commercial real estate loans northern va require a lender who understands the terrain, both literally and financially.
Zoning boards in Loudoun County operate distinctly from those in Fairfax or Arlington. Land use history varies block by block. Stakeholder relationships often determine whether a project gets approved on schedule or stalls for months. Regional lenders bring deep expertise in these issues, including working capital — an edge a call-center underwriter can't match.
What makes a NoVA lender different from a national bank?
Experience matters more than size. Some banks serving the Washington metro area have provided real estate and construction financing for more than 170 years, building institutional knowledge of local zoning patterns, permitting timelines, land use disputes, and appraisal processes that shape deal structures and financing terms.
Does that history actually help with financing terms?
Yes. Lenders with local insight structure business property financing va around real conditions, not assumptions. This matters heavily during real estate acquisition va transactions, where timing, site-specific knowledge, and financial metrics like DSCR and LTV limits affect final terms:
- Zoning familiarity leads to fewer surprises during due diligence and appraisal.
- Land use history enables faster resolution of title, permitting, and environmental issues, including Phase I ESA outcomes.
- Stakeholder connections contribute to smoother negotiations with local boards and expedite approvals.
- Financial analysis ensures compliance with DSCR > 1.25x and acceptable LTV thresholds, optimizing loan structure.
A business credit strategy ignoring these regional dynamics risks slower approvals and less negotiating strength.
What Types Of Commercial Properties Qualify?
Retail centers, office buildings, industrial warehouses, multi-family apartment complexes, and mixed-use developments across Fairfax, Loudoun, and the surrounding Northern Virginia corridor all qualify for commercial financing programs. Purchase and refinance options extend to both owner-occupied and investor commercial properties, including those seeking SBA 504 real estate loans va or bridge financing options. This variety gives buyers flexibility whether acquiring a first building or restructuring debt on an existing portfolio.
Skipping eligibility verification wastes time with lenders who never intended to fund the property type in question. Northern Virginia's commercial corridors reflect a wide mix of property types, and lenders structure programs around that variety. A business owner eyeing a Loudoun County flex space has different underwriting considerations than an investor targeting a Fairfax retail strip. Matching property types to the right program early prevents wasted applications.
What property types typically qualify for commercial financing?
Programs generally support the following categories:
- Retail – shopping centers, standalone storefronts, mixed-tenant strips
- Office – single-tenant and multi-tenant professional buildings
- Multi-family – apartment complexes and residential investment properties
- Industrial – warehouses, distribution centers, light manufacturing spaces, often paired with equipment financing for machinery and vehicles tied to operations
- Mixed-use – buildings combining retail, office, or residential units
Does financing cover both buying and refinancing?
Yes. Financing structures typically cover both new acquisitions and refinancing of existing debt on commercial or residential investment property, and this dual coverage is crucial for real estate acquisition va projects where an owner needs to purchase immediately and refinance later as the property stabilizes. Because property types and business goals vary widely, VIP Business Credit connects clients with over 1,000 lenders and tailored programs, including SBA 504 loans with favorable terms for owner-occupied commercial real estate and commercial bridge loans for flexible interim financing during property transitions.
How Does Business Property Financing Work In VA?
Commercial real estate loans Northern VA follow a structured path: establishing a business credit profile, matching to lenders, and closing financing tied to the company's EIN rather than the owner's personal finances. This separation protects personal assets if a deal turns sour and establishes a foundation for sustained growth via property acquisitions, renovations, or expansions across Fairfax, Loudoun, and Greater Washington, DC.
VIP Business Credit works with entrepreneurs throughout Northern Virginia to build this EIN-based credit foundation before property deals reach lenders. Businesses that need working capital alongside a property transaction, for example to cover renovation costs or bridge a cash-flow gap before a lease stabilizes, can also explore invoice financing as a complementary funding source. Businesses with thin or personal-only credit histories typically face higher rates or denials on business property financing va applications. Establishing trade lines and reporting under the company’s identity repositions underwriters’ views on risk.
What Steps Come Before Applying For A Commercial Loan?
Preparation determines whether a real estate acquisition va transaction closes on favorable terms or stalls in underwriting. Business owners typically progress through these stages:
- Review current business credit standing with attention to LTV and DSCR expectations.
- Correct inconsistent business identity data across reporting agencies.
- Build trade credit history tied to the EIN and demonstrate stable cash flow to support DSCR > 1.25x.
- Match the business to lenders suited to its stage, industry, property type, and loan products including SBA 504 real estate loans va or bridge loans.
How Does Pre-Qualification Help Property Buyers?
A pre-qualification workflow shows which programs a business qualifies for immediately and flags which require more preparation. This saves Northern Virginia buyers from wasted applications and hard credit pulls on mismatched programs by replacing guesswork with a clear sequence of eligible next steps.
What Loan Terms Should You Expect?
Term structures on commercial real estate loans northern va vary by lender, property type, and borrower strength, but several standards appear consistently across Fairfax, Loudoun, and the surrounding market. Borrowers who understand these terms negotiate confidently and avoid surprises at closing, paying less interest and maintaining repayment flexibility.
Loan-to-Value (LTV) Limits
Most lenders offer loan-to-value ratios up to 80%, though owner-occupied properties often support higher LTVs due to lower risk profiles. Investor commercial properties may see stricter limits to mitigate potential vacancies or market volatility.
Debt Service Coverage Ratio (DSCR)
Lenders generally require a DSCR above 1.25x, meaning the net operating income from the property must cover loan payments by at least 125%. Maintaining this threshold helps demonstrate strong cash flow and reduces lender risk, impacting loan approval and rate offers.
Owner-Occupied vs Investor Properties
Owner-occupied commercial properties typically benefit from more favorable loan terms, including lower interest rates and higher LTV limits, as businesses occupy and directly manage these assets. Investor-owned properties face higher scrutiny due to income dependency on tenants, underwriting cash flows more conservatively.
Environmental Site Assessments (Phase I ESA)
Many lenders require a Phase I Environmental Site Assessment to identify potential contamination risks before approving financing. Addressing these findings early prevents costly delays or denials in the financing process.
Appraisal Processes
Commercial property appraisals consider location, condition, income potential, and comparable sales. Appraisal results influence LTV calculations and loan terms. Regional lenders possess local appraisal expertise, ensuring accurate valuations aligned with Northern Virginia market realities.
Commercial Bridge Loans
Bridge loans provide short-term financing that bridges gaps between transactions, such as acquiring a new property before selling an existing asset. These loans offer expedited approval and interest-only payments but typically carry higher rates, suitable for transitional financing needs.
Common repayment structures for real estate acquisition va projects include:
- Adjustable terms up to 15 years
- Fixed rates locked for 5 or 10 years before adjusting
- Amortization periods up to 25 years, spreading principal and lowering monthly payments
Choosing between shorter fixed periods and longer amortization schedules shapes monthly cash flow for years. Owners pursuing business property financing va for industrial or mixed-use buildings should weigh holding periods and exit strategies when selecting terms.
A Sample Financing Scenario in Loudoun County
Consider a hypothetical illustration of how these terms come together in practice. A business owner identifies a $2.4 million flex-space building in Loudoun County's data-center corridor, intending to occupy 60% of the space and lease the remainder. Because the property is majority owner-occupied, the deal qualifies for an SBA 504 structure: a bank loan covering 50% of the purchase price, an SBA debenture covering 40%, and a 10% down payment from the owner, roughly $240,000.
Given Loudoun County's typically conservative underwriting (max LTV near 75%, DSCR above 1.3x), the lender confirms the business's net operating income covers the projected debt service with a comfortable margin before moving to a Phase I Environmental Site Assessment and appraisal. Because the ownership structure, zoning, and financials were prepared and verified in advance, the file moves through underwriting without the back-and-forth that typically delays deals in this market, closing within the SBA 504 program's standard 20-25 year amortization window. This mirrors the pattern Northern Virginia lenders look for: a well-documented EIN-based credit profile, realistic LTV and DSCR expectations going in, and zoning and environmental groundwork done early rather than discovered mid-underwriting.
Ready to Explore Your Loan Options?
Understanding LTV limits, DSCR requirements, and the right loan structure is only half the equation, matching that knowledge to the right lender is where deals actually close. VIP Business Credit connects Northern Virginia business owners to a network of over 1,000 lenders suited to their property type and credit profile.
📞 Call (571) 248-3863 or start your free business funding pre-qualification scan to see which programs fit your deal.
Comprehensive Breakdown of Loan Structures for Northern Virginia Properties
Northern Virginia's diverse commercial real estate landscape requires nuanced financing solutions. Here is a detailed overview of prominent loan structures available:
SBA 504 Loan Virginia (CDC Debenture Structure)
- Designed for owner-occupied fixed assets (land, buildings, heavy equipment).
- Typical financing split: 50% bank loan, 40% SBA debenture, 10% borrower down payment.
- Low down payment requirements, often 10%, with maximum LTV around 90% when combined.
- Long amortization terms, up to 20-25 years, with fixed interest rates on the SBA portion.
- Strict owner-occupancy requirements, generally 51% or more of the property must be owner-occupied.
- Highly suitable for expansion and modernization projects.
SBA 7(a) Real Estate Financing
- Flexible loan program that can be used for real estate acquisition, refinancing, or working capital.
- Generally requires down payments between 10-20%, with LTV up to 85% depending on the project.
- Loan amounts up to $5 million, with variable and fixed-rate options.
- Amortization up to 25 years for real estate, typically with balloon payments beyond 10 years.
- Less strict owner-occupancy rules compared to SBA 504, can apply to investor properties with proper justification.
Conventional Commercial Mortgages Northern Virginia
- Offered by banks, credit unions, and CMBS lenders.
- Down payments vary typically from 20-30%, with LTV often capped at 75-80%.
- Loan term structures commonly 5-10 years with amortization up to 25 years.
- Requires comprehensive underwriting including DSCR generally above 1.25x, thorough appraisals, and environmental reviews.
- Suitable for a broad range of property types including multi-family, retail, and office.
Commercial Bridge Loans
- Short-term financing bridging the gap between transactions or renovations.
- LTV typically lower, around 65-75%, with higher interest rates and fees.
- Terms generally 6 months to 3 years, often interest-only payments.
- Useful for time-sensitive acquisitions, repositioning properties, or during refinance waiting periods.
Comparative Table: SBA 504 vs SBA 7(a) vs Conventional Commercial Mortgage Northern VA
Underwriting Checklist for Virginia Commercial Real Estate Borrowers
Successful underwriting for commercial real estate loans northern va requires thorough documentation and due diligence. Key elements include:
- Phase I Environmental Site Assessments (ESA): Evaluates potential contamination liabilities. A clean or manageable report expedites approval.
- Commercial Appraisals: Professional valuation factoring in location (e.g., Loudoun County commercial real estate trends), condition, and income potential. Influences LTV and loan terms.
- Rent Rolls and Lease Agreements: For investment properties, detailed rent rolls demonstrate income stability. Lease terms inform cash flow projections.
- Global Cash Flow Analysis: Underwriters review both property-level and business-level cash flows to assess DSCR compliance and overall creditworthiness.
- Business and Personal Tax Returns: Validation of income and financial stability.
- Property Zoning and Land Use Documentation: Essential especially in Fairfax County commercial mortgages and Loudoun County markets where zoning varies extensively.
Northern Virginia Commercial Property Market Breakdown
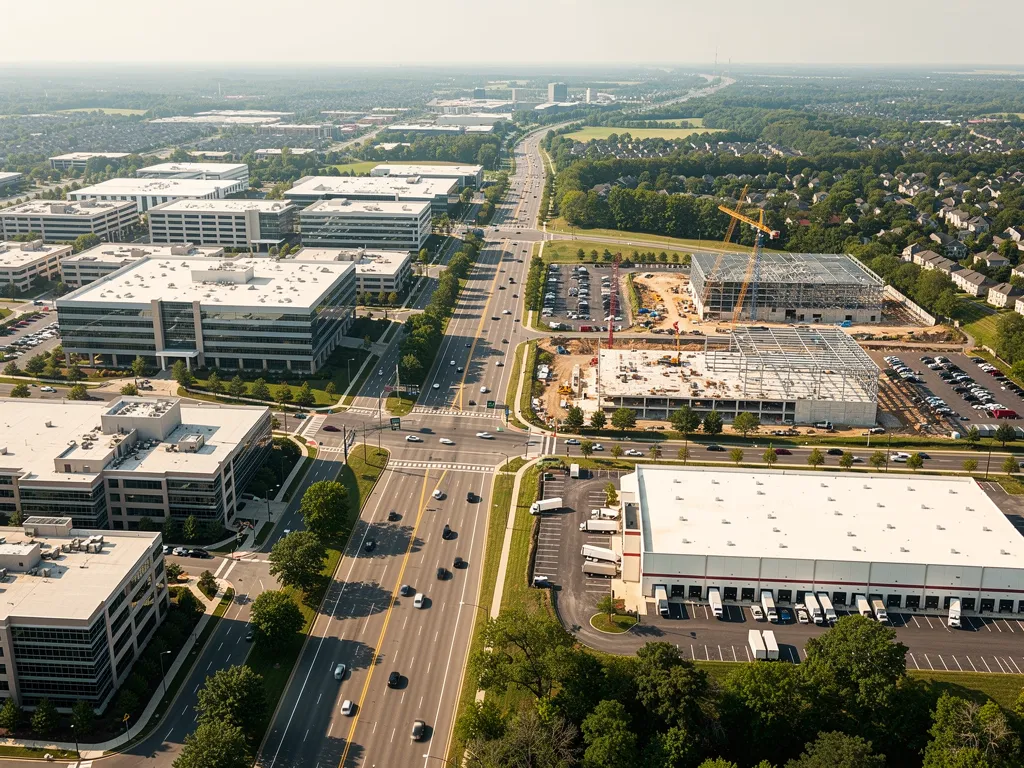
Loudoun County Commercial Real Estate: Growth corridor driven by data centers, warehouses, and flex space. Strong demand with new developments a key feature. Loans often target industrial and tech-related properties. LTV and DSCR metrics tend toward conservative levels due to market volatility, typically max 75% LTV and DSCR > 1.3.
Fairfax County Commercial Mortgages: Established suburban office and retail markets with steady demand. Higher owner-occupancy rates allow lenders to offer more aggressive LTVs (up to 80%) and moderately flexible DSCR requirements (as low as 1.25x). Zoning complexities in Fairfax require experienced lenders.
Here's a quick side-by-side of how underwriting benchmarks compare between the two counties:
Key Financial Formulas in Commercial Real Estate Underwriting
Debt Service Coverage Ratio (DSCR) is a critical metric calculated as:
DSCR = Net Operating Income (NOI) / Debt Service (Annual Loan Payments)
Lenders require DSCR > 1.25x typically, ensuring NOI covers loan payments by at least 25% margin to reduce default risk.
Loan To Value (LTV) ratio measures borrowing power:
LTV = Loan Amount / Appraised Property Value
LTV limits of up to 80% are common in Northern Virginia, balancing borrower equity and lender risk.
Which Local Lenders Serve NoVA Businesses?
Regional banks across the Washington metro area bring over 170 years of combined local knowledge to commercial real estate loans northern va, providing expert evaluation of Fairfax's and Loudoun's zoning and market specifics. This expertise expedites and sharpens lending decisions compared to out-of-market underwriters.
Regional banks are a vital piece, but business owners often need options beyond a single institution’s appetite. VIP Business Credit connects clients to a diverse network of banks, alternative finance providers, and specialized programs including SBA 504 loans and commercial bridge loans, matching businesses with sources most likely to approve favorable terms.
Do business owners need a local bank for a commercial property loan?
Not necessarily. While local familiarity assists with complex zoning and environmental issues, many Northern Virginia entrepreneurs qualify for more competitive terms via national and specialized lenders tailored to their property type, loan size, and risk profile.
How does an advisor help compare lender options?
Lender comparison is time-consuming and confusing, especially for busy owners. Local Business Credit Advisors provide personalized guidance, reviewing financials and directing businesses to lenders best suited to their profiles and properties.
For real estate acquisition va projects, the right lender depends on property type, business history, and timeline. Working through a broad network increases viable options substantially.
An Advisor's Note
"The businesses that close fastest aren't the ones with the biggest balance sheets, they're the ones who treat the credit and documentation work as part of the deal, not paperwork to get through afterward. In over 25 years of building and financing real estate, the deals that stalled almost always had the same root cause: zoning or environmental questions that surfaced during underwriting instead of before it." – Lee Johnson, Co-Founder and CEO of VIP Business Credit
That pattern holds across property types and loan sizes: preparation done before a lender sees the file consistently outperforms preparation done in response to a lender's questions.
How Can You Prepare Your Business For Approval?
Successful approval requires honest assessment of how lenders perceive a business, focusing on financial metrics too. Owners preparing for commercial real estate loans in Northern Virginia gain the greatest advantage by identifying and closing gaps before lenders review applications.
Capital-Ready Score and related tools reveal credit position weaknesses and highlight risk factors around cash flow, DSCR, LTV, and environmental compliance. Cleaning up business records, standardizing data across registrations and licenses, and actively reporting trade credit reduce perceived risks dramatically.
What documents matter most for a real estate loan application?
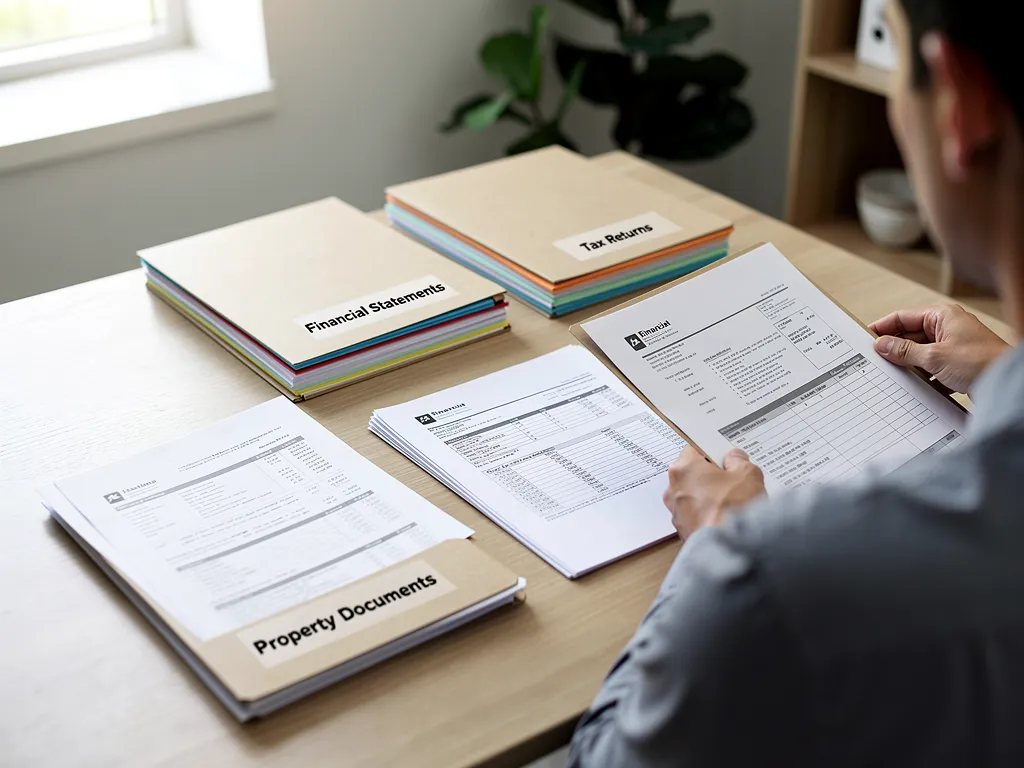
Lenders expect a comprehensive and transparent paper trail for Northern Virginia property loans. Core documentation includes:
- Business formation and EIN verification documents
- Recent financial statements showing net operating income and cash flow
- Tax returns for the business and relevant principals
- Trade credit and payment histories establishing creditworthiness
- Property details, such as zoning certifications, Phase I ESA reports, and intended uses
- Clear explanation of loan purpose and repayment strategy
How does credit-building coaching support real estate acquisition plans?
Structured credit-building programs educate owners on underwriting criteria and guide them through improving credit profiles, cash flow documentation, and environmental risk management. This preparation shortens time to approval by reducing surprises and rejected submissions, and it builds the confidence that comes from seeing the business the way a lender will, which is the real value of working through a structured credit-building program rather than applying cold.
What Does The Real Estate Acquisition Process Look Like?
Commercial property acquisitions across Fairfax, Loudoun, and Northern Virginia follow familiar stages fused with critical local complexities including zoning, land use history, environmental review, and stakeholder input, and real estate acquisition va processes typically progress through:
- Property identification and due diligence, including zoning checks, land-use and environmental site assessments (Phase I ESA).
- Stakeholder and jurisdictional reviews, acknowledging impacts from neighboring interests, planning offices, and environmental regulators.
- Financing structure selection, aligning the right lender and loan products including bridge loans or SBA 504 real estate loans va.
- Underwriting and appraisal, where lenders assess the property, credit profile, DSCR, LTV, and environmental reports.
- Closing and ongoing asset management, ensuring performance meets loan covenants and property goals.
Financing shapes each phase. Commercial real estate loans northern va must suit both the property and business stage. New ventures face different scrutiny than established firms expanding portfolios. Tailored lending strategies account for this diversity.
Does Acquisition Financing Cover Refinancing Too?
Yes. Acquisition financing often overlaps with refinancing needs, especially for investors holding mixed commercial and residential portfolios. Business property financing va can flex as holdings mature, so borrowers can lean on bridge loans or SBA-backed products as circumstances change.
Why Does Zoning Matter So Much In This Region?
Northern Virginia's commercial corridors and development zones are dense and still evolving, so zoning rules can vary from one block to the next. Knowing the land use and environmental history of a property early on helps avoid costly surprises during permitting, appraisal, or resale, and keeps financing timelines on track.
How Do You Get Started With Financing?
Launching financing begins with connecting to a local advisor familiar with Northern Virginia’s commercial market. Business owners across Fairfax, Loudoun, and Greater Washington, DC lose valuable time and negotiating strength without a clear credit picture. VIP Business Credit, based in Sterling, VA, works with entrepreneurs needing commercial real estate loans northern va that are realistic and fit property types, DSCR, and LTV expectations. The starting point is rarely the application itself: most often, it’s an honest business credit assessment followed by a plan to close gaps blocking approval.
What Steps Are Involved in the Process?
- Initial consultation reviewing credit profile, business entity, and financing goals including loan product preferences like SBA 504 or bridge loans.
- Gap identification pinpointing missing strengths before submitting to lenders.
- Lender matching pairing the business to programs aligned with stage, property type, DSCR, and LTV requirements.
- Application and negotiation submitting well-documented requests to optimize approval odds.
How Does Pricing Work With an Advisor?
Pricing transparency prevents costly deal breakdowns. VIP Business Credit offers clear, no-surprise pricing so costs are known upfront, avoiding hidden fees that jeopardize budgets or negotiations. This clarity is especially important given the multifaceted nature of business property financing va involving multiple parties and timelines, and it underlies VIP Business Credit's long-term, partnership-driven approach, staying with clients through complex real estate acquisition va deals that often span many months.
Begin by visiting vipbizfunds.com to request a consultation. Advisors serve Sterling, Fairfax, Loudoun County and the wider Northern Virginia region, offering both in-person meetings and fully remote financing coordination.
FAQ
What types of properties qualify for commercial real estate loans in Northern Virginia?
Retail centers, office buildings, industrial warehouses, multi-family apartments, and mixed-use developments across Fairfax, Loudoun, and adjacent areas qualify for financing, refinancing, and purchase programs including SBA 504 and bridge loans.
Why do local lenders matter for commercial real estate deals in NoVA?
Local lenders understand zoning, environmental risks including Phase I ESA results, appraisal standards, and stakeholder relations essential to navigating commercial real estate loans northern va efficiently and avoiding costly surprises.
How does VIP Business Credit help Northern Virginia property owners find financing?
VIP Business Credit connects business owners to a network of 1,000+ national and local lenders and uses proprietary credit-assessment tools to align deals with appropriate financing programs considering DSCR, LTV, property type, and business profile.
What's the typical timeline for commercial real estate loan approval in Northern Virginia?
Timelines vary by loan type and property complexity, but a well-prepared application with clean zoning, Phase I ESA, and financial documentation generally moves faster through underwriting. SBA 504 and 7(a) products tend to take longer than conventional mortgages because of added federal review steps, while bridge loans close on an expedited schedule when speed is the priority.
What credit profile do lenders expect before approving a real estate loan?
Lenders want to see a business credit profile real estate loan applicants can stand behind: an EIN-based credit history separate from the owner's personal finances, consistent trade lines, and documented cash flow that supports the required DSCR. Building this lender ready business credit va profile ahead of time, rather than during underwriting, is what shortens approval timelines and strengthens negotiating position.
Conclusion
Securing the right commercial real estate loan in Northern Virginia demands understanding your business’s credit health and matching it to lenders aligning with your property type, loan product, and financial metrics like DSCR and LTV. VIP Business Credit’s extensive lender network and proprietary tools simplify this complex landscape, connecting borrowers with terms that foster sustainable growth. Whether building initial creditworthiness or scaling existing holdings, the foundation remains consistent: a strong EIN-based credit profile combined with targeted, locally informed financing strategies including SBA 504 real estate loans va, commercial bridge loans, and conventional mortgages.
About the Author
Lee Johnson is the Co-Founder and CEO of VIP Business Credit, a seasoned real estate investor, business growth strategist, and a Master Certified Professional Coach. He holds a Bachelor of Science degree from Fairleigh Dickinson University and an MBA from the University of Phoenix. With over 25 years of experience, Lee has built a real estate investment portfolio exceeding 1,700 units valued at approximately $254 million across multiple U.S. markets. His mission is to help small business owners achieve financial freedom by establishing strong business credit and accessing favorable loan terms through VIP Business Credit’s 12-month Fundability coaching program.
- 📞 Phone: (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule A Business Financial Health Strategy Call
- 🌐 Website: vipbizfunds.com
- 🎯 FREE Business Funding Pre-Qualification Scan: Start Your Free Scan
- 📍 Location: Sterling, VA, and the surrounding Greater Washington, D.C. region
Expand Your Commercial Property Portfolio in Northern Virginia
Acquire, refinance, or develop commercial assets with flexible terms. Explore competitive commercial real estate loans and custom commercial business loans.
Research & Sources
The loan structures and due-diligence standards referenced throughout this article align with publicly documented federal programs and industry standards:
- SBA 504 Loan Program: The U.S. Small Business Administration's 504 program finances fixed assets like land, buildings, and heavy equipment through a Certified Development Company (CDC) debenture structure, as detailed on the SBA's official 504 loan page.
- SBA 7(a) Loan Program: The SBA's flagship 7(a) program covers real estate acquisition, refinancing, and working capital, with full terms and eligibility published on the SBA's 7(a) loan program page.
- Phase I Environmental Site Assessments: The standard practice for evaluating a commercial property's environmental liability follows ASTM International's E1527 standard, summarized by the U.S. EPA's guidance on all appropriate inquiries.
- EIN-Based Business Credit: Establishing a business identity separate from personal finances starts with an Employer Identification Number, with full application details on the IRS's About Form SS-4 page.
- Loudoun County Zoning: Zoning classifications, permitted uses, and land development regulations referenced throughout this article reflect published guidance from Loudoun County's Planning and Zoning Department.


