Business Credit Reports Explained: How to Read & Improve Your Business Credit Score [2026]
Business Credit Reports Explained: How to Read & Improve Your Business Credit Score [2026]
- What Is a Business Credit Report?
- How to Check Your Business Credit Report?
- What Is a Business Credit Score and How to Understand It?
- How Can You Improve Your Business Credit Score?
- What Are the Major Business Credit Bureaus?
- What Are Common Business Credit Report Errors and How to Fix Them?
- Frequently Asked Questions
By Lee Johnson, VIP Business Credit
Knowing your business credit reports is essential for entrepreneurs and small business owners who need financing or want to build long-term financial strength. These business credit reports show lenders, including those assessing lender requirements for a business loan or SBA loan, how reliable your company is and influence loan approvals, interest rates, and vendor terms. This article breaks down the metrics that move the needle, gives practical steps to improve your business credit score, and explains why keeping a clean business credit profile matters. Our goal is to give you clear, usable guidance so you can confidently improve your business credit position and understand your business credit rating.
In this guide we'll cover the factors that shape business credit scores, how to read those scores, the role of vendor credit and trade credit including net-30 accounts, and the basics of business entity formation and business banking. You'll also find advice on business credit monitoring tools like Nav, CreditSignal, and Credit.net, using 0% business credit card offers wisely, and preparing strong SBA loan applications with a solid business plan and accurate financial statements.
This material is designed for owners at different stages: startups building initial credit builder tradelines, established firms optimizing financing terms, and businesses preparing for growth or acquisition. Where helpful, we include practical examples and short checklists you can use to prioritize actions based on impact and effort.
What Is a Business Credit Report?
A business credit report is a record of your company's financial behavior, including payment history, credit utilization, and public records such as UCC filing, liens, judgments, and bankruptcy. Lenders, suppliers, and insurers use it to judge your business's creditworthiness and risk. Strengthening these fundamentals is the focus of a dedicated business credit building program, which helps establish the tradelines and payment history this report measures.
A strong business credit profile opens doors to lower rates, larger lines of credit such as a business line of credit, and better vendor terms, while a weak profile can limit growth and increase borrowing costs, making regular review and remediation essential. For businesses without an established credit history, trade credit and properly reported vendor credit can be the quickest way to produce a meaningful report, while established firms typically unlock better financing terms through a steady pattern of on-time payments and controlled credit utilization.
How to Check Your Business Credit Report?
To check your business credit report, obtain reports from major credit bureaus such as Dun & Bradstreet (which issues the DUNS number), Experian Business, and Equifax Business, since each bureau may have different data and scoring models, so reviewing all three gives a comprehensive view of your business credit rating. Regularly monitoring your reports helps you spot errors, detect fraud, and understand your credit profile; use online portals or subscribe to business credit monitoring services that provide alerts for changes or new credit inquiries.
What Is a Business Credit Score and How to Understand It?

Business credit scores reflect measurable behaviors that lenders use to assess risk. Key components include:
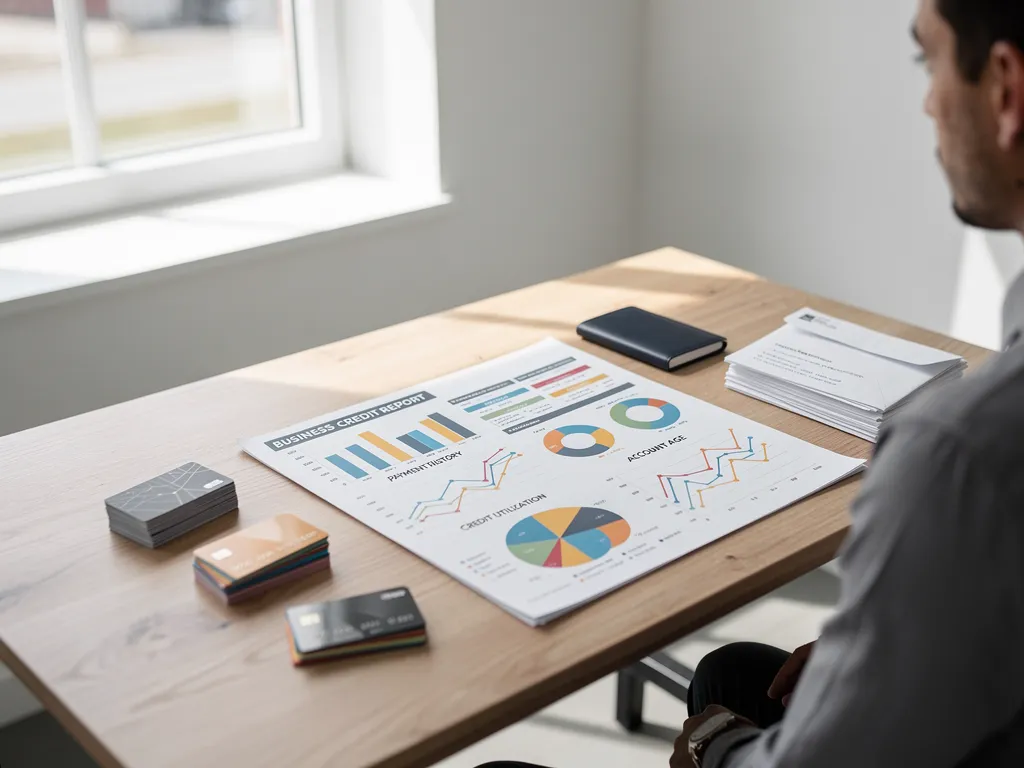
- Payment History: Timely payments are the most important signal lenders look for. Consistency reduces perceived risk and improves your credit recommendation.
- Credit Utilization: Aim to keep balances well below your credit limit, under 30% is a common benchmark to demonstrate restraint and maintain excellent credit.
- Length of Credit History: Older accounts provide a longer track record and generally improve your score over time, reflecting your business age.
- Public Records: Negative filings such as liens, judgments, or bankruptcy can severely impact your score and risk assessment.
- Credit Inquiries: Hard inquiries can lower your score temporarily, while soft inquiries do not affect it.
Different bureaus use various scoring models, including the Paydex score by Dun & Bradstreet, Intelliscore Plus by Experian Business, and FICO SBSS by Equifax Business. Understanding these helps you interpret your business credit score accurately within the credit score range from poor credit to excellent credit.
How Can You Improve Your Business Credit Score?
Raising your business credit score takes consistent, practical steps. Start with these proven tactics:
- Monitor Credit Reports Regularly: Check reports from major bureaus like Dun & Bradstreet, Experian Business, and Equifax Business to catch errors and unexpected changes early using business credit monitoring tools.
- Pay On Time, Every Time: Prioritize on-time payments. Automate payments where possible to avoid late marks that damage your payment history and business credit score.
- Build Vendor Tradelines: Work with suppliers that report payment activity to credit bureaus. Timely payments to those vendors help establish positive vendor credit and trade credit history, including net-30 accounts.
- Manage Credit Utilization: Keep balances below 30% of your credit limit on business credit cards and lines of credit to maintain a healthy outstanding balance.
- Maintain Older Accounts: Keep positive accounts open to lengthen your credit history and improve your business credit rating.
- Form a Legal Business Entity: Register as an LLC, corporation, or sole proprietorship and obtain an EIN (employer identification number) to separate personal and business credit.
- Use Dedicated Business Bank Accounts: Separate your finances to simplify bookkeeping and demonstrate financial organization to lenders.
Additional practical steps include negotiating longer vendor payment terms only after confirming you can reliably meet them, keeping simple written policies for invoice approval and payment, and using bookkeeping software that flags high utilization or overdue invoices measured in days beyond terms (DBT). If you have a high-priority borrowing need, focus first on actions with the fastest measurable impact: clear any recent delinquencies and reduce balances on revolving accounts.
What Are the Major Business Credit Bureaus?
Business credit bureaus collect financial data from lenders, vendors, and public records, then use proprietary scoring models to rate a company's creditworthiness. Because each bureau uses different inputs and algorithms, your scores can vary between providers.
The three major bureaus are:
- Dun & Bradstreet: Known for the DUNS number and the Paydex score, focusing heavily on trade credit and vendor payments.
- Experian Business: Uses Intelliscore Plus and incorporates payment trends, credit utilization, and public records.
- Equifax Business: Uses the FICO SBSS model, which includes industry risk and time in business alongside payment history.
Understanding how bureaus gather and report information gives you valuable bureau insights, helping you spot discrepancies and take corrective action.
Credit Bureaus & Lender Risk Assessment Credit management underpins the financial system. Lenders assess borrower risk to limit losses and decide loan amounts. They gather borrower information directly or from other lenders; that information sharing, whether voluntary through private services or required via public credit bureaus, reduces market costs and improves efficiency. Value of big data to finance: observations on an internet credit Service Company in China, X Li, 2015
Regularly monitoring reports from these bureaus reduces surprises and gives you the opportunity to correct errors before they affect financing decisions. If you find discrepancies, gather documentation (invoices, canceled checks, bank statements) and follow the bureau's credit report dispute process, keeping a log of communications and outcomes so you can show lenders a consistent effort to maintain accurate records.
What Are Common Business Credit Report Errors and How to Fix Them?
A careful credit report analysis can reveal errors on your business credit report, including incorrect payment history, outdated public records, misreported credit utilization, or accounts that do not belong to your business. These mistakes can unfairly lower your business credit score and affect your ability to secure financing such as a commercial loan or business line of credit.
To fix errors:
- Obtain copies of your reports from Dun & Bradstreet, Experian Business, and Equifax Business.
- Identify inaccuracies such as wrong balances, duplicate accounts, or incorrect public filings.
- Gather supporting documents like invoices, canceled checks, or court documents.
- Submit a credit dispute to the bureau following their process, which is often available online.
- Keep detailed records of all communications and responses.
- Follow up until the bureau updates your report accordingly.
Understanding your rights under the Fair Credit Reporting Act (FCRA) can help you navigate disputes effectively.
Frequently Asked Questions
What is a good business credit score?
A good business credit score varies by bureau but generally a Paydex score above 80, an Intelliscore Plus above 75, or a FICO SBSS score above 700 is considered strong. These scores indicate timely payments, low risk to lenders, and a positive credit recommendation.
How often should I check my business credit?
Check your business credit report at least quarterly. If you're preparing to apply for financing or your business is growing quickly, review it monthly. Frequent checks help you spot errors or fraud quickly and give you time to correct issues before lenders review your profile.
How long does it take to build business credit?
Building business credit typically takes several months of consistent, on-time payments and responsible credit use. Establishing vendor credit and trade credit with a good vendor list including tier 1 credit, tier 2 credit, and tier 3 credit suppliers helps accelerate the process. Correcting errors and managing credit utilization also speed improvements.
What hurts my business credit score?
Negative factors include late or missed payments, high credit utilization, negative public records such as liens, judgments, or bankruptcy, frequent hard credit inquiries, and inaccurate information on your business credit report. Poor management of outstanding balances and failure to maintain a good payment history also damage your score.
Key Takeaways
- Business credit reports measure a company's creditworthiness and affect loan approval and terms.
- Payment history, credit utilization, and account age are primary drivers of business credit scores.
- Regularly review business credit reports to spot mistakes and protect your profile.
- Vendor tradelines and consistent, on-time payments build positive business credit history.
- Forming a legal business entity and using dedicated business bank accounts help separate personal and business credit.
- Business credit monitoring services give alerts and support to manage and protect your business credit.
- Qualifying for 0% business credit card offers requires a strong profile and a clear repayment plan.
- Your business credit report strongly affects SBA loan eligibility and loan terms.
- Prepare for SBA loans by reviewing finances, crafting a solid business plan, and strengthening your credit.
Conclusion
Understanding and improving your business credit reports is a practical, ongoing process that directly affects your ability to grow. Focus on timely payments, consistent monitoring, and building tradelines with reporting vendors. Combine those habits with proper business entity setup and organized business banking to create a lender-ready profile. Use the resources and steps above to take control of your credit and unlock better financing for your business.
Finally, treat credit management as a regular business process: assign ownership, schedule periodic reviews, and track measurable improvements over time. That discipline turns credit from a passive report into an actionable asset that supports strategic growth. Whether you're running a startup in Reston or Herndon, scaling a firm in Arlington, or operating anywhere across the DC metro area, the same fundamentals apply: monitor your reports, pay on time, and build tradelines deliberately.
About The Author
Lee Johnson is a seasoned business credit expert with over 15 years of experience helping entrepreneurs and small business owners build and improve their credit profiles. As the founder of VIP Business Credit, Lee specializes in credit coaching, financing strategies, and credit risk management. His practical insights and hands-on approach have empowered countless businesses to secure better financing terms and achieve sustainable growth. Lee is passionate about educating business owners on the importance of credit management as a key driver of long-term success.
Contact Us
- 📞 Phone: +1 (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule a free credit consultation
- 🌐 Website: vipbizfunds.com
- 🎯 FREE Business Funding Pre-Qualification Scan: Get Started
- 📍 Serving: Sterling, VA and surrounding areas


