Secured Business Credit Lines: Flexible Funding With Assets
Secured Business Credit Lines: Flexible Funding With Assets
By *VIP Business Credit* Editorial Team · Updated 2026-09-07
Secured business credit lines let owners pledge business assets as collateral to unlock higher limits than unsecured options allow. VIP Business Credit connects to over 1,000 national and local lenders, matching secured line structures to each company's assets, stage, and cash flow needs through its underwriting insights and advisor guidance.
Key Takeaways
- Secured lines of credit use collateral like equipment, inventory, or real estate to unlock flexible funding access.
- VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders for competitive financing options.
- Interest charges apply only to borrowed amounts, making secured lines cost-effective for Northern Virginia businesses.
What Is a Secured Business Credit Line?
A secured business credit line is a revolving credit account tied to collateral the business already owns, including equipment, inventory, real estate, or cash deposits. Backing the account this way lowers the lender's risk, which often translates into higher limits than an unsecured line would allow. For a business owner in Flexible Funding weighing seasonal cash flow gaps against long-term borrowing costs, that distinction matters.
The mechanics stay simple. Once approved, the business draws funds up to its limit, pays interest only on the amount actually borrowed, and repays on its own schedule. As the balance gets paid down, that credit becomes available again. No need to reapply for new funding every time working capital runs tight.
This structure falls under a broader category finance professionals call revolving business credit: businesses borrow up to a set limit, pay the balance down, and borrow again as needs arise. **Asset backed credit lines** work on this same revolving principle, just with collateral doing the work of securing better terms.
How does collateral affect the credit limit?
Collateral value directly shapes how much a lender will extend. Equipment, inventory, real estate, and cash deposits each carry different risk profiles in a lender's eyes. The appraised value of the asset often sets the ceiling on the credit line, which is why choosing the right collateral for business credit line approval matters from the start.
Consider a two-year-old landscaping company with a 690 personal credit score and a work truck it owns outright. Pledging that truck as collateral can unlock a lower rate and a higher limit than the business would qualify for on credit history alone, since the lender has a tangible asset to fall back on if payments stop.
Is a secured line the same as a term loan?
No. A term loan delivers a lump sum that gets repaid on a fixed schedule. A collateralized line of credit stays open and reusable, and businesses in Flexible Funding managing unpredictable expenses typically find that flexibility more useful than a one-time disbursement. VIP Business Credit helps entrepreneurs across Northern Virginia, including Arlington, Fairfax County, and Tysons, as well as the Greater Washington, DC region, build EIN-based business credit. The firm structures these accounts by connecting local Business Credit Advisors to a nationwide lender network, matching collateral to the right program from the start.
Why Do Growing Businesses Need Asset-Backed Credit?
Growing businesses need asset-backed credit because expansion rarely follows a predictable schedule. Payroll, inventory restocks, and sudden equipment repairs often arrive faster than revenue does. A secured business credit line solves this timing problem by giving Flexible Funding-based companies quick, easy access to funds for purchases, unexpected expenses, and cash flow support whenever the need arises.
Unlike a traditional term loan, this type of financing works more like a continuous loan a business owner can tap whenever necessary, without filing a new application every time cash gets tight. That structure matters most during growth phases, when funding needs shift from month to month.
What Makes a Line of Credit Different From a Term Loan?
A term loan delivers one lump sum with a fixed repayment schedule. A line of credit stays open and reusable, letting a business draw funds, repay them, and draw again as conditions change. For companies scaling operations across Flexible Funding, that reusability reduces the need to reapply for financing every time a new expense appears.
Why Choose Asset-Backed Options Specifically?
Asset backed credit lines use business property, including equipment, receivables, or inventory, as collateral, which strengthens the case a lender sees when reviewing an application. This flexibility makes a collateralized line of credit an ideal tool for managing cash flow and covering short-term working capital gaps.
For controllers overseeing seasonal swings, this matters:
- Smooths revenue gaps between busy and slow seasons
- Covers short-term working capital needs without new loan applications
- Supports fast response to unplanned expenses
Business Credit Advisors serving Flexible Funding help owners match these tools to their actual cash flow patterns, rather than guessing at the right funding structure.
Research & Sources
According to the Federal Reserve's Small Business Credit Survey, access to financing remains a recurring challenge for small businesses, with many citing uneven cash flow and funding gaps as reasons for seeking outside credit. A revolving, asset-backed structure like a secured business credit line directly addresses that pattern, giving business owners a reusable source of capital instead of a one-time loan that doesn't flex with changing needs.
That same survey also finds collateral requirements to be one of the most commonly cited approval obstacles for small firms seeking credit. For context, unsecured bank programs sit at the other end of that spectrum: Wells Fargo's BusinessLine extends $10,000 to $150,000 with no collateral at all, while Bank of America's unsecured line sets the bar at a personal credit score above 700, two years in business, and $100,000 in annual revenue. Comparing the two shows why collateral works as a substitute for some of those credit and revenue thresholds, rather than an extra hurdle stacked on top of them.
How Does a Collateralized Line of Credit Work?
A collateralized line of credit works by tying a business's borrowing power to an asset the lender can claim if payments stop. Pledging collateral reduces the lender's risk, which opens the door to larger credit lines than an unsecured option typically allows. For business owners managing seasonal cash flow or funding expansion, that risk-reduction translates into real borrowing capacity.
Once approved, the business draws funds as needed rather than receiving a lump sum. Interest applies only to the amount actually borrowed, not the full approved limit. A company that draws only a portion of its approved limit pays interest on that drawn amount alone, keeping unused credit cost-free until it's tapped. Typical secured lines run from roughly $10,000 to $750,000, with limits commonly reaching up to about 80% of the pledged collateral's appraised value and annual rates often landing between 5% and 15%, noticeably below the 10% to 30% range unsecured lines typically carry.
Asset backed credit lines commonly use these forms of collateral:
- Equipment or machinery
- Inventory on hand
- Commercial real estate
- Outstanding invoices or receivables
- Cash deposits held with the lender
Does Collateral Increase the Credit Limit?
Yes. Applying with collateral secures a higher line of credit than applying without it. The pledged asset gives the lender a fallback if the business can't repay. Businesses without collateral to offer aren't shut out entirely; unsecured lines remain an option, typically at lower limits.
What Happens If a Business Can't Repay a Secured Line?
The lender has the right to seize the pledged asset to recover the outstanding balance, which is why matching the collateral type and value to the credit need matters before signing, and why working with an advisor who can match collateral type to lender requirements makes the difference between a modest limit and one large enough to fund real growth. VIP Business Credit, based in Sterling, VA, extends this guidance to businesses throughout Flexible Funding, connecting them to lenders suited to their assets and stage.
Secured vs Unsecured: Which Fits Your Business?
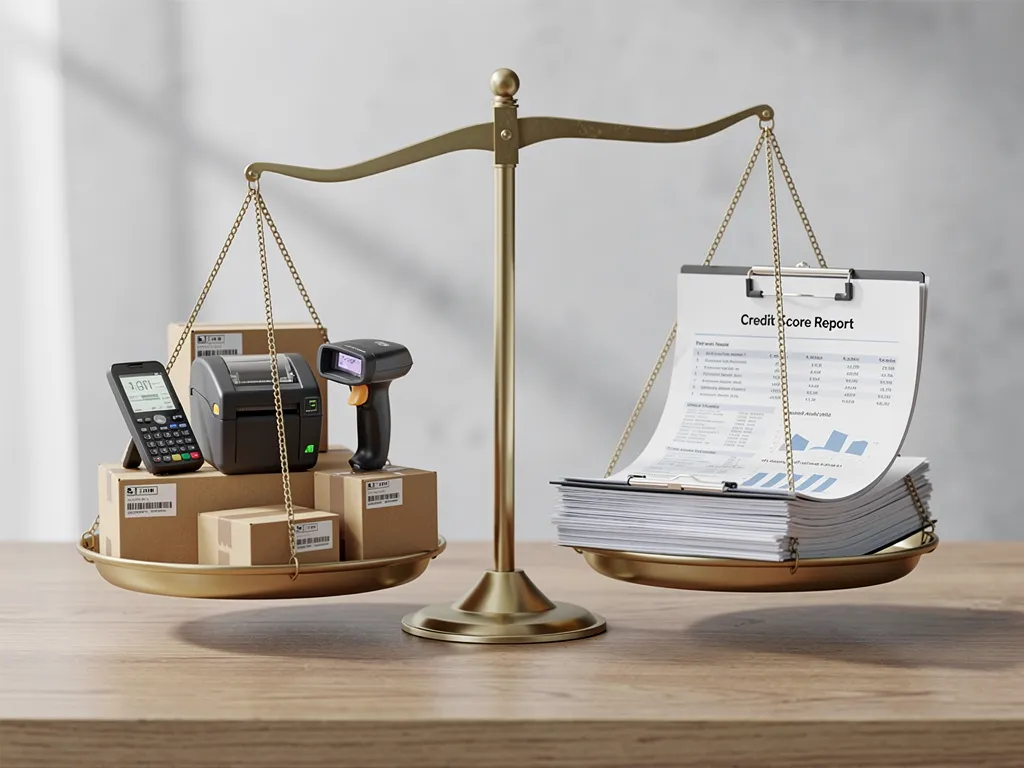
Choosing between the two comes down to one question: does the business have assets to pledge, or does its credit history carry the weight? A secured business credit line ties the credit limit to collateral. An unsecured line rests entirely on the strength of the business's credit profile. That single distinction shapes rates, limits, and how fast a business owner can access flexible funding when cash flow gets tight.
Secured options generally win on cost and size. Because the lender has collateral to fall back on, a secured line typically carries lower rates and a higher ceiling than an unsecured line that depends on creditworthiness alone. Founders chasing large working-capital limits for seasonal inventory or equipment often find this the more efficient path.
What if a business has no collateral to offer?
No assets on hand doesn't shut the door. Businesses without property, equipment, or inventory to pledge can still apply for an unsecured line of credit. Approval instead hinges on revenue history, time in business, and credit standing, with many bank programs looking for a personal credit score above 700, at least two years of operating history, and a meaningful level of annual revenue. Credit unions and banks also tend to require collateral once a credit line exceeds a certain size, often around $100,000, while smaller lines are more commonly approved on an unsecured basis.
Which option should a growing business choose?
The right choice depends on assets, urgency, and growth stage. Lenders structure both secured and unsecured options precisely. Business owners can match financing to what they actually have and need. Business loans can be a viable solution in such situations.
The choice also isn't necessarily permanent. A business that starts on a secured line can often graduate to unsecured terms once it builds a track record, lenders reviewing eligibility for that shift typically start account reviews around the 12-month mark, once a consistent history of on-time payments is in place. Reaching that milestone can mean the pledged asset gets released entirely, freeing it up for other use.
That speed difference is worth weighing alongside cost. Valuing and verifying a pledged asset adds a step a lender skips when underwriting is based on credit and revenue alone, so a business facing an urgent, time-sensitive expense sometimes finds the faster unsecured path worth the higher rate.
Newer companies chasing scale sometimes lean toward asset backed credit lines because pledged equipment or receivables unlock larger limits than credit history alone would support. A financial controller comparing both should weigh how much collateral the business can safely tie up before committing to a collateralized line of credit versus staying unsecured for flexibility.
What Assets Can Back Your Credit Line?
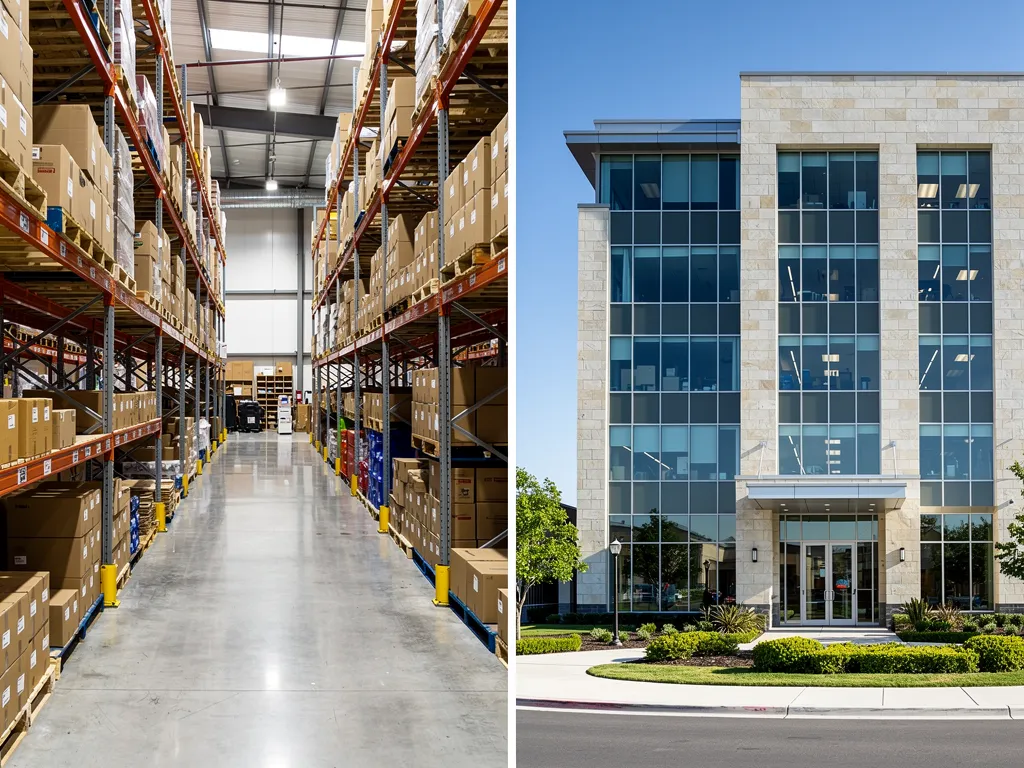
Equipment, inventory, real estate, and cash deposits can all secure a business credit line. These four categories give lenders tangible value to fall back on, which is why a secured business credit line often unlocks higher limits than an unsecured option. Businesses across Flexible Funding use different combinations of these assets depending on what their balance sheet already holds.
Understanding the mechanics matters more than the label. A revolving loan gives owners access to a set amount of funds they can draw against whenever cash flow gets tight. Borrowers only pay interest on what they actually pull from the line, not the entire approved limit. That structure is what makes asset backed credit lines so useful for seasonal expenses and unplanned costs alike.
What counts as collateral for a business line of credit?
Lenders typically accept four main asset types: business equipment, inventory on hand, commercial or investment real estate, and cash deposits held in a business account. Each asset type carries its own valuation process, and lenders weigh liquidity heavily. Cash deposits, for example, are viewed as lower risk than inventory because their value doesn't fluctuate.
Is a collateralized line of credit better than an unsecured one?
A collateralized line of credit generally comes with a higher limit and more favorable terms because the lender has recourse if payments stop. Businesses in Flexible Funding weighing this choice should consider which assets they're willing to pledge before applying. Many lenders also build in a path off collateral entirely: account reviews that determine eligibility for an unsecured line typically start at the 12-month mark, once a consistent record of on-time payments exists, and a company under the same ownership for two years with consistent qualifying revenue can often see the pledged asset released.
A Business Credit Advisor serving Flexible Funding can walk owners through which asset fits their goals, then match that choice to a lender built for it.
How Can a Secured Line Fuel Your Growth?
A secured business credit line fuels growth by turning collateral into working capital that stays ready whenever Flexible Funding needs it. Seasonal revenue swings, surprise repair bills, or a sudden bulk-order opportunity all draw on the same pool of funds, without a business owner scrambling for a new loan each time. Steady access like this replaces guesswork with a repeatable financing habit.
Collateral matters here. Asset backed credit lines use equipment, inventory, receivables, or real estate to secure approval, which typically unlocks higher limits than an unsecured product allows. For a business preparing for a growth push, that higher ceiling can mean the difference between hesitating and moving forward.
What makes a revolving line different from a term loan?
A revolving structure lets a business draw funds, repay them, and draw again, rather than receiving a single lump sum. Some online revolving lines deliver funding decisions in as little as one to two business days, a sharp contrast to SBA-backed products that often take several weeks to close, a point covered in more detail on VIP Business Credit's Business Lines of Credit overview. That speed matters most when a growth window is short.
Why does reusable credit matter for long-term planning?
Reusable credit means capital never sits locked away after one draw: businesses repay what they've borrowed, the credit line resets, and it's ready for the next opportunity, supporting repeated investment like restocking inventory, covering payroll during a slow month, or financing a new contract's startup costs.
A collateralized line of credit works best when treated as an ongoing tool, not a one-time rescue plan. Consider how the pattern typically plays out:
- Draw funds for a specific, planned expense.
- Repay based on actual cash flow, not a fixed rigid schedule.
- Rebuild available credit automatically as balances clear.
- Reuse the same line for the next growth phase.
Flexible Funding businesses that lean on this cycle consistently keep capital positioned for the moment growth actually knocks.
What Should You Check Before You Apply?
Business owners preparing for flexible funding should review three things first: rate structure, collateral requirements, and lender options. Skipping this review risks locking a company into rigid terms or pledging unnecessary assets as collateral. A short pre-application checklist saves time and protects a business's negotiating position at the table.
Rate structure matters most for businesses carrying revolving balances. Some lenders extend competitive rates on a secured business credit line and even let borrowers lock in a fixed rate on existing balances, protecting cash flow from sudden rate swings. That feature helps seasonal businesses that draw heavily during peak months and carry a balance into slower periods.
Collateral is the next checkpoint. Asset backed credit lines use equipment, inventory, receivables, or real estate to secure a higher limit than an unsecured product typically allows. Owners should confirm which assets qualify and how a lender values them before signing anything. Valuation methods vary widely between institutions.
Is a secured line of credit right for every business?
Not automatically. Deciding whether a collateralized line of credit fits a company depends on underwriting criteria, the assets available to pledge, and how comfortable an owner is tying business property to a credit facility. Companies with strong receivables or equipment often qualify for a secured line more easily than those without tangible assets to pledge.
How Does VIP Business Credit Help You Qualify?
Qualification starts with matching a business to the right lender, not applying blindly and hoping for approval. VIP Business Credit connects clients to more than 1,000 national and local lenders, giving each business a wider set of paths toward funding for Flexible Funding operations. That network matters because no two lenders weigh risk the same way. A business with seasonal cash flow gaps needs a different fit than one preparing for rapid expansion.
Matching starts with a clear picture of where a business stands today. VIP Business Credit runs a pre-qualification scan that takes about two to five minutes and carries zero impact on personal credit, showing business owners which business credit profile funding programs they can access right away and which ones need more groundwork first, preventing wasted applications and protecting the business's credit profile from unnecessary inquiries. For a business serving Flexible Funding, that clarity translates into faster, more confident decisions about growth capital.
What Financing Options Does VIP Business Credit Help Businesses Access?
Businesses working with VIP Business Credit gain access to several credit structures suited to different funding needs. Each option carries its own trade-offs between flexibility, cost, and collateral requirements.
- A secured business credit line, backed by business assets, often unlocks higher limits and lower rates for Flexible Funding operations managing uneven cash flow.
- Asset backed credit lines, tied to equipment, inventory, or receivables, help growing businesses fund expansion without giving up equity.
- A collateralized line of credit gives lenders added confidence, which frequently translates into better terms for the borrower.
Does Location Affect Access to VIP Business Credit's Services?
Location does not limit access to this funding guidance. VIP Business Credit is based in Sterling, VA, and serves clients digitally through a lender network spanning the country. Businesses supporting Flexible Funding work with a Business Credit Advisor remotely, without needing to travel, while still building EIN-based credit that separates personal and business liability.
FAQ
What assets can back a secured business credit line?
Equipment, inventory, real estate, and cash deposits can all serve as collateral, with the appraised value of each asset shaping the credit limit a lender is willing to extend.
How does VIP Business Credit match businesses to their financing?
VIP Business Credit connects entrepreneurs to over 1,000 national and local lenders, using local Business Credit Advisors to match collateral with the right program.
Why is a secured line considered cost-effective for Northern Virginia businesses?
Interest applies only to the amount actually borrowed. Repaid balances become available again, letting Northern Virginia businesses avoid reapplying every time working capital runs tight.
What's the difference between a secured business credit line and a term loan?
A term loan delivers a lump sum repaid on a fixed schedule. A secured business credit line stays open and reusable: the business draws funds, repays them, and draws again as needs arise, paying interest only on the amount actually borrowed.
Can a business move from a secured line to an unsecured one over time?
Often, yes. Lenders typically begin reviewing eligibility for unsecured terms around the 12-month mark, once a business has built a consistent record of on-time payments, and reaching that milestone can free the pledged collateral for other use.
Conclusion
In closing, secured business credit lines represent a strategic bridge between the assets you've already built and the flexible capital your business needs to grow. By putting collateral to work thoughtfully, you transform idle resources into working capital while strengthening your company's credit profile independent of personal guarantees. This foundation, built on clear business identity and consistent credit management, positions your enterprise for better terms, higher limits, and sustainable expansion. The path forward requires intentional planning and disciplined execution. The payoff is a business that stands on its own financial merit.
About The Author
Lee Johnson is a seasoned Real Estate Investor, Business Growth Strategist, and Master Certified Professional Coach, whose mission is to see people achieve financial freedom and live a life filled with abundance and happiness. He holds a Bachelor of Science from Fairleigh Dickinson University and a Master of Business Administration from the University of Phoenix, and brings more than 25 years of professional experience along with over 500 hours of coaching. Since 2005, Lee has built a personal real estate investment portfolio exceeding 1,700 units valued at approximately $254 million across multiple U.S. markets.
Lee's mission is to help small business owners, including those in home services, trucking, and real estate, achieve financial freedom by first establishing a strong business credit profile, then accessing the highest loan amounts at the best terms available. He and his team serve business owners nationwide through VIP Business Credit's signature 12-month business credit coaching program.
Connect with Lee and VIP Business Credit:
- 📞 Phone: +1 (571) 248-3863
- ✉️ Email: [email protected]
- 📅 Consultation: Schedule A Business Financial Health Strategy Call
- 🌐 Website: vipbizfunds.com
- 🎯 FREE Business Funding Pre-Qualification Scan: Take the Scan
Serving Sterling, VA and the surrounding Greater Washington, DC region, including Reston and Herndon and Ashburn.


